Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 587

Looking beyond banks for dividend income

The Big Four banks have had a stellar run over the past 12 months. For instance, Commonwealth Bank (ASX: CBA) is up 56% during the period, and 43% year-to-date. It’s a head spinning move for the ASX’s largest stock with a market capitalization of $260 billion.
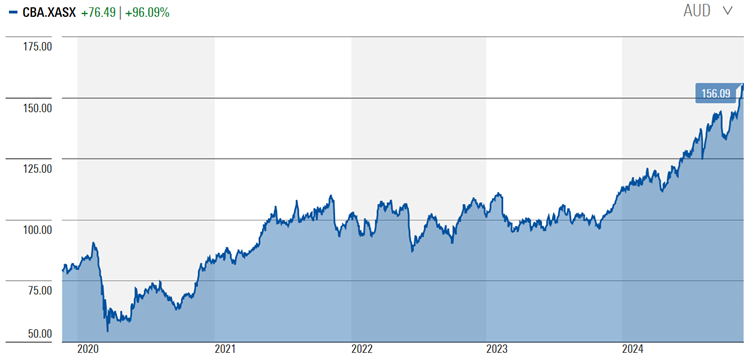

Source: Morningstar

Is CBA a $115 billion better business (the equivalent of Westpac's current market capitalisation) than a year ago? Not if you go by earnings, which were down 2% in the last financial year. The prospects for future earnings aren’t impressive either, with most analysts looking for mid-single digit growth over the next three years. And these analysts assume provisions for bad debts remain near all-time lows – a big assumption.

What explains the rampant run-up in bank share prices? ‘Fundamentals’ as we like to call them in the finance industry don’t explain the moves. More likely, it’s liquidity. Mining stocks have been in the doldrums and large fund managers and super funds have essentially been forced to buy the banks to get returns. Passive ETFs have amplified the price rises.

Gone are the good old days

Once upon a time, the banks offered high starting yields (due to lower prices), with steady, growing dividend streams, but that’s now a distant memory. For instance, CBA grew dividends by a compound annual growth rate (CAGR) of 9.2% in the decade to 2003, by 8.9% in the decade to 2013, but by just 1.74% in the decade to 2023. Similarly, Westpac increased dividends by 9% CAGR in the ten years to 2003, by 9.5% in the following ten years, yet dividends declined by 3.1% per annum in the decade to 2023.

The slowing dividend growth is the result of slowing earnings growth, due to a host of reasons. Increased competition for deposits and loans, greater capital requirements, slowing credit and economic growth, and other factors have played a part.

Future earnings growth also looks tepid at best, and consequently so does dividend growth. Even with franking credits, the picture doesn’t appear anywhere near as positive as it did over much of the past 40 years.

Yet, the current share prices don’t reflect this. CBA is sporting a price-to-earnings ratio (PER) of 27.7x, making it the most expensive bank in the developed world, and by a distance. The PERs of the other banks are cheaper, though far from cheap: Westpac (ASX: WBC) at 17.4x, NAB (ASX: NAB) at 17.5x, and ANZ (ASX: ANZ) at 15x.

These high prices have left dividend yields at the lower end of history, with CBA’s yield at 3%, Westpac’s 4.5% NAB’s 4.3%, and ANZ’s at 5.1%.

Looking beyond banks

Banks have been the go-to source of dividend income for investors for years, yet they don’t offer the same prospects for high, growing income that they once did. What should investors do?

The yields on banks aren’t disastrous, so I’m not suggesting that it’s time to cut and run from them. However, it does seem an opportune time to look beyond the banks for better dividend prospects.

Here are some ideas:

Steady compounders. These are potential bank alternatives, offering steady, growing income. I like medical insurers such as Medibank Private (ASX: MPL) and NIB (ASX: NHF), with dividend yields of 4.4% and 5% respectively. Yes, there are risks around hospital cost negotiations, yet these seem to be at least partially priced in. While pricing is set by government, growing demand for private healthcare should ensure increasing earnings and dividends for many years.

Origin Energy (ASX: ORG) is another one in this category. It’s the country’s electricity and gas supplier and its attractive prospects have made it the subject of takeover bids. With a 5.1% yield and reasonable valuations, it deserves a place in income portfolios.

Dividend growers. This group of companies comprises great businesses with relatively low dividend yields but with opportunities to grow those dividends at a brisk clip. Brambles (ASX: BXB) is one, offering a yield of 2.6%, albeit only partly franked. Resmed (ASX: RMD) is another, with a paltry yield of 0.8%, but with a great track record of increasing dividends (more than 7% CAGR over the past ten years). And a personal favourite is Washington H. Soul Pattison (ASX: SOL). It has raised dividends in each of the past 24 years, by 10% per annum. It’s a phenomenal track record that’s unlikely to be repeated. However, the future still appears bright for the conglomerate. Soul Patts offers a 2.7% current dividend yield.

Comeback stories, returning cash. Here are stocks where there is real value and the potential for business turnarounds and for cash to be returned to shareholders. Ramsay Health Care (ASX: RHC) offers a possible opportunity. Better returns should come from an increased focus on its Australian assets. Also, negotiations with insurance funds over costs could prove a catalyst for the stock.

Perpetual (ASX: PPT) is another one. Everyone hates the company given its history. Yet, it’s inexpensive and if a proposed demerger goes ahead, that should result in about a billion dollars finding its way back to shareholders.

What didn’t make the list

There are notable absentees from the stock ideas above. First, there are no miners. I just don’t think miners deserve a large spot in portfolio given their volatile earnings and dividends. Second, the supermarkets are excluded too. Despite recent issues, the shares still seem on the expensive side and dividends aren’t compelling. Government pressure is effectively capping pricing, and they’re still dealing with cost issues.

What about dividend ETFs?

Given ETFs are all the rage, the inevitable question is whether there are ETFs that can provide investors with decent dividend income. My issue with a lot of the dividend ETFs is that they’re loaded with banks and materials companies. For example, the largest dividend ETF, Vanguard’s Australian Shares High Yield ETF (ASX: VHY) has 66% exposure to financials and materials, in line with its benchmark. It’s fine if that’s what you’re looking for. However, if you want to diversify away from banks and miners for yield, then please carefully read the fine print of dividend ETFs.

Are international shares an option?

International shares are an option for those seeking income. However, these shares don’t have the franking credits that are on offer in Australia. For this reason, I’ve always looking for yield in Australia and growth outside of it. It’s a strategy that may not suit everyone and depends on your circumstances.


James Gruber is editor of Firstlinks and Morningstar.


  •   20 November 2024
  • 9
  •      
  •   
9 Comments
Peter Latham
November 21, 2024

James. Given the high price of Banks and Financials at the moment, a topical and timely article !

LEATH HUNT
November 22, 2024

the reason people are not selling CBA shares is because of capital gains tax. Many investors were in the original float at $5.40

CLK
November 24, 2024

Leath, with DRP since its original float what would be the CGT for one share if sold today …

Ramon Vasquez
November 25, 2024

Correct !!!

Steve
November 21, 2024

Passive ETF's have amplified the price rises? Amplified? A bog standard passive ETF simply mirrors the index, buying all stocks (in its index) in the same proportion as the market at the time. If anything this would be expected to amplify the price of smaller stocks wouldn't it? I agree its probably liquidity, you see plenty of stories where people who have owned the banks for many years and done very well simply refuse to sell. Not sure how much juice is left in this piece of fruit though. Switch to hybrids or bonds, get equal or better yields with much lower capital risk. The potential for risong yields is I think dwarfed by the risk of a capital loss when common sense appears. Just a thought.

greg
November 22, 2024

no - most index ETF's buy market weight, so as the banks % of the market has increased, due to there out-performance, the ETF's buy more banks as a %. Becoming a self fulfilling loop. Until someone or an algorithm that looks at fundamentals starts selling. Some ETF's buy equal weight MVW, and some can use filters - AQLT but most SFY, A200 etc use market weighting.

SGN
November 22, 2024


How times have changed Bank Hybrids are paying higher dividend yield than Bank shares.Perhaps time to short some bank shares for bank hybrids before hybrids are potentially phased out.

Neil Davis
November 24, 2024

Blue
B
Brambles ASX code is BXB not BSL which is Bluescope Steel.

James Gruber
November 24, 2024

Neil, I had BSB of which there is no code on the ASX! It's corrected now.


Leave a Comment:

RELATED ARTICLES

The best income-generating assets for your portfolio

Bank reporting season scorecard November 2025

The naysayers may be wrong again on the Big Four banks

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.