Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 238

Small and mid-cap resources review 2018

(This introduction is an edited extract from the longer research book attached at the end of the article).

How did 2017 stack up?

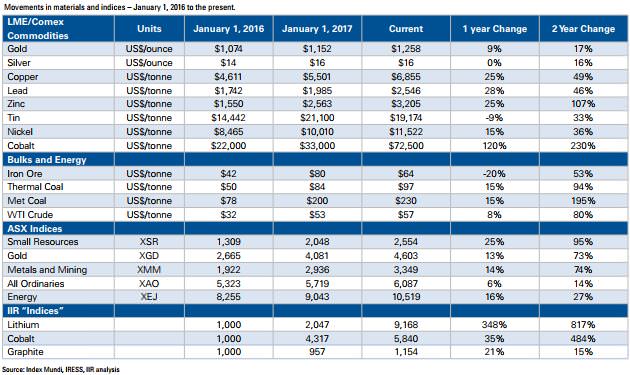
How times have changed since the end of the resources bust. The market began to turn at the beginning of 2016, and we have seen significant gains in all sectors and metals, as shown in the following table. The figures show strong performance across most market sectors and individual commodities over the last two years.

The resurgence is largely in response to an improving global economy, which fared better than expected in 2017, and is expected by some to carry into 2018. However, given that the Chinese economy is maturing, it is unlikely to repeat the rapid growth that characterised the early to late 2000s which led to the previous 'super cycle'.

2017 was an excellent year for the resources sector, building on the solid foundations achieved in 2016. I recall my first 121 Conference in London in early 2016 where a panel discussion suggested that, given the prevailing environment, some junior explorers should be privatised, much to the disgust of at least one managing director of a listed junior miner.

The headline story of the 2017 year was the battery metals, particularly lithium and cobalt. These have been driven by the expected growth in demand for rechargeable batteries, particularly for electric vehicles. Although it has not performed as well, graphite has held its own. We would expect interest in these commodities to continue, but with some flattening and consolidation.
We have noticed in the current cycle that most companies seem to be better quality than in the exuberance of the last boom. This is largely due to shareholders (many who were burnt in the bust) demanding more cost and project management discipline from company management. Many companies have a good product to sell and are run by quality personnel.

Due to the rejuvenation in the junior miner sector, quality smaller companies are once again able to raise funding for exploration, appraisal and development activities, markets are reacting positively to favourable company news, and share prices are continuing to move in the right direction.

Smaller companies, in contrast to the majors, boast management with significant ‘hurt money’ invested, meaning they are often run on the smell of an oily rag. Smaller independent resource companies are also much more leveraged to the strongly-performing commodities of 2016/2017.

What’s in store for 2018?

The resource space in 2018 will be volatile, but amid an overall improving tone in demand and supply fundamentals. One of the biggest drivers in sentiment early in 2017 was ‘The Trump Effect’. There was a lot of near-term enthusiasm in commodity markets as speculators gambled on an infrastructure-led spending spree, but it was largely overblown. The biggest factor in the resource sector remains China, easily the largest consumer of commodities in the world economy.

Our view is that the key mainstream commodities are the base metals, and in particular nickel, which is showing signs of life, with the battery resources also in the mix. Interestingly, the world’s major mining houses have relatively little exposure to the minor metals and are still heavily reliant on iron ore, coal and copper for the bulk of their earnings. We expect the gains in bulk commodities like iron ore and coal to subside, as supply is abundant and there have been temporary factors within China that have sucked in imports and supported price increases.

Australian miners should continue to benefit from strong commodity prices in A$ terms. Overall, we expect the strength in the sector to continue into 2018 due to our forecasts for strong metals prices, driven by a relatively healthy global economy.


Mark Gordon is Senior Analyst at Independent Investment Research. Gavin Wendt is the Founder of MineLife and the Senior Resource Analyst. These comments are general in nature and do not consider the circumstances of any investor.

The full Independent Investment Research - Small and Mid-Cap Resources January 2018 Review (including specific comments on many junior resource companies) can be accessed by clicking the image below. The purpose of this research book is to present a diverse group of resource companies worthy of further consideration.
 

  •   2 February 2018
  •      
  •   


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.