Australian investors have traditionally relied on two primary sources of income: dividend-paying shares and bank hybrids. More recently, private credit supplemented these income sources.
Each offered a compelling proposition. Equities and bank hybrids delivered attractive post-tax income and private credit offered an illiquidity premium in exchange for locking capital away.
However, the market has changed.
Investors can now access yield from high-quality Australian public credit that in many cases exceeds yields available from fully franked Australian equities. Public credit also sits higher in the capital structure, benefits from contractual income streams, and can be accessed through vehicles offering daily liquidity. Yields on private credit, by contrast, have steadily declined as demand for the asset class has increased.
Yields exceeding 6% are currently available to investors from a broad range of high-quality companies in public credit, an asset class that is liquid, highly regulated and has daily independent pricing transparency. Investors no longer need to accept the additional risks embedded in private credit, or the lower income yield now on offer from equities.
The decline of franked dividend income
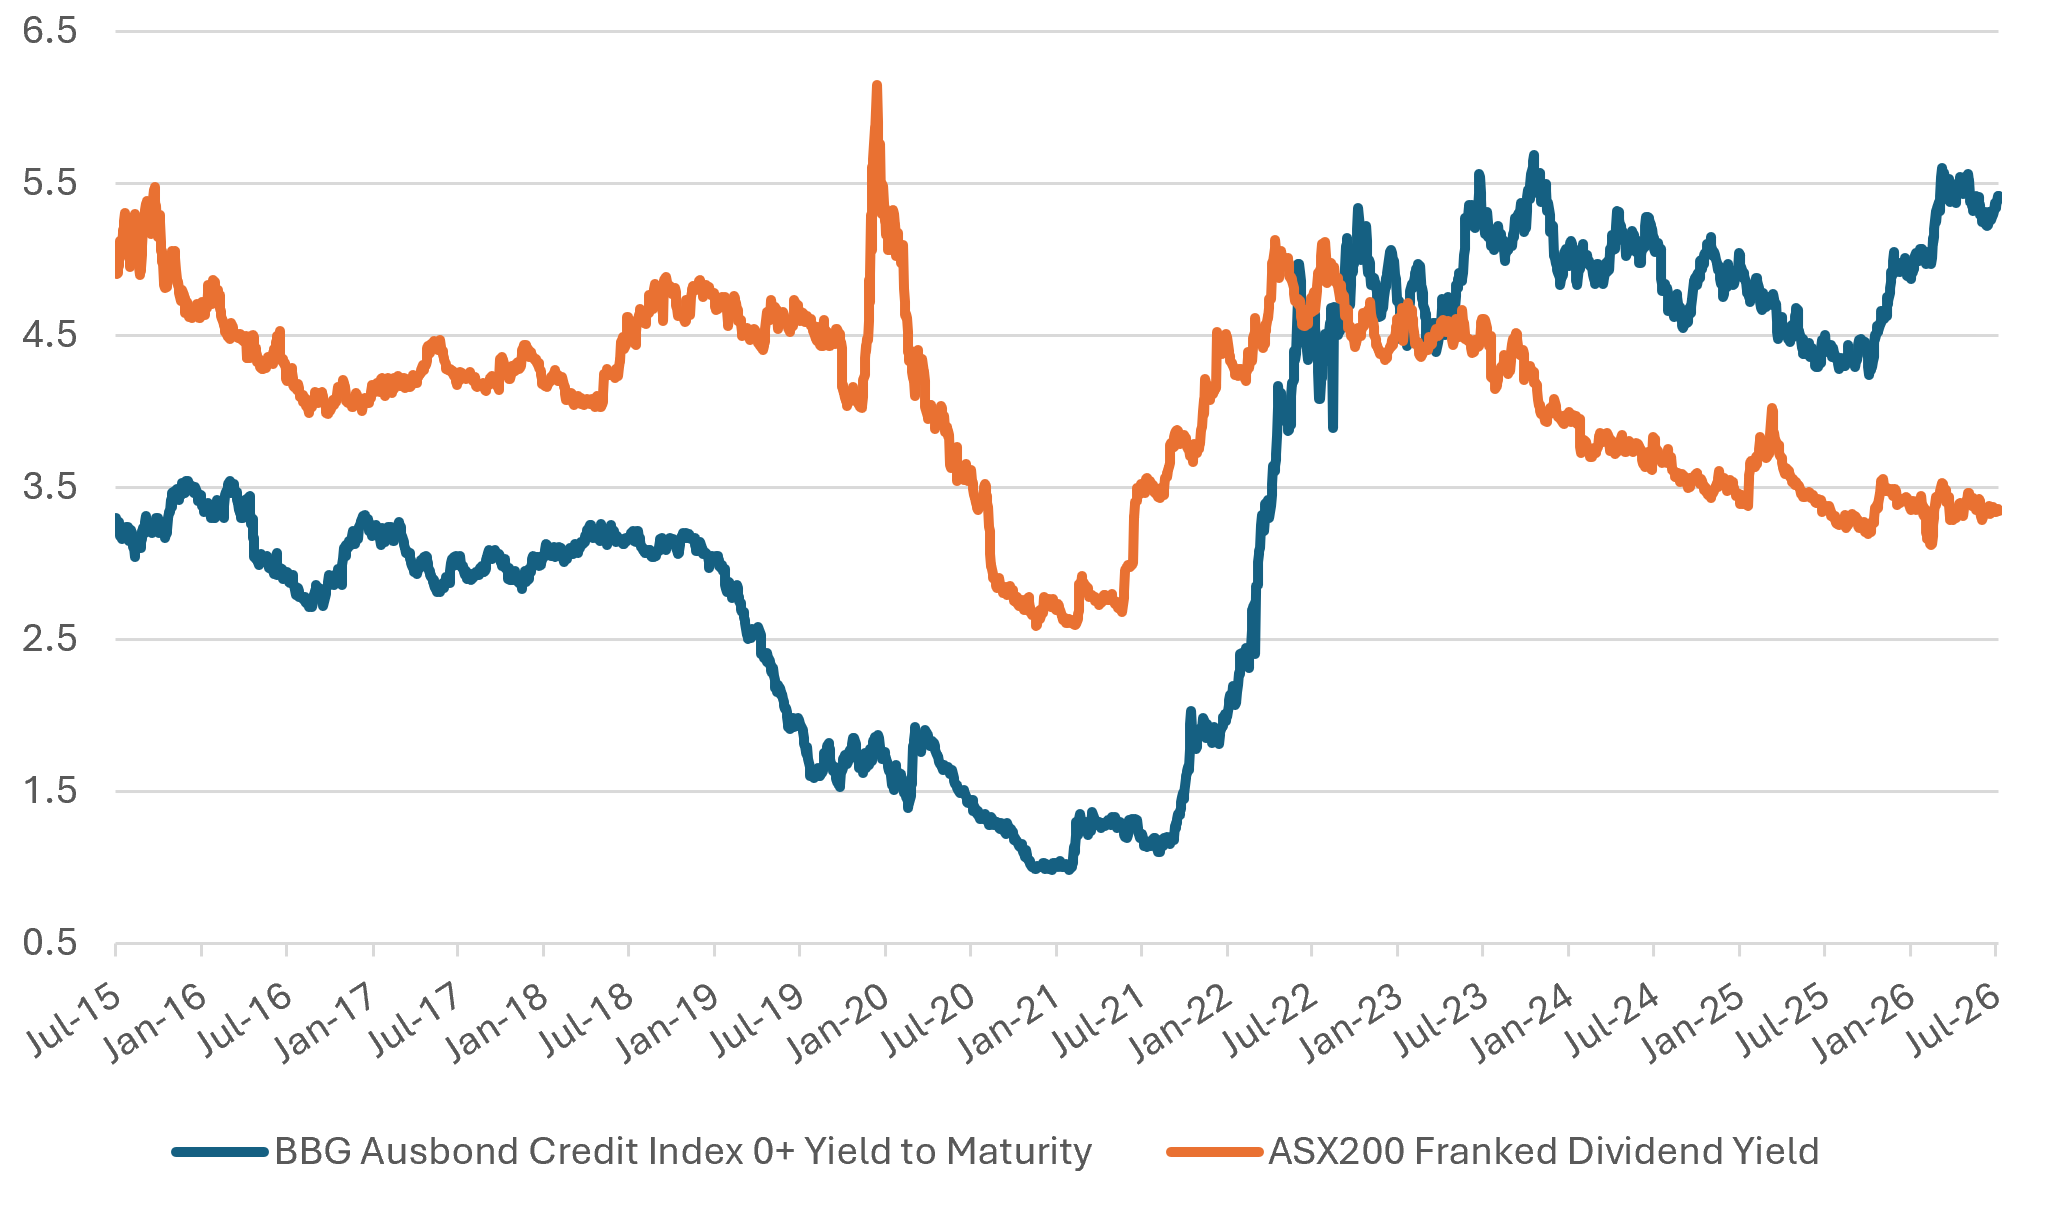
Since 2010, the ASX200 has provided investors with a grossed-up dividend yield of between 4%-5% along with capital appreciation, with the exception of 2021 (2.75%), when COVID highlighted the discretionary nature of dividends (see chart 1). However, since 2022, the rally in equity markets has outpaced dividend growth, which has resulted in the dividend yield dropping to 3.3%. Up to this point, investors have been rewarded through capital gains, but for the incremental investment dollar, the ASX200 is offering a lower income yield and/or a greater risk of capital loss if the index yield returns to the 4-5% range.
Chart 1: Australian Credit versus Equity Income
Source: Bloomberg, July 2026
More recently, public credit and equity income yields have diverged. Higher underlying interest rates, together with wider credit spreads, have pushed yields higher, creating a situation where investors can access income streams that often exceed fully franked dividend yields. The chart below shows just a few examples where senior and subordinated yields on listed companies exceed the franked equity dividend yield.
Chart 2: Comparing yields across the capital structure
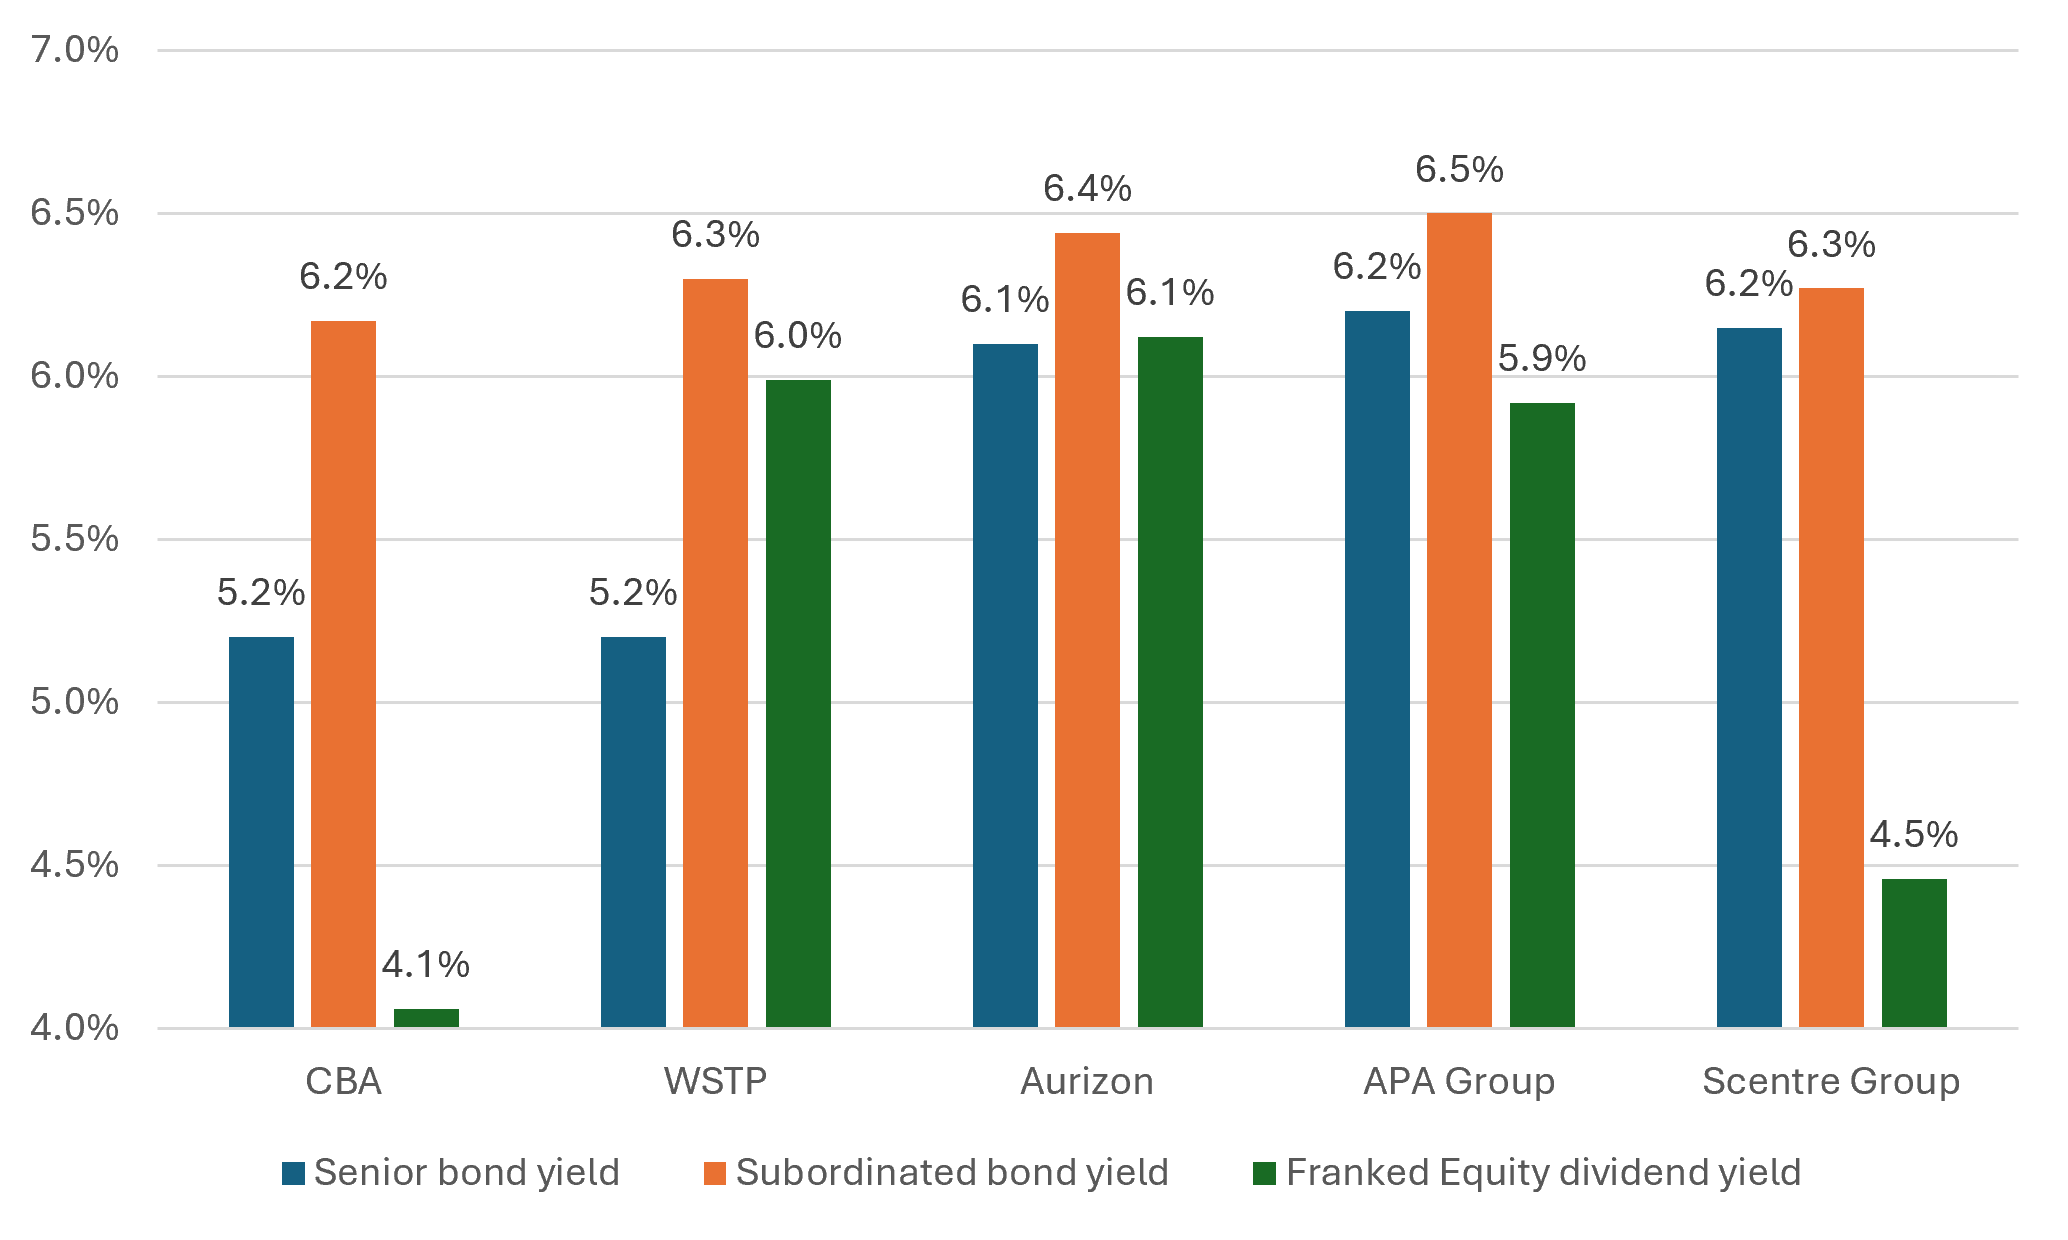
Source: Bloomberg, July 2026
This matters because dividends are discretionary, whereas bond coupon payments are a legally binding obligation, subject to the terms of the security and the issuer remaining solvent. Dividends can be increased, reduced or cancelled altogether depending on company profitability, economic conditions, capital requirements, and/or management decisions. This is not the case for bonds.
Furthermore, bondholders must be paid before shareholders. They sit higher in the capital structure and enjoy a priority claim on a company's cash flow.
Whilst equities remain a good source of long-term capital growth, high-quality public credit can offer income-focused investors greater contractual certainty and a higher position in the capital structure, with yields that in many cases now exceed grossed-up dividend yields.
The value of liquidity
Over the past decade, achieving higher yields has often meant investors have accepted lower liquidity and lower quality by investing in Australian private credit funds. Post the Global Financial Crisis (GFC), when interest rates were near zero and income was scarce, that trade-off looked attractive.
Today, it is less compelling.
Public credit yields are now comparable with private credit, but without the lock-ups, high fees, valuation opacity and constrained liquidity that define many private market investments. This is particularly important because liquidity is often underestimated until it is needed. Opportunities emerge. Personal circumstances change. Markets move.
As a regulated, liquid asset class, public credit gives investors the ability to respond, private credit does not.
At the same time, investors should be cautious about equating smoother returns with lower risk. The apparent stability of private credit is partly a function of infrequent pricing. Assets that are not regularly traded naturally experience less visible volatility. That does not mean the underlying risks have disappeared. In fact, risk can be exacerbated by the lack of transparency inherent in these markets.
Income should be contractual, not conditional
Perhaps the strongest argument for public credit is the nature of the income itself.
Income investors are often seeking reliability as much as yield. The ability to plan around regular, predictable cash flows is a central part of the investment objective.
Public credit is built around contractual income payments. The amount, timing and frequency of coupon payments are established when the bond is issued.
That certainty stands in contrast to both equities and parts of the private credit market.
Dividend payments depend on company performance and board decisions.
Private credit investments can also include complex documentation features that allow borrowers to defer cash interest payments under certain conditions.
Public investment grade bonds generally offer a much simpler proposition: the borrower is expected to pay investors in cash and on time.
In an environment characterised by greater economic uncertainty, that certainty has value.
Why quality matters
Income should not be evaluated solely on yield. The quality of the borrower matters.
The strength of the Australian public credit market is that it remains dominated by investment-grade issuers, including major financial institutions, infrastructure businesses, utilities and other established corporate borrowers like Woolworths and Wesfarmers.
In Australia, these companies operate in a favourable competitive environment, often enjoying a monopoly or duopolistic position. Many operate essential services, generating resilient CPI-linked cash flows and are also required to maintain regulated and transparent reporting standards.
The combination of high yields, quality and seniority within the capital structure is difficult to replicate elsewhere.
A better income proposition
For much of the past decade, income investors faced an uncomfortable choice: accept lower yields from defensive assets, or chase higher yields by sacrificing liquidity, transparency or credit quality.
Today, investors no longer need to accept that trade-off.
Australian public credit offers a competitive income solution with the benefit of high-quality exposures, contractual cash flows, transparent pricing and daily liquidity.
In our view, public credit is no longer just the defensive option. For investors focused on income, it now stands out as one of the more compelling opportunities available.
Helen Mason is Head of Credit, Australia at Schroders Investment Management Australia, a sponsor of Firstlinks. Issued by Schroder Investment Management Australia Limited (ABN 22 000 443 274, AFSL 226473). This article does not contain and should not be taken as containing any financial product advice or financial product recommendations. This article does not take into consideration any recipient’s objectives, financial situation or needs. Schroders does not give any warranty as to the accuracy, reliability or completeness of information which is contained in this material.
For more articles and papers from Schroders, click here.