Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 384

Offices will live on in a post-COVID world

COVID-19 has put the spotlight on all asset classes, and commercial property is no exception. David Harrison, Charter Hall’s CEO & Managing Director, recently spoke at the Morningstar Individual Investor Conference and explained why quality office buildings are still an attractive investment. Here is a summary of the reasons David is still optimistic on the outlook for the office sector.

Structural vs cyclical change

There is a lot of media hype on the office sector. The million-dollar question is whether COVID-19 will create a structural change or a cyclical change, as we have witnessed with other past economic downturns.
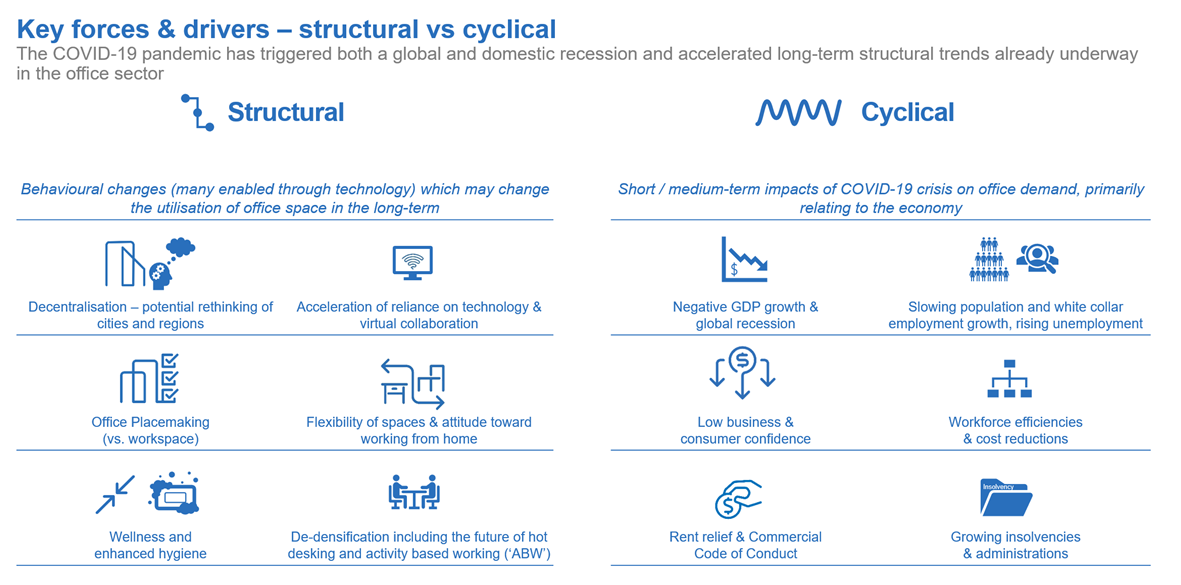
Charter Hall’s view is that this is another example of a cyclical correction. While there will be a short-term reduction in demand and vacancy factors will go up, we entered this crisis with some of the lowest vacancy rates we have seen in both the Sydney (3.9%) and Melbourne (3.2%) CBD markets. Compare this to cities like Chicago (16.2%), LA (13.0%) and New York (7.7%). This will buffer any short-term reduction in demand.

Clearly, we are already seeing companies announcing cutbacks in headcount in response to the economic downturn. But an offsetting trend is an increase in the amount of space per person in occupying in a building. Go back 30 years, it was 25sqm per person but pre-COVID, it went as low as 10sqm per person. The pendulum had swung too far - you cannot have that sort of density and operate efficiently.

The end of 'activity-based working' extremes

The concept of 'activity-based working', where two or three people might occupy one seat on a particular day, and as people went to a meeting or left the office, their seat was occupied by some else, is unlikely to be the predominate workplace system in future. There will be a move back to fixed seats with some clustering in neighbourhoods and there might be some movement in those neighbourhoods on a weekly basis but not on an hourly or daily basis.

With the emphasis on workplace health, the densification of workplaces will return towards 14-16sqm per person. As a result, businesses will need more space for the same amount of people in our offices and this will help offset the cyclical change in demand.

CEO and business leaders need to deal with productivity and risk management. One of the problems that has arisen out of COVID-19 and working from home is that risk goes up. It is difficult to have a detached workforce no matter what the business. There will be a desire, particularly over the medium term, for staff to return into an office environment. Yes, there will be flexible arrangements, and in some industries, like call centres, they may be able to work efficiently from home 100% of the time. Most people will spend more time in the office and it is unlikely that we are going to see a long-term structural change in mass working from home.

Health and wellness in the office

In response to concerns about the workplace environment, there will be more focus on technology in buildings and a flight to quality by tenants. New buildings that provide the latest in health and hygiene facilities (such as ultraviolet hand rail sanitiser on building escalators and in air handling units, touch-free technology for doors and lifts and temperature scanners in the entrance) will be in demand. Buildings that fall short will not be able to compete.

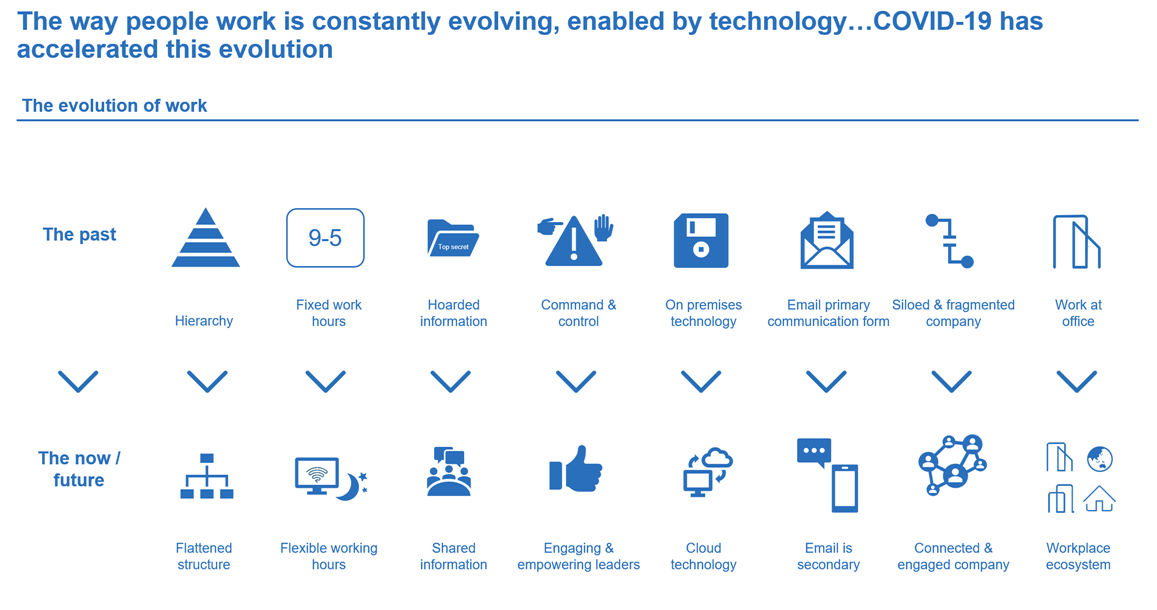
We’ve seen a lot of change over the past 30 years. The office will continue to evolve and adapt. We’ll see more flexible working hours, more shared information, and more innovative technology. But at the same time, there will be a greater focus on collaboration and empowerment. Whether in the CBD or the suburbs, a well-designed, productive, connected workplace environment will allow a company to attract and retain talent at the same time helping to foster the company’s identity and culture.
CBD vs the suburbs: It’s not one or the other

Another refrain is the death of the CBD and the rise of suburban office markets. We are believers in both CBD and metropolitan markets. Charter Hall is one of the largest owners of office property in Parramatta. We recently bought a 34,947 sqm office property in Macquarie Park in suburban Sydney that is leased to the NSW Government for 12 years.

The CBD is, and will continue to be, the dominant office market. Across Australia, there is 11 million sqm of quality (Premium and Grade A) CBD space and circa 3 million sqm in non-CBD areas.

To meet the needs of staff, businesses want a quality retail amenity and good public transport. It is difficult to have a suburban location in any state that has the convenience and centralised public transport system of a CBD. Apart from Parramatta and North Sydney in Sydney, most states have little in the way of mature suburban markets. There are some exceptions, but there will not be a massive structural change in office demand moving from the CBD to the suburban market.

Population growth drives demand and it will again

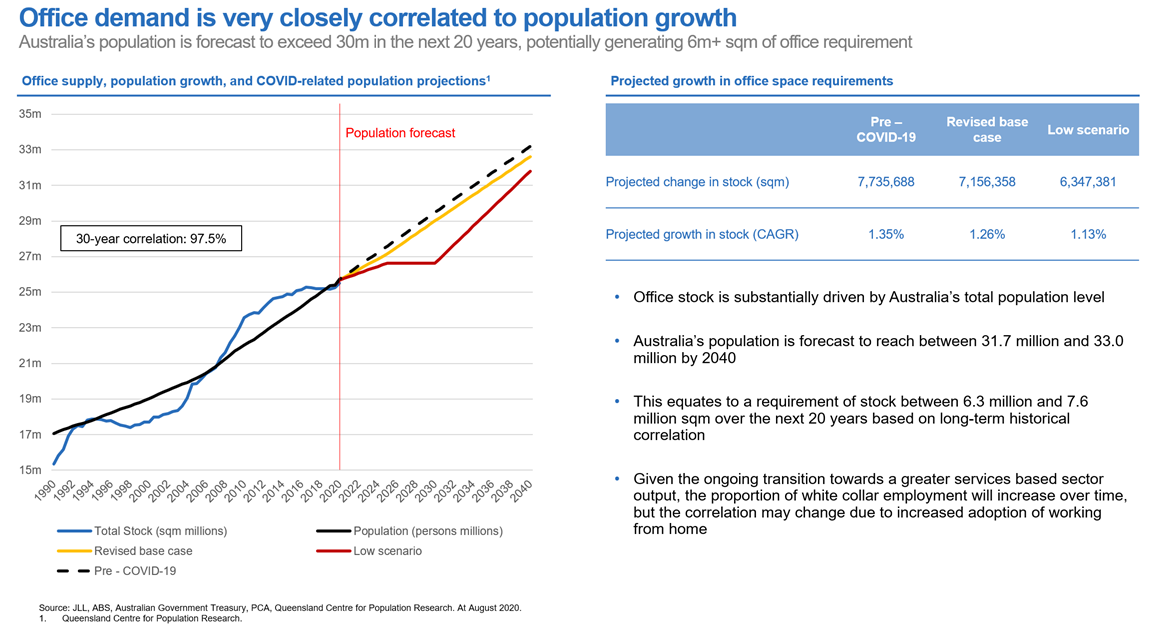
There is a strong correlation between office demand and population growth. Obviously, COVID-19 has driven a short-term reduction in net migration. Hopefully, after the health crisis, we will see a return to pre-COVID net migration levels, which in turn will drive office demand. Population growth is essential if Australia is to continue above average economic growth compared with Europe and North America and many other parts of the world.
Capital continues to chase office assets

Some of the largest global institutional investors are investing in Australian office buildings and this will continue. Two recent examples include Peakstone, a Singaporean investor, acquiring a Sydney CBD office building in June 2020 for $530 million while in October 2020, Deka Immobilien, a German investor, paid $452 million for a Melbourne CBD office building.

One of the key reasons they are choosing Australia is because of the lease structures that allow 3.5% to 3.75% annual fixed rental growth. Investors want a growing distribution yield in a low inflation, low interest rate environment. Australian commercial real estate offers an attractive relative investment return compared with other major global markets. We expect office transaction pricing to remain firm and reflect the large gap between office yields and the 10-year bond rate.

Winners and losers

We are not as concerned about the office market as some. Clearly, industrial and logistics will be the stand-out performer for the next five years driven by the explosion in e-commerce while the supermarket and convenience end of the retail market will be more stable.

While there will be winners and losers in the office market, modern buildings with long leases to quality tenants will perform well. Older buildings with shorter leases will underperform.


Adrian Harrington is Head of Capital and Product Development at Charter Hall, a sponsor of Firstlinks. This article is for general information and does not consider the circumstances of any investor.

For more articles and papers from Charter Hall, please click here.


  •   18 November 2020
  • 2
  •      
  •   
2 Comments
David Jones
November 18, 2020

We'll see. The push for more WFH is not only a COVID issue but many people prefer it, at least a few days a week. Also solves some of our city transport capacity problems.

Warren Bird
November 18, 2020

David Jones, you make a very valid point, but I don't think the article contradicts what you are saying. It just posits the very genuine argument that for each component of reduced demand for office space because of more WFH, there is an offsetting force at work - when people do come into the office, they're going to want their own desk, or at least a desk that hasn't been sat at by several other people since they were last in. They're going to want a wider desk so they're sitting further from their colleagues than at present. They're going to want wider corridors to walk in so they don't have to pass too closely to others when they're moving around.

And responsible business managers will cater for that in the interests of health and safety.

All of that will mean that the square metres of floor space a business will need in an office isn't just going to go down in line with WFH arrangements. Who knows exactly how the relativities will play out, but as both an office owner and the CEO of a small business (about 30 staff), I'm anticipating that in a few years' time we'll still have a similar amount of office space as we currently do.

You mentioned city traffic, another valid point. I think this goes further and a topic I haven't seen much commentary on is the impact of the technology that enables WFH on travel. There will definitely be an increase in the number of meetings that have multiple locations linked by video technology and far fewer meetings involving folk who've flown in from all over the place, or even driven across the city. Hotels and airlines will need to find new travellers to offset the reduction in business travel.


Leave a Comment:

RELATED ARTICLES

Not all non-residential real estate performs the same

AREITs are not as passive as you may think

A-REITs: what the market gloom is missing

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.