Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 447

Is your portfolio in need of rebalancing?

Summer’s nearly over and it’s almost time to relegate the swimwear and shorts to the back of the cupboard. Items on the ‘to do’ list include mentally preparing for a physical return to the office and restarting an exercise regime. Regardless of which life stage you’re at, it is also good to put a review of your investment portfolio on your list and consider whether a rebalance is necessary.

The value of rebalancing

Does the allocation of your portfolio to shares, fixed income, property and cash look right? If your portfolio allocations have shifted, such as due to the recent falls in many share prices, take this opportunity to retune your asset allocation for the eventual rebound in the stockmarket.

Or if recent market falls felt more like a downhill run than momentary ups and downs in the road, now may be a good time to reconsider your risk tolerance as it is likely that your risk appetite and asset allocation are not in sync.

The low-yield environment poses a challenge to income-focused investors who hope to use portfolio income to support spending. In the past, as illustrated in Figure 1, a broadly-diversified portfolio of equity and fixed income could generate a ‘natural yield’ (that is, the return of the portfolio in the form of dividends and interest) equal to 4% or 5% of the portfolio’s value, consistent with conventional guidelines for spending from a portfolio. Today, that is no longer the case.
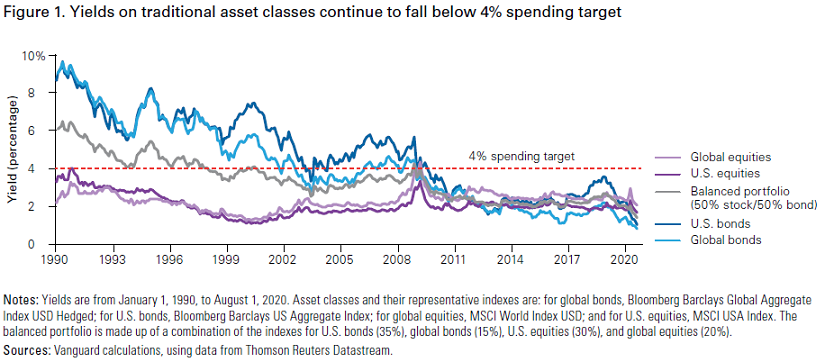
Unless investors are willing or able to make radical cuts in spending, there are two broad options to address the shortcoming of portfolio yields in meeting spending goals:

  • Alter the portfolio asset allocation in search of higher yielding and potentially riskier assets, or
  • Spend from capital in addition to the portfolio income yield.

For retirees or those approaching retirement, it could be tempting to increase your portfolio’s allocation to equities in the hopes of making up for the shortfall caused by capital losses. But this could mean taking added risk at the most conservative phase of your investment journey and is likely not in your longer-term best interest. If you take on more risk than you can tolerate, then losing your nerve and selling out of your strategy at the worst possible time can be damaging both emotionally and also to your hip pocket.

Higher rates should eventually lead to better fixed income returns

Vanguard expects that rising interest rates will likely reduce rising inflation and create a higher real interest rate environment that could potentially provide a boost for fixed income returns. The transition to higher rates is likely to curtail the most speculative parts of the financial markets at the edges but is unlikely to upend bond markets.

There are a few ways that you can rebalance your portfolio, but ultimately, you must decide how far you are willing to let your portfolio drift from its target asset allocation while also considering how much you are willing to pay in rebalancing costs.

The other element to consider is how you construct your portfolio. Some portfolios are designed with an income-oriented strategy in mind, with the goal of spending from interest and dividends while preserving capital. But Vanguard research has found that adopting a total return approach provides a better alternative to most investors.

The total return approach

So what is a total return approach? Instead of targeting a desired level of income, it begins with your goals and risk tolerance and then matches the asset allocation to your risk-return profile. It takes into account all sources of return from your portfolio, both income and capital (hence the term 'total return'), while controlling risks by using diversification, minimising costs and remaining disciplined over time. Then you set a prudent spending rule that sustainably supports your spending needs.
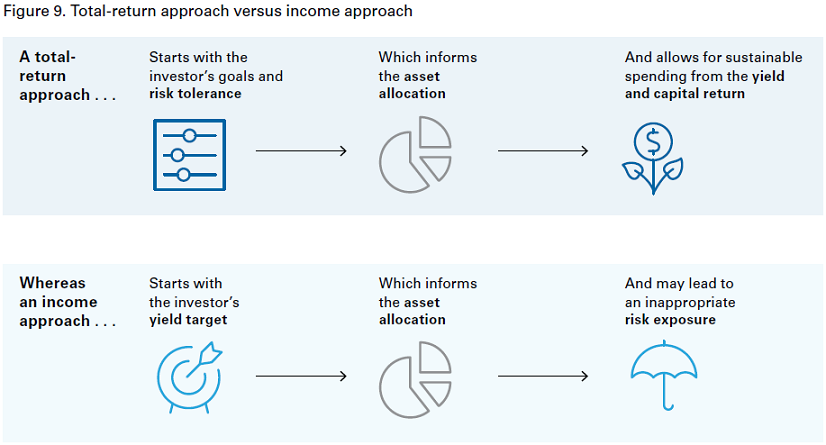
Source: Vanguard

As yields on traditional bond and balanced portfolios have fallen over the past 20 years, some investors opted to chase additional yield by overweighting higher income producing assets, taking on more equity or credit risk and introducing unintended factor or sector tilts. 

The total return approach ensures that portfolio risk is aligned to the investor’s risk tolerance, it also allows investors to control the size and timing of withdrawals, using the capital returns when necessary.

With a total return approach, the capital gains of the portfolio are spent to make up shortfalls in periods where the income yield of the portfolio is less than your spending needs or goals. This approach helps smooth out spending over time, as long as the total return drawn from the portfolio doesn’t exceed the sustainable spending rate over the long term.

It also requires you to be disciplined to reinvest a portion of income yield during times when the income generated by the portfolio is higher than the sustainable spending rate. Since capital returns can be volatile, taking a long-term view is paramount.

The ongoing volatility and market turbulence can be worrying over the short term, but history has proven that those who build their portfolios in line with their goals and risk tolerance and who remain disciplined by rebalancing their portfolios back to their target asset allocation are rewarded over time.


Inna Zorina is a Senior Investment Strategist at Vanguard Australia, a sponsor of Firstlinks. This article is for general information and does not consider the circumstances of any individual.

For articles and papers from Vanguard, please click here.


  •   23 February 2022
  • 2
  •      
  •   
2 Comments
Dave
February 23, 2022

Peter Thornhill where are you? Interesting comparison between advice given.

Kevin
February 25, 2022

Different ways of expressing things,and it depends on what you want to see.Vanguard is a fund.I know very little about funds,by all accounts Vanguard is one of the better ones.
Total return,the long explaination is strange.My goal was to retire with at least the same income as when I was working.I achieved that and more.I targeted that level of income,very simple .Super income is a bonus on top of that.
Total return.Still baffles me.Retire 2007 with 10,000 shares in CBA at the top of the market,I'm worth $620K.Without looking at dividends from then say $2 a share.I retired with grossed up income of $30K.

Same thing occurs,capital grows rather than depletes,the shares are now worth $ 950K.The grossed up income is $50K.

Investing is as easy or as complicated as you want it to be.The end result is the same whether it is called total return,or Kermit the frog.Compounding is the same for everybody.

Today if you have $1 million in any fund that Peter likes,or a Vanguard fund, or CBA shares it is still the same.Risk is what you see.I think CBA is risk free.In 10 years time they will all still be there,you will be depleting capital from your super fund,and hopefully the dividends grow from the funds and CBA .If they all grow at the same rate you may have $1.5 million,and a 5% yield.The yield from the funds may be higher or lower than CBA,each year you will know .
Inna is exactly right,for most investors.Peter is exactly right for compounding.
The simple approach is 1991,spend $10K on 1500 CBA shares.
Put $10K into whatever LIC or anything that Peter likes.
Put $10K into a Vanguard fund with Inna.
As Inna said the discipline to reinvest dividends.I'll add not the sloppiness of a hypothetical,or a what if,or a what about,or a yeah but something else,or but if you look over there.Somebody else said,other people would.....,on and on and on.
Going right out on a limb,put $10K into each of them.Spend $30K in one hit,around average wages in 1991.Today you will be very happy,whatever they are worth,and perhaps $250K in super on run of the mill averages.
Tomorrow is exactly the same $90K into a couple or 1 share that you like Or $30K into each of them Around average income.Spent in one hit and the loan paid back over the coming 31 years.

The end result is exactly the same,whatever they are worth,plus your super.Easy.

Or,yeah but will it reduce my pension,will I be paying tax ,I don't like the idea of paying tax,on and on and on


Leave a Comment:

RELATED ARTICLES

The new capital gains tax trap for your portfolio

Why investors should consider adding private equity to portfolios

Solving the Australian equities conundrum

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.