Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 100

Where to put your money these days

[Editor’s note: The author is not a licensed financial advisor, and opinions are given as a personal conviction and as a futurist, not advice to investors.]

It is getting very tricky for Australian investors with over $3.7 trillion in super and other financial assets to know which asset classes are the best in terms of short or long term yield and capital appreciation. Or safest, regardless of yield.

The choices at the asset class level are:

  • liquids (cash, short term, long bonds)
  • shares (local or foreign).
  • property (owner-occupied and investment dwellings, commercial)
  • commodities and collectables (gold, other metals, collectables)

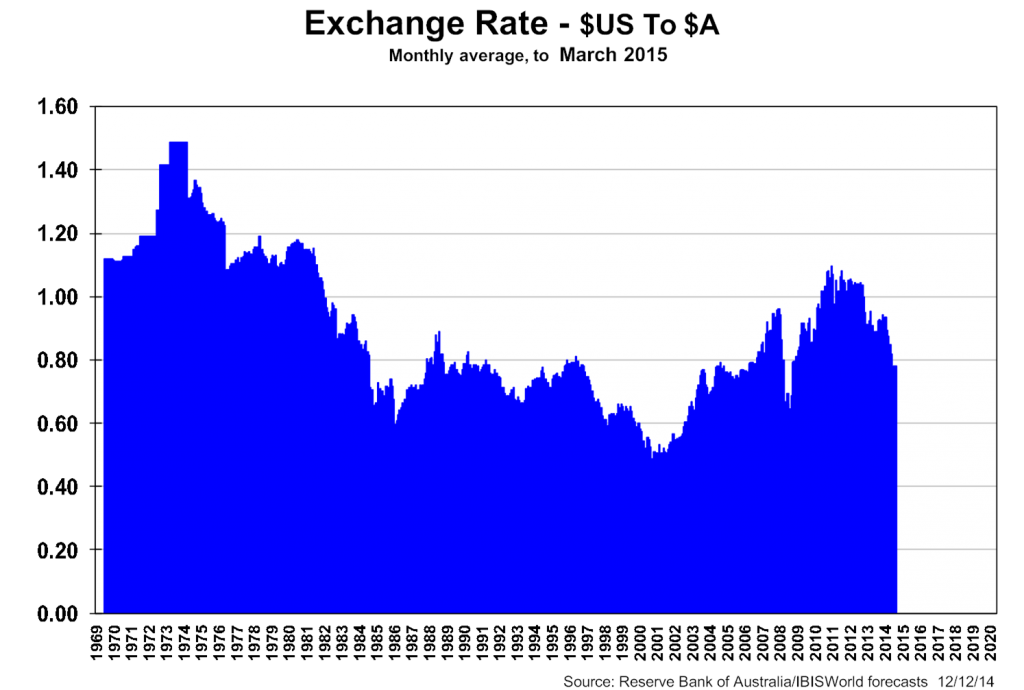
The offshore options on any of the above classes of investment introduce the exchange rate variable, further clouding the choices. As the chart below reminds us, the exchange rate is a very difficult variable to predict with any accuracy. And buying offshore assets is not as easy with a US76¢ exchange rate versus the US$1.10 of mid-2011.
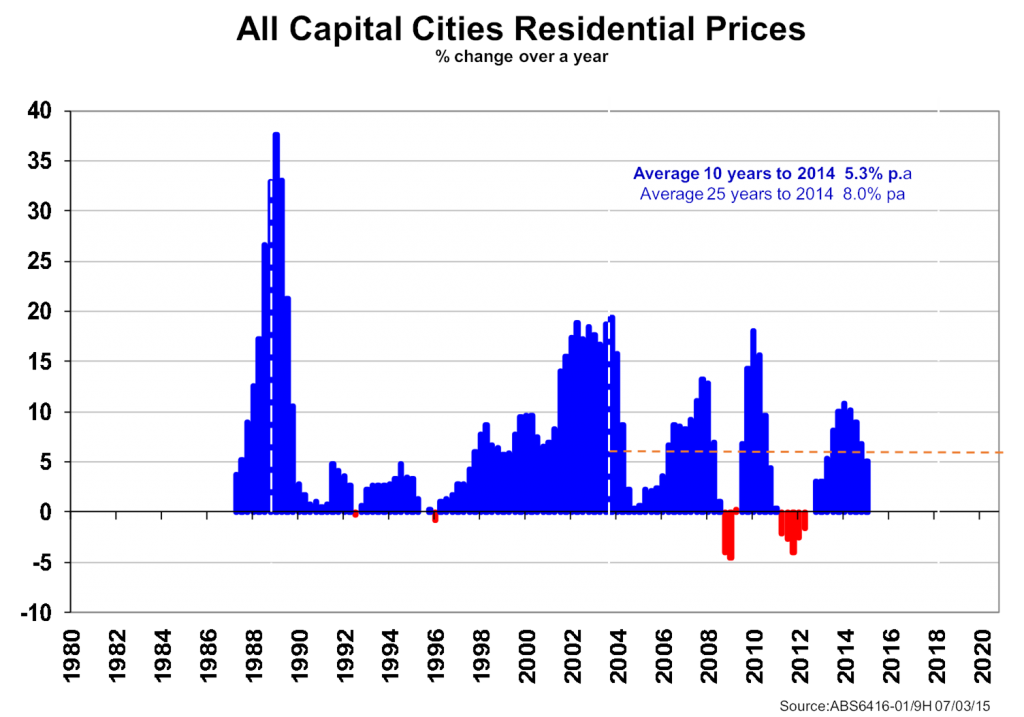
Residential property values also move around, but over the medium to longer term provided capital growth of a fairly safe 5¼% pa. However prices can go negative, as seen in the second exhibit. Australia already has some of the world’s most over-valued residential prices (over 3½ times average household income), kept high by record low mortgage rates at under 5% compared with the very long term average of nearer 7½%. So considerable care is needed as we head into the third decade of this 21st Century when it comes to looking for a lot of capital gain as distinct from low net rental returns in investment residential property.
Is gold ready for another of its spectacular leaps? As we know, gold is no longer used for currency backing, the gold standard having gone almost half a century ago when President Nixon abandoned it. These days it serves two purposes: use in jewellery and industry; and as a panic metal during financial crises.
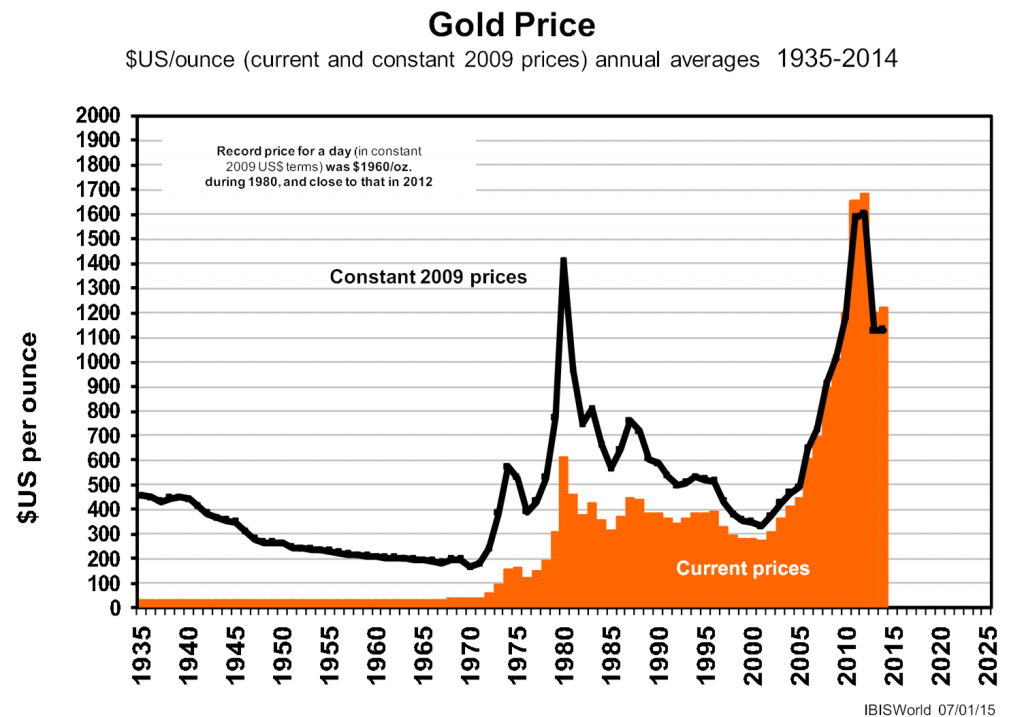
It doesn’t look like the price is going to spike again in the short term, but maybe in the much longer term.

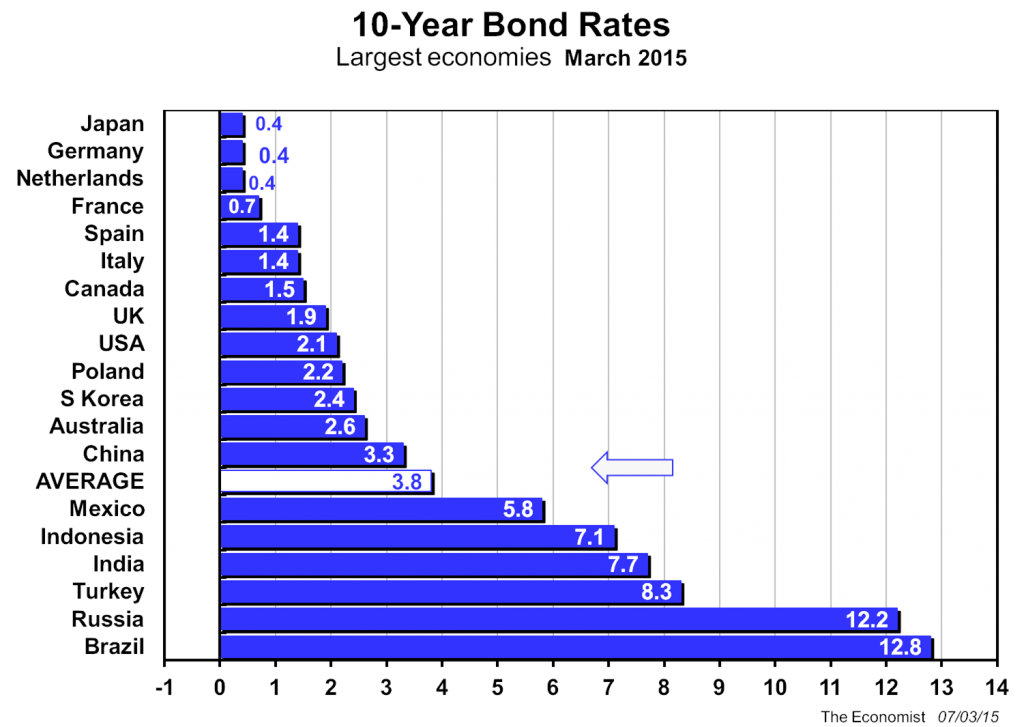
Are government bonds better? Hardly, when one looks at the fourth exhibit and its record low yield in March 2015 of 2.6%.
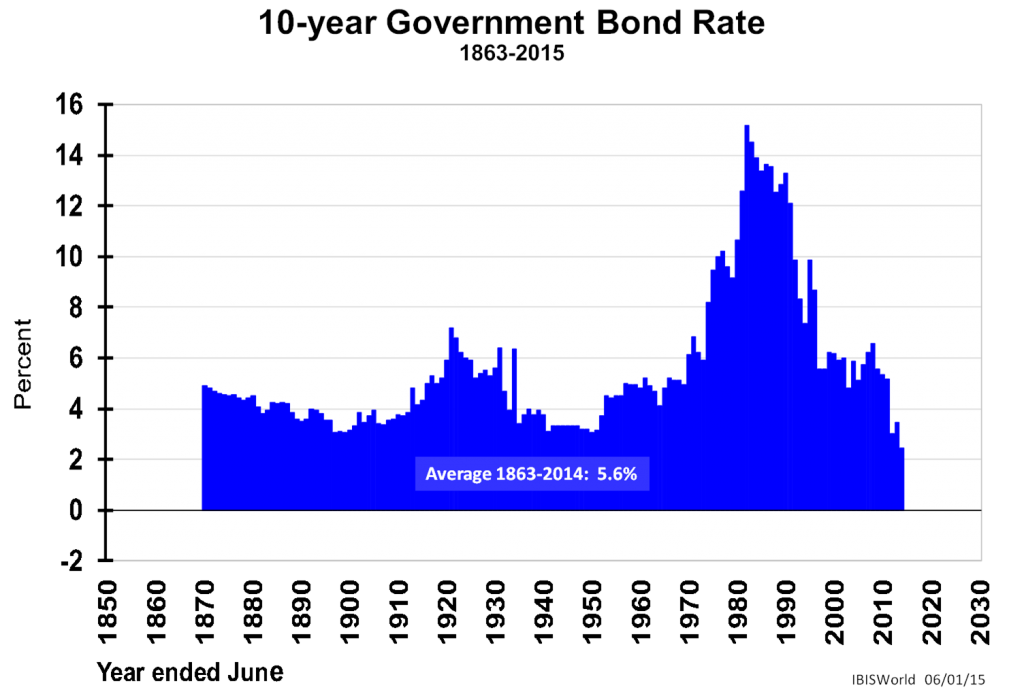
If we think that level of yield is unacceptably low to an investor, we could spare some compassion for investors in other large economies as seen in the fifth exhibit below.
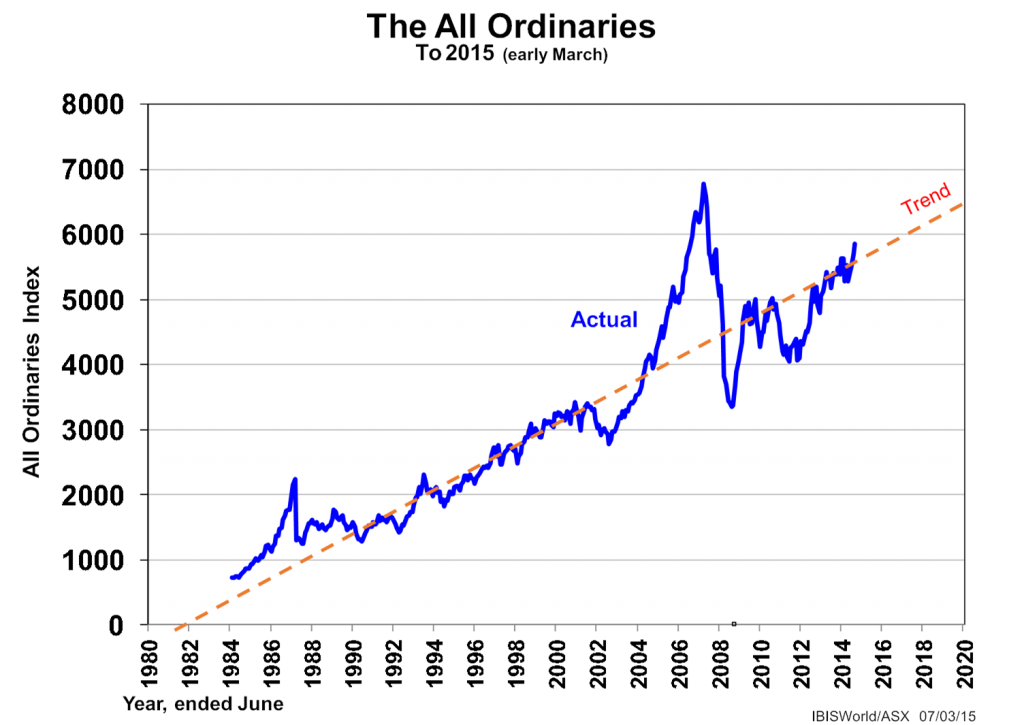
Which leads to shares. They are rising lately as much by default (unattractive yields in other classes of investment) as due to other fundamentals (rising profitability and dividends) as we see below in the sixth exhibit. So far into 2015, the All Ordinaries Index does not appear to be wildly over-trend.
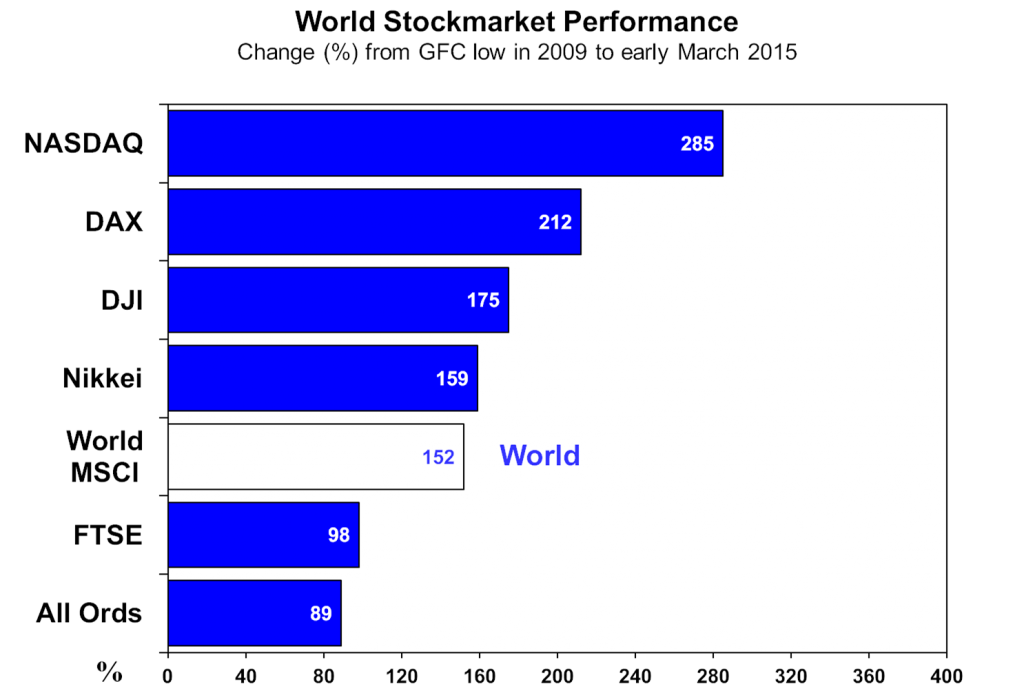
The final exhibit suggests that we can over-react to steep falls such as occasioned by the GFC. The recovery across the world’s major indices ranges from the mind-boggling (NASDAQ and DAX) to sort of reasonable (All Ordinaries).
So what does all this mean going forward from 2015?

Basically, that returns are not as good as they have been over recent decades, whether they be liquids, property, commodities or shares, where rising P/E ratios are lowering yields in response to record low interest rates. Then again we aren’t experiencing another GFC either which would be a much greater worry. Inflation is very low in most developed economies, and some are experiencing deflation, not seen since the Great Depression. This points to slightly better real returns than the nominal rates might suggest.

It is also very encouraging to see the USA and UK climbing out of their six-year long GFC, although we could be less sanguine by the almost motionless Japanese economy and the slowing Chinese economy – both big export destinations for Australia, accounting for well over half our trade.

Some forecasters are predicting apocalyptic troubles arising from world debt levels, but not this author, as yet. Government indebtedness is not yet back to the immediate post WWII levels (with some exceptions such as Greece and Japan). Yes, household debt is huge in many countries, especially Australia, but still manageable in terms of debt servicing costs as our RBA reminds us from time to time, while warning us of stupid dwelling prices and the long term dangers involved.

And business debt in terms of debt/equity ratios are generally prudent.

If all this tells us anything, it is don’t retire too early! Supplement any low investment returns with working income, be it on a part-time or casual basis if you can. We will probably live longer anyway by doing that.


Phil Ruthven is Chairman, IBISWorld and Australia’s leading futurist. Repeating, he is not a licensed financial advisor, and opinions are given as personal conviction and as a futurist, not advice to investors. The article is written for general information and investors should seek their own professional advice.


  •   12 March 2015
  • 2
  •      
  •   

RELATED ARTICLES

Chris Joye on why stocks and property are set for a poor year

How much will you risk to feel comfortable?

Do investors accept lower returns from assets that make them feel good?

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.