Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 296

Would a recession in 2019 matter to financial markets?

With the S&P 500 Index delivering its worst December performance since 1931 and credit spreads widening back to their long-term averages, fears of a recession in 2019 have increased.

But are those fears justified?

Some market-based metrics have been quietly signaling an increase in the risk of recession, with one of the more popular being the flattening US yield curve. While not perfect — and market watchers need to be cautious about false positive signals, such as in the late 1960s (see illustration below) — the predictive powers of the yield curve historically have been quite high. So how should investors think about this?

I think about it in two ways.
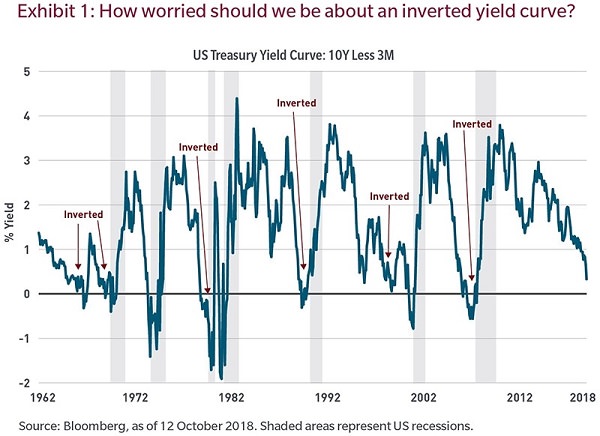
1. Would a recession matter to financial markets?

Market falls and recessions have coincided more often than not, as we observed in 1982, 2001 and 2008. So the answer is yes. However, that has not always been the case.

Economic health — or the lack thereof — and investor sentiment are two different things. While the economy is made up of many varying elements, financial markets reflect investors’ expectations regarding profits and cash flows. While each can heavily influence or lead the other, we have observed periods in which capital market declines and recessions have been mutually exclusive, like in 1990 (a recessionary non-bear market) or in 1987 (a non-recessionary bear market).

2. This economic cycle has been different from others in many ways.

As MFS chief economist Erik Weisman recently said to me, “In terms of the traditional drivers of recession, most aren’t evident today. We haven’t just ended a war; there is no negative supply shock (as with oil in 1973 and 1979); and the US Federal Reserve isn’t aggressively trying to contain overly high inflation (like the Volker Fed in the early 1980s). Outside of corporate leverage, macro excesses in the US economy are hard to identify.”

Something else that makes this cycle different has been the rise of internet platforms. They have provided a new way for enterprise and consumers to optimize business operations and everyday life. They have fostered “de-materialization.” In other words, the world is doing more with less capital, and that has been disinflationary.

For example, cloud computing allows enterprises to better engage with customers in a more cost-effective and productive manner. Internet infrastructure technology has allowed enterprises to better manage inventories and deploy capital more efficiently. Similarly, consumers have de-materialized. Internet platforms have allowed people to rent what they once owned, avoiding large, upfront costs in categories such as shelter and transportation.

Not only in the United States, but also in Germany and the United Kingdom, consumers allocate more than half of their discretionary spending to experiences or intangibles rather than physical goods. We are seeing similar trends in emerging markets such as India and Colombia.

The result has been a decline in the volatility of real demand, which partially explains why this business cycle has been low in growth, long in duration and with fewer excesses compared with history.

In conclusion, we are generally not concerned about a recession in 2019. To me, the Treasury market, which has rallied in recent months, is signaling greater concern about a potential Fed policy error than about an overheating economy. However, we have grown concerned about market complacency surrounding margin sustainability and financial leverage. So while we are less concerned with recession risks, we believe investors should be more thoughtful about how portfolio risk is allocated today as compared to how it was in the past decade.


Robert M. Almeida is a Global Investment Strategist at MFS Investment Management. The comments, opinions and analysis are for general information purposes only and are not investment advice or a complete analysis of every material fact regarding any investment. Comments, opinions and analysis are rendered as of the date given and may change without notice due to market conditions and other factors. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343), a sponsor of Cuffelinks.

For more articles and papers from MFS, please click here.


  •   7 March 2019
  • 1
  •      
  •   

RELATED ARTICLES

Investors need to allow for future cycles

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.