Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 532

Is ResMed a trap or an opportunity?

During the [third] quarter, we added ResMed (RMD.ASX) to our top ten holdings. ResMed is the global leader in sleep and respiratory care primarily focused on the development and sale of positive airway pressure devices and accessories for the treatment of obstructive sleep apnoea. ResMed’s share price has fallen 30% since the release of its FY23 results in August largely in response to concerns GLP-1 (Glucagon-Like Peptide-1) drugs may reduce its addressable market. In this article, we discuss the business in more detail and why we think the GLP-1 concerns are overdone.

What is Obstructive Sleep Apnoea (OSA)?

Obstructive sleep apnoea is a chronic illness that occurs when the muscles that support tissues in the back of the throat relax during sleep, blocking or narrowing the upper airway. This obstruction leads to impaired breathing for a short period (usually 10-20 seconds), which results in lower oxygen in the blood. The brain senses the impaired breathing, causing the individual to subconsciously rouse from sleep in order to reopen the airway. The severity of OSA is characterised by the number of events per hour: Normal < 5; Moderate 15-30; Severe > 30.

Continuous Positive Airway Pressure (CPAP) devices are the accepted standard of care for treating OSA, delivering a stream of pressurised air through a mask to prevent the collapse of the upper airway during sleep. ResMed is the largest manufacturer of these products, and we estimate the company currently has ~80% market share with its major competitor Philips out of the market for the past two years due to an FDA-imposed product recall.

Large, undiagnosed addressable market

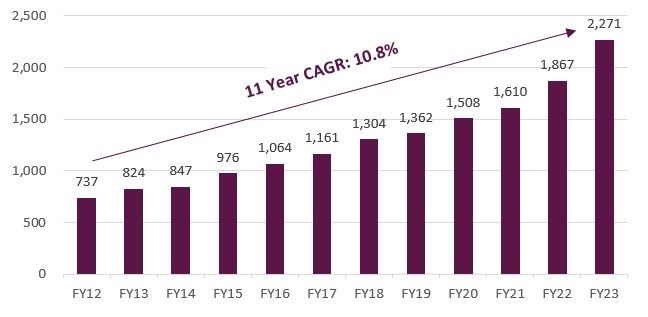
The OSA market is large and mostly undiagnosed. According to the company, there are 936 million people globally with sleep apnoea and 424 million of these suffer from severe sleep apnoea. The size of the addressable market is evidenced by the fact ResMed had grown its device revenue at over 9% p.a. in the six years prior to the Philips recall (FY13-FY19). Recent growth rates have been even higher. ResMed estimates that penetration currently sits at 20% in the US and well below this percentage globally, which implies a long runway for future device and mask sales.

Figure 1 – ResMed device revenue (US$)
Source: Company filings

One of the highest-quality companies on the ASX

As with any new position, we tested ResMed against our key investment criteria and consider the business to be high quality based on the following factors:

  • Financial strength: ResMed has a strong balance sheet with less than 1x ND/EBITDA
  • Business quality: ResMed has a dominant market position (~80% share), sells defensive products that improve patient quality of life and are reimbursed by Medicare/health insurers in the US, and earns high returns on capital (22% average over last 5 years).
  • Management quality: We consider ResMed a “founder-led” business. Founder Peter Farrell is Chair Emeritus, and his son, CEO and Chair Mick Farrell, has presided over an exceptional track record in product development and market share gains in his 10+ years as CEO.

GLP-1 concerns and valuation

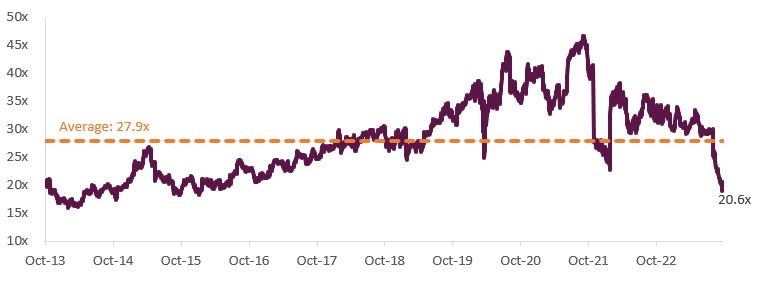
ResMed has historically traded on a forward multiple of 28x PE but is currently trading on less than 21x PE due to market concerns about GLP-1 drugs reducing ResMed’s addressable market.

Figure 2 – ResMed NTM Rolling PE
Source: FactSet

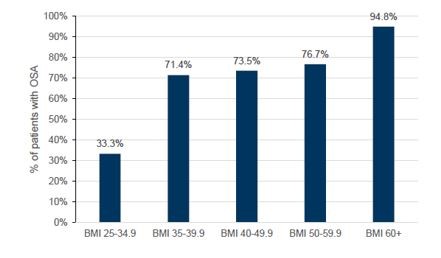
GLP-1 drugs (branded as Ozempic, Wegovy and Mounjaro) act by mimicking hormones that are released into the gastrointestinal tract in response to eating. These drugs were initially developed to target type 2 diabetes by stimulating more insulin production but have evolved to potential applications in weight management and cardiovascular indications. Given obesity is a key risk factor for OSA (see Figures 3 and 4), there is a view that significant weight reduction from taking GLP-1s may result in reduced demand for CPAP therapy.

Figure 3 – OSA severity by AHI (>5 mild) and (>15 moderate)
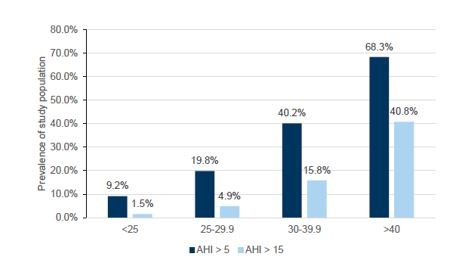
Figure 4 – Prevalence of sleep apnoea in morbidly obese patients who presented for weight loss surgery evaluation
Source: Goldman Sachs Research

While we are not medical experts, we consider the significant de-rating to be an overreaction for the following reasons:

  • GLP-1 drugs have been around for almost a decade in managing blood sugar, and other competing therapies such as oral devices and bariatric surgery have not been able to displace CPAP as the standard of care. We note CPAP also has the advantage of being able to track patient adherence and compliance through cloud-connected devices. We believe this data is valuable to third-party payors.
  • While we acknowledge weight gain is a leading risk factor in developing OSA, it is not the only cause. Based on our conversations with sleep physicians and the company we estimate one-third of OSA patients are not obese. While the remaining two-thirds of the patient pool is highly likely to test GLP-1 drugs (as they become more accessible and affordable) we don’t expect adherence to be 100% given the potential for side effects such as nausea and the impact on lifestyle. We also don’t expect GLP-1s to fully eliminate OSA in all cases (the drugs may simply reduce severity). As a result, we think it’s more likely you could have a scenario where a combination of GLP-1 drugs and CPAP therapy are prescribed as treatment.
  • Finally, these drugs with an average retail price of ~US$1,000/month are currently unaffordable for most patients. Pricing will need to come down significantly to attract broader reimbursement and mass adoption.

Overall, we think the uncertainty as to the potential penetration and success of these drugs in treating OSA has created a rare opportunity to invest in one of the highest quality companies on the ASX. While we are unlikely to pick the bottom, we believe the company is trading well below its intrinsic value.


Vinay Ranjan is a Senior Equities Analyst at Magellan-owned, Airlie Funds Management. Magellan Asset Management is a sponsor of Firstlinks. This article has been prepared for general information purposes only and must not be construed as investment advice or as an investment recommendation. This material does not consider your investment objectives, financial situation or particular needs.

For more articles and papers from Magellan, please click here.


  •   25 October 2023
  • 5
  •      
  •   
5 Comments
Jonathan R
October 26, 2023

The issue not mentioned with ResMed is that despite the share price fall, it's still far from cheap. At 23x PER for a company that's grown EPS at 11% pa over the past decade, it's a full price. Which goes to show how silly the price at the peak was.

CSL is in a similar boat - it's current PER at 33x for a company that's grown EPS by 6% pa over 10 years.

Price matters.

David
October 30, 2023

anything half descent with a business model that spits out cash trades on an enormous PE eg TNE - 13% growth over 8 years, PE = 51x; REA 8% PE =45x. People know quality and they are prepared to pay up for it. But look at the average PE over a number of years and stocks like RMD and CSL are pretty cheap.

David Smith
December 05, 2023

Hi David,
I agree with you completely. I have also held TNE and REA shares for many years as you say quality shares like this are worth having.
With regard to CSL and RMD they are now my biggest holding (aprox 20% each) because I see this as a oportunity to to buy very high quality shares at bargin price. I intend to be holding these shares for at least 5 years and I expect their price to rise steadly.

Michael Sandy
October 30, 2023

there is no doubt that Ozempic (GLP-1 drug) has side effects such as loss of muscle as well as fat, and because it delays gastric emptying it can make indigestion/gastric reflux worse.
Overall I'm finding it surprisingly effective in helping people lose weight.

Dudley
October 30, 2023

For those for whom Ozempic is not prescribable and who are motivated, assisted sleep, such as with minimal zopiclone (eg 2 x 1 mg), extends the natural sleeping ketone 'cycle'. Extended walks assist both sleep and ketone cycle. Both reduce blood sugar and inflammation.


Leave a Comment:

RELATED ARTICLES

Market narratives are seductive and dangerous

Why stock prices are a distraction

Why investors are looking beyond traditional property sectors

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.