Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 274

Is 'shaken and stirred' coming? The risky business of bonds

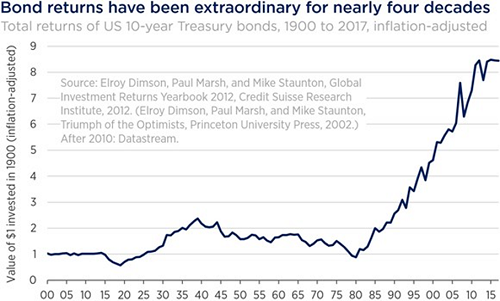
Bonds have been an exceptionally rewarding asset class for nearly four decades. They have also proven to be a reliable diversification tool, particularly when deployed with stocks in a so-called '60/40' portfolio. But expecting a repeat performance in the decades to come reminds us of the late financial historian Peter L. Bernstein’s comment that: “There is a difference between an optimist and a believer in the tooth fairy.”

As can be seen in the chart below, this extraordinary period of performance has been unusual in the context of longer-term history. Bonds have benefitted from a favourable tailwind that stretches back to the early 1980s. Recently, the tailwind has been reinforced by the unprecedented actions of central banks following the GFC. To avoid a deflationary debt spiral, the Federal Reserve and other major central banks intentionally drove bond yields to historic lows and even into negative territory in some instances, sending bond prices to new highs.
government bonds

government bonds

Prospective returns for many bonds now appear limited

In addition to nosebleed prices and rock-bottom yields, the risks embedded in the bond market would appear to be well above average when we observe cuts in taxes and a ramp up in fiscal spending at a time when government debt is already at or near all-time highs. Governments and central banks are desperate to inflate away these debt burdens. Sustained negative real yields imply sustained negative real returns to holders of these nominal assets.

We also ask ourselves: “Who is the marginal buyer of bonds at these yields if central banks are stepping back?” Historically it might have been large governments recycling their enormous current account surpluses. If a country exports more than it imports, it needs to do something with the difference, and exporter countries have often been major buyers of importers’ bonds. But the reduction of international trade imbalances is now top of the political agenda.

In addition to political will, there are forces at work that should lead to a more natural reduction of the global gross trade surplus. Examples include the seismic shifts in China, where supply-side reforms have the potential to substantially boost imports, and in the US, where the shale oil and gas revolution is beginning to impact the export picture.

The bond sell-off that spooked investors in February this year was driven by greater-than-expected wage growth in the US. It could be a sign of more volatility to come. Negative returns are likely if interest rates continue to rise as quantitative easing begins to unwind. When yields are low, bond prices become extra sensitive to any change in yield, adding a layer of risk.

Rise in correlation reduces diversification benefits

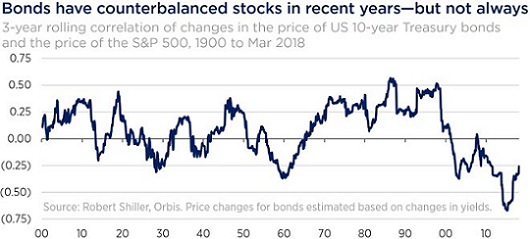
Worse, there are signs that stocks and bonds are now moving together, negating the diversification benefit bonds are expected to provide. Taking a longer-term view of history, the following chart shows that the strong anti-correlation between US stocks and bonds (the negative numbers) since the late 1990s is quite unusual.  History suggests that investors should expect bonds and stocks to be more correlated in the future with the possibility of high correlations in a rising interest rate environment. It also suggests that investors might question the traditional diversification role played by long-dated government bonds in a balanced portfolio.
government bonds

Yields for long-term government bonds can be broken into a few components: inflation expectations, the expected path of real interest rates and the term premium. This latter component can be thought of as the compensation offered to investors for taking on a long-dated risk. It should always be positive, but today, term premiums in most developed markets are near zero, and some, astonishingly, are negative. A negative term premium implies that investors are paying for the privilege of taking on term risk. This is highly unusual, if not nonsensical. Yields can be low for good reasons, but it’s hard to imagine a good reason for the term premium to be negative. This looks like a real inefficiency — a mispricing.

One culprit is quantitative easing (QE), the process where central banks buy bonds and other assets using newly-printed money. Large price-insensitive buyers of government bonds are bound to create price distortions. In this environment it makes sense for governments and companies to borrow long term, and this is what we have seen. Ireland and Austria have issued bonds that mature in 100 years.

Today's prices force a rethink

One definition of risk is that “more things can happen than will happen”, and purchasers of these bonds have 100 years’ worth of potential surprises to look forward to. For taking on this enormously long-dated risk, investors receive a paltry 2% per annum. Relying solely on long-term government bonds to manage risk at today’s prices strikes us as imprudent at best.


Graeme Forster is Portfolio Manager at Orbis Investments, a sponsor of Cuffelinks. Commentary is adapted from Orbis quarterly reports and reflects recent views. The information provided in this article in general in nature and does not take into account your personal objectives, financial situation or needs.

For more articles and papers from Orbis, please click here.

  •   4 October 2018
  • 1
  •      
  •   

RELATED ARTICLES

Busting the bond myth

A journey through the life of a fixed rate bond

Why have bond fund distributions been shrinking?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.