Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 110

SMSF trustees have longer lives and more certainty

One of the greatest risks facing retirees today is the uncertainty over how long they might live. How do you plan your retirement when you don’t know how long you need your savings to last? Whilst an individual’s lifespan can never be known with complete certainty, the more information retirees have on how long they are likely to live, the easier it will be to make sustainable retirement plans.

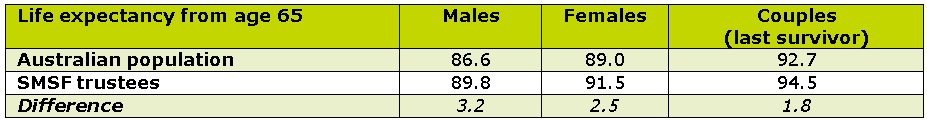
The most commonly quoted life expectancy figures are from the Australian Life Tables and are based on the whole population. If we allow for recent trends in improving mortality to continue, these tables show that 65 year-old Australian men have a life expectancy of 87 and women, a life expectancy of 89. However, different cohorts of the population will live longer than others.

Wealth and education lead to longer lives

Research from around the world has shown that wealth and higher levels of education are strongly correlated with longer life expectancy. SMSF trustees are, on average, both wealthier and better educated than the average Australian so they are one such cohort that might be expected to live longer than the average.

In the first research of its kind in Australia, Accurium’s SMSF Retirement Insights paper, SMSF Trustees - healthier, wealthier and living longer, carried out a mortality investigation on the 65,000 SMSFs in its database to test this hypothesis and calculate how much longer SMSF trustees might live. The results showed that SMSF trustees can expect to live around three years longer in retirement than average.

The table below shows the life expectancies of SMSF trustees in retirement compared to the population as a whole:
Half will live even longer

While life expectancies are helpful for retirement planning, few people will live to their exact life expectancy. Even amongst SMSF trustees, only one in six will live to within a year either side of the life expectancies shown above. Life expectancy is just an average. In fact over half of SMSF trustees will live beyond this.

Many retirees want greater certainty that their savings will last for life so it can be useful to look at the probabilities of living to older ages. Accurium’s research predicts the proportion of trustees who will survive to each age in retirement. These figures can be used as confidence levels for retirees when setting their retirement planning horizons. The table below shows the age trustees retiring at age 65 should plan for with differing levels of confidence:
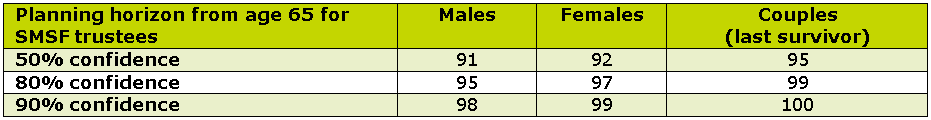
For example, one in five 65 year-old women with an SMSF is expected to live to age 97, therefore those wanting 80% confidence in their retirement plans should be planning for their savings to last around 32 years. A couple wanting 90% certainty should be planning for living for a further 35 years to age 100.

The price of long lifespans is a high cost of retirement and requires trade-offs between how much an SMSF couple spend each year in retirement and how much risk they are willing to accept around outliving their capital.

‘Typical’ couples may need $1.3 million to $2.5 million

Accurium estimates that a 65 year-old couple wanting to spend $70,000 each year and willing to accept an 80% probability of a successful outcome would need $1.3 million as an SMSF starting balance; those wanting to spend $100,000 a year would need a starting balance at 65 of $2.1 million. To achieve 95% certainty that they won’t outlive their capital, that same couple would need $2.5 million if they wished to spend $100,000 per year.

Exactly how long an individual is expected to live has been found to be affected by a number of different factors as well as age and gender. Factors that are known to influence individual life expectancy include smoking, genetics (e.g. family history of certain diseases), current health problems (such as diabetes), occupation and geographic location. SMSF trustees retiring in good health are likely to fall into the higher percentiles for life expectancy and should be planning accordingly.

An important conclusion is that, while fewer SMSF trustees will pass away in the early years of their retirement compared with the population as a whole, a greater proportion will live to their mid-nineties. SMSF trustees can have greater certainty over how long they will live.

Longevity risk for a retiree isn’t the risk that they will live a long time; it is the risk that they will live longer than they have planned for. As long as trustees set their retirement plans using appropriate time horizons, this research shows that SMSF trustees really can have their cake and eat it. Not only will they live longer than the average Australian, but they actually have less longevity risk too.


Doug McBirnie is a Consulting Actuary at Accurium. This information is factual and is not intended to be financial product advice or legal advice and should not be relied upon as such. You should seek appropriate professional advice before making any financial decisions.


  •   22 May 2015
  • 2
  •      
  •   
2 Comments
SMSF Trustee
May 24, 2015

I'm so relieved to realise that my decision to start an SMSF and become a trustee a couple of years ago has added to my life expectancy.

I think, actually, that this study suffers from one of the fallacies I learnt about in high school commerce: arguing that because B follows A, then B must have been caused by A. It's just as likely that both A and B were caused by X, Y and Z.

Perhaps it's got nothing to do with being an SMSF trustee and is really just saying that wealthy, well educated people live longer than poor people with less education. The fact that this cohort also happens to tend to start SMSF's rather than just relying on an off the shelf product is most likely to be coincidental with their extra life expectancy.

But I'm open to being shown otherwise. If I'm wrong, then every GP in the country should immediately prescribe 'open an SMSF' to all their patients.

Alun Stevens
May 25, 2015

I don't believe that the paper suffers from the fallacy of misinterpreting correlation for causality. It is simply comparing outcomes for SMSF trustees with those of the general public.

The causality is undoubtedly the beneficial outcomes from the socio-economic standing of the average SMSF trustee when compared to the total population. The results are entirely consistent with many studies over many years that have considered the mortality experience of different socio-economic cohorts. Even with those studies, however, it is worth remembering that it is not the money that causes the better outcomes - although it helps.

The GPs, however, might have been misled by the statistical inference. They pretty much all have SMSFs.


Leave a Comment:

RELATED ARTICLES

Will you run out of money in retirement?

Longevity awareness and the three pillars

The retirement account that Australia should have

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.