Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 159

Surprising negative gearing and capital gains survey results

Another strong response to our survey, with some surprising results.

Before we go too far analysing the numbers, we should acknowledge that opt-in polls are not as independent as using a statistical method to pick respondents. It’s important how people are chosen, and where the respondents choose themselves, pollsters argue the sample does not reflect the general sentiment.

With this qualification, it was surprising that 60% of respondents believe negative gearing should not be retained in its current form, given that most readers are investors and market professionals.
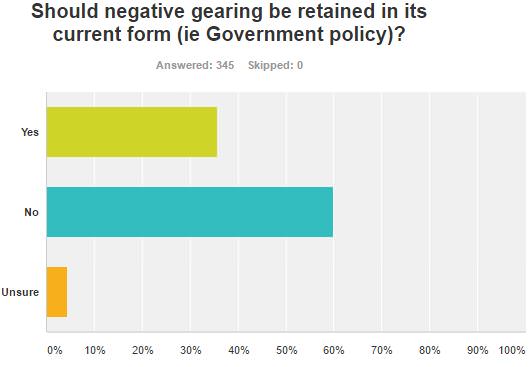
The comments reveal the rationale for this result, with responses dominated by two groups:

  • those against negative gearing argue property investment has become speculative and is contributing to making housing unaffordable for first-home buyers. There are equity and intergenerational issues and it is a subsidy from the taxpayer.
  • Those in favour of negative gearing argue it is a basic principle of investing and business that an expense is a tax deduction, and negative gearing is used by medium-income earners to build security, not only the wealthy.

There was a lot of support for capping the loss in some way, either by the number of properties or the type of income the loss can be claimed against.

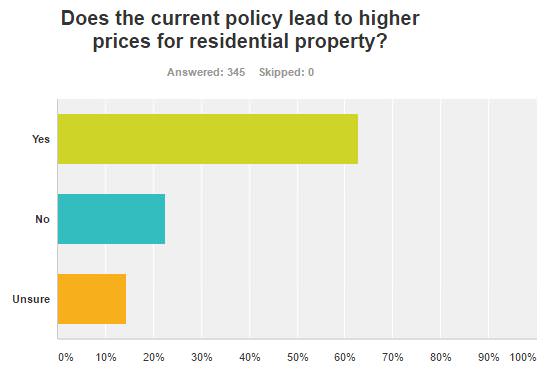
Respondents strongly believe that the current policy leads to higher house prices, with only 22% saying it does not. Main reason is that the tax benefits encourage demand for investment property.
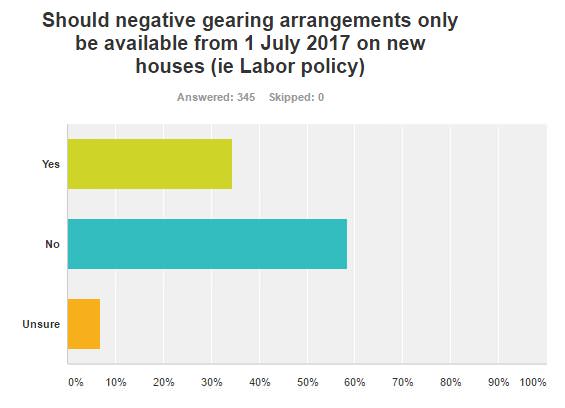
On the proposed Labor Party policy of restricting negative gearing to new properties from 1 July 2017 (and retaining existing arrangements), 59% disagreed, mainly because it would create distortions and lift the price of new homes.
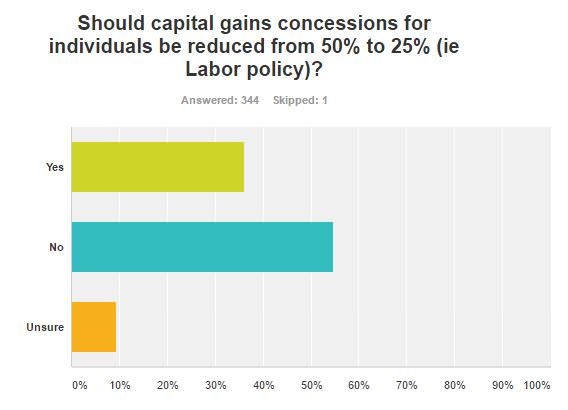
On Labor’s proposal to cut capital gains concessions, although a strong 55% were against, there was decent number arguing the current 50% is too high, with 36% in favour of the change.
The full survey results are linked here.

There are many good comments in the final section of the survey, too numerous to reproduce here.

A few observations on the policies:

  • Labor will retain negative gearing on new property, in a policy designed to encourage a supply of new housing, but there's a potential downside. Already, many new apartment developments are over-hyped in elaborate marketing campaigns, glossy brochures and photographs taken from the top floor. With obvious exceptions like Barangaroo, early resales are often disappointing when the building is actually finished. The negative gearing on new property and the easier access to these apartments for foreign investors may lead to an even more expensive primary market and a disappointing secondary market. Plus there will be a rush by investors to buy existing property before the 1 July 2017 deadline, exacerbating the affordability problem.

  • For the majority of Australians, owning their own home is an important part of life’s journey. The dream goes like this (warning: sweeping generalisation coming) – have a good education, find the right job, meet a partner, buy a home, start a family, pay off the mortgage, buy an investment property, move onto other investments …). Unlike other countries where it is acceptable for even senior executive to rent homes on 10- and 20-year leases, in Australia, home ownership is a right of passage. With average household income about $80,000 a year and median capital city house price about $723,000 (and over $1 million in Sydney), the nine-times house-to-income ratio is destroying dreams, or creating massive debt burdens, notwithstanding lower interest rates.

  • Many property investors over-extend themselves believing prices can only rise. There’s a naivety about piling into debt to buy property rarely seen in other asset classes. Investors are willing to accept property expenses exceeding income in the hope of future gains. The latest CoreLogic rental data for combined capital shows average gross rental yields of 3.3%, which would net to around 1% after costs (council rates, strata fees, repairs, etc). Subtract mortgage costs of at least 4% and there’s the negative gearing. Rental yields are at record lows. Fuelling the fire, the expected capital growth has certainly played out in the last five years, as shown below for total returns from residential property (including capital gains):
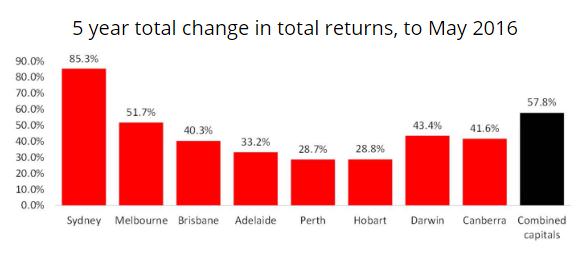

Source: CoreLogic RP Data Accumulation Index

Little wonder housing investment remains popular. There’s not enough space to outline what can go wrong in future with this plan, but suffice to say that the thousands of inexperienced property investors borrowing five to ten times their annual gross salary to buy an off-the-plan apartment in an over-supplied market will end in a lot of tears.

It’s a complex policy area of intergenerational equity, rich versus poor, renters versus landlords and massive personal debts and leverage. So far, the people who own the properties are mostly the big winners.


Graham Hand is Editor of Cuffelinks.


  •   7 June 2016
  • 3
  •      
  •   
3 Comments
Gary
June 09, 2016

“Pay off a mortgage” used to part of everybody’s plan – but now the majority of 60-70 year olds I come across still have a mortgage. Many of them are increasing instead of reducing.

Ramani
June 09, 2016

The administrative difficulty of limiting negative gearing deductions (not just on residential property) given that during a long-term asset's holding duration, the net outcome would fluctuate between positive and negative cannot be ignored. Of course, tax rules can artificially limit negative outcomes while taxing the positive. This would offend equity, and with compounding, be magnified in its impact.

No one would invest expecting a life long negative outcome.

The regime's other quirks (capital gains only considered on realisation, except for professional traders; unused capital losses having to be carried forward; the capital gains discount) distort the results.

If it is agreed that tax policy, to be effective, should be seen to be fair (especially given our self-assessment regime), riding rough shod by asymmetrically ignoring negative years while taxing the positive ones would breed disaffection, and for the fortunate ultra-rich, a swift place in the Panama Papers.

Does nothing for public confidence or fiscal deficit. Hasten slowly here.

Alex
June 09, 2016

Introducing a restrictive policy a year from now will send the residential market into a frenzy next year. I can hear the real estate agents. "Get in now before negative gearing is abolished and capital gains tax is halved". Although the Government is encouraging higher prices with its retention of negative gearing, so is Labor by granting a one year buying window, making affordability even worse.


Leave a Comment:

RELATED ARTICLES

A capital gains tax discount is legitimate but how much?

Negative gearing and capital gains survey

Survey on potential superannuation changes in Budget 2016

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.