Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 531

Survey results: Your personal experiences with inflation

Thanks to the hundreds of readers who shared their experiences in Australia's current inflationary environment. Here is a summary of the results and extracts from your comments.

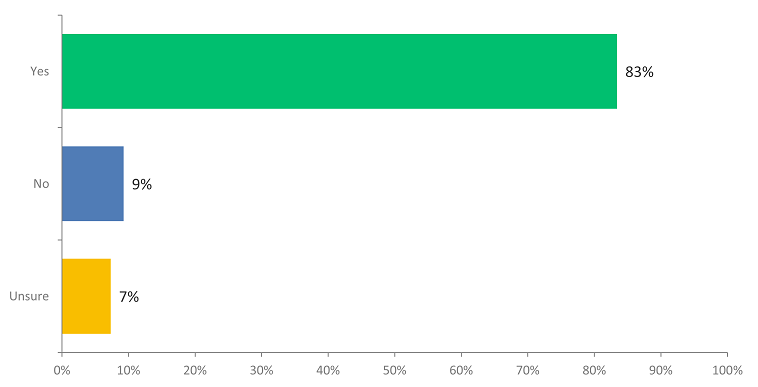
Rising living costs are keenly felt with 83% of people believing that costs are rising more than the officially-reported inflation rate.

Do you feel inflation has been higher than the official trimmed mean average of 5.75% in the last two years?
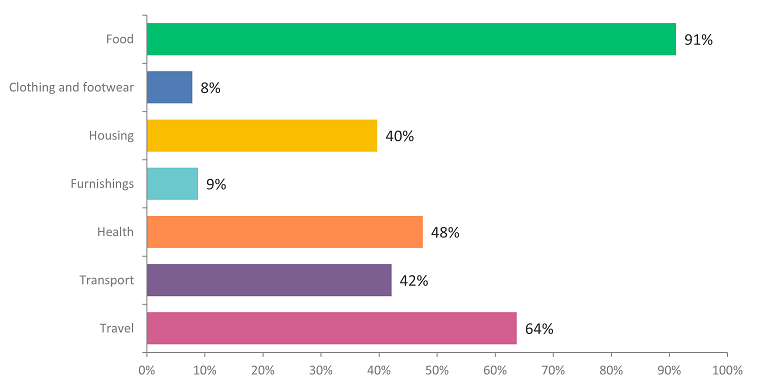
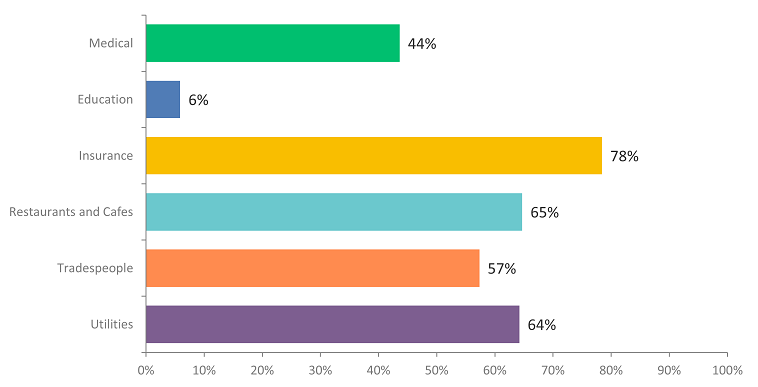
On which goods and services seem to have increased in price the most, the standout answers (selected by more than half of our respondents) were food (91%), travel (64%), insurance (78%), dining out (65%), tradies (57%), and utilities (64%).

What goods in particular seem more expensive? (multiple selections allowed)
What services in particular seem more expensive? (multiple selections allowed)
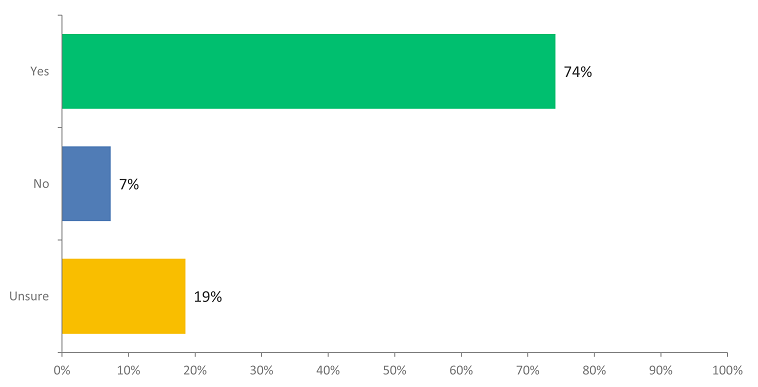
Almost three-quarters of respondents believe companies are taking advantage of the high-inflation environment.

Do you feel companies are taking advantage of the inflationary conditions?
The final question asked readers to share their more quirky and unusual anecdotes and examples of rising costs and inflation. While most comments are included in the longer report linked below, here is a sample:

  • We started the backyard vege plot and it's going gangbusters! We scour the neighbourhood for produce and share our abundance of navel oranges with anyone who comes near our front door.
  • Restaurant wine increases out of proportion.
  • An example last week, at the Grand Central shopping centre car park in Toowoomba Qld. The first 3 hours are free, however, my total time was 3 hours & 30 minutes. They charged me $2.00 for the additional 30 minutes & there was no provision to pay by cash. When I received my credit card statement I was charged $2.10. That was a 5% fee!!!!
  • Lower your standard of living. Shop around & consume less.
  • It is becoming increasingly expensive to use the convenience of digital payments as more and more outlets (service industry, hospitality, medical and so on) charge a credit card surcharge - and without prior warning.
  • I'm not one to scout about to save 6 cents a litre, but there are noticeable mark-ups of 50-60 cents a litre at some service stations. I ask you, why? 
  • Fuel surcharge on transport costs.
  • Restaurants adding weekend surcharges, also on holidays.
  • My doctor bulked billed and then changed to no bulk billing. There was no notification. You found out after the consultation. Now the medical practice is empty but you can easily get an appointment which was not the case with bulk billing.
  • Car insurance. My car is 1 year older so insured value is lower. No accidents but premium increased by over 20%.
  • Restaurants adding service fees on top of menu price rises (are we now becoming the US??) and pass through of credit card charges.

Full results and comments can be downloaded here.


  •   18 October 2023
  • 2
  •      
  •   
2 Comments
George W
October 20, 2023

I'm sorry, I own a business and the charge that companies are taking advantage of inflation to raise prices is mostly bollocks. Have you seen cafes and offices in CBDs lately. They are full only 2-2.5 days a week. The knock on effects are enormous for CBD pubs and others. They need to pay exorbitant rent - how else bar raising prices are they meant to survive? And that doesn't take into account cost inflation, which is huge. I recently came off a 3-year electricity contract and the new one is up 150%. Add in minimum wages going up 7%, rent by CPI of close to 6%, and what do you think companies have to do to keep the doors open?

Lyn
October 23, 2023

After reading full list of results/ comments where insurance increases crop up often, my decision 30 yrs ago on moral grounds to not invest in insurance companies seems justified. In floods and fires many uninsured in high risk areas when we see news and those who are insured and rightly claim, contribute to overall increase of insurance cost for all after major calamities. When one sees pictures of burned houses there is often burned tree/trees in close proximity to a home and I think, why don't they remove trees near home to minimise risk? Councils may be to blame re tree removal, there seems a disconnect between removal and risk of fire to home. I know person who took 10YEARS for approval to remove but they kept at it for 10 years to remove risk of damage to home, approval after last major fires came to their fence from council land full of tall trees. Meanwhile, cost of removal trebled to fixed income retiree. Let's not go to how councils approved homes in historical flood areas and adds to everyone's insurance cost after major calamities. Supposedly having alarms and keyed window locks gives discount re risk, time ins. companies gave extra discount for not living in flood area and no trees near the home.


Leave a Comment:

RELATED ARTICLES

The overlooked driver of energy inflation

This 'forgotten' inflation indicator signals better times ahead

Welcome to Firstlinks Edition 597 with weekend update

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.