Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 277

Sustainable investing focuses on the future

In the rapidly-evolving world of socially-conscious investing, sustainability has arrived. The integration of environmental, social and governance (ESG) factors into fund managers’ fundamental research processes has become mainstream in recent years. However, sustainable investing takes that approach one step further by also considering the impact a company has on society.

Sustainability is gaining traction with investors, but it is not without challenges. Typically, socially-conscious strategies have focused on negative filters, without taking into consideration the positive contribution a company might have on society. Investment returns can be compromised due to constraining the investment universe and data. Each companies’ ESG performance can be of variable quality, resulting in many arguable or 'grey' areas.

The rise of sustainable investing

Research conducted by Responsible Investment Association Australasia (RIAA) in 2017 shows that nine-in-10 Australians think that sustainable investing is important. Furthermore, 63% of Australians expect their advisers to incorporate their values and the societal or environmental implications of investments. Millennials are leading the charge. One key attribute of Millennials, now aged in their 20s and 30s, is their stated desire to live lives consistent with the values they espouse. About 84% of them say they want to invest in a socially-responsible way and their influence will grow as they become older and richer.

International organisations such as the United Nations and European Union are encouraging corporates to generate company profits in a positive and sustainable manner. Many of the world’s leading companies now consider sustainability in their corporate strategies, including Coca-Cola, Apple, BMW, Adidas, and H&M.

The United Nations has developed its Sustainable Development Goals Agenda (SDGs), a set of goals which, if achieved, would ‘end poverty, protect the planet and ensure prosperity for all’ by 2030. Broad and ambitious in scope, the SDG Agenda addresses the three dimensions of sustainable development: social, economic and environmental, as well as important aspects related to peace, justice and effective institutions. These goals are shown below.
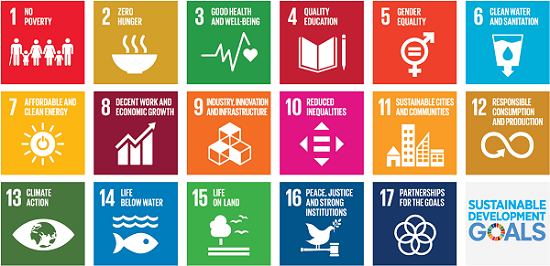
Assessing the extent to which a company’s operations and products support the SDG agenda is an appealing way to address broader sustainability.

The investment manager as advocate

The investment industry is also evolving and, in some areas, driving the change. Simply having a ‘clean hands’ approach is no longer good enough. Many existing socially-conscious funds purely screen and exclude whole industries on the basis that they have a negative impact on society. This approach strictly reinforces a company’s adherence to ESG principles but fails to consider whether a company is contributing positively to society.

We believe investment managers should also be playing an ‘advocacy’ role, by putting pressure on individual companies to improve their ESG performance. In turn this operational improvement can lead to improved financial outcomes, along with the broader positive impact to society.

The dilemma for investment managers has been their fiduciary responsibility: their primary goal is generally to maximise returns for a targeted level of risk. In the past it has usually been assumed that pursuing both social good and profits would damage investment outcomes, as screening out potential investments or pursuing goals other than profit maximisation might result in the missing of opportunities. These are legitimate concerns and have often resulted in an unwillingness to commit to socially conscious investing.

However, investing sustainably doesn’t necessarily mean sacrificing potential returns.

Investing for good and for returns

The most common objection to investing with a social conscience is that an investor needs to sacrifice returns to invest for the greater good. An increasing body of evidence is beginning to challenge this view, and the outcomes achieved by some such funds suggest it is possible to have both. Industry research summarised by Willis Towers Watson in their paper ‘Show me the evidence’ confirms better ESG scoring-companies tend to provide moderately better risk-adjusted returns over the long term. From the evidence collected to date, Governance (‘G’) and company engagement have proven to lead to a positive impact on returns.

A commonality across the research points to a heightened quality factor via a lower cost of capital which in turn leads better stock performance. Published University of Oxford research by Clark, Feiner and Viehs (2014) on over 190 sources showed 90% of the studies on the cost of capital demonstrate that sound sustainability standards lower the cost of capital for companies. 88% of that research showed solid ESG practices result in better operational performance of firms.

Alphinity agrees with Willis Towers Watson’s conclusion:

“Astute long-term investors understand that ESG factors are not necessarily non-financially related factors, as is often perceived, but rather an additional source of insight into the risk and return profile of that investment.”

Selecting better scoring ESG companies is likely to become another pillar of active management, along with conviction, skill and a disciplined consistent approach.


Stephane Andre and Bruce Smith are Principals and Portfolio Managers at Alphinity Investment Management, a boutique fund manager in alliance with Fidante Partners, a sponsor of Cuffelinks. This article is for general information only and does not consider the circumstances of any individual.

For more articles and papers from Fidante, please click here.


  •   23 October 2018
  • 2
  •      
  •   
2 Comments
Ashley
October 24, 2018

I want to see returns measured to the last basis point on specific investment decisions based on concrete ESG rules. That way investors can make informed decisions about the trade-offs. On the other hand If ESG actually improves returns – then you should shout from the rooftops – with specific details on each ESG decision so people can test.

Bruce Smith
October 25, 2018

Hi Ashley, thanks for your comment. Our message from this article is that people are increasingly looking for funds that consider more than just returns, but that you don't necessarily have to get lower returns when you do that.

In reality, no decisions are ever made purely on the basis of ESG, it is one of many things we look at when investing in a company. In the end portfolio returns are a function of the stocks in the portfolio and the weighting of those stocks. The fact that there are 12 ESG-focused equity funds in the latest Mercer table and the range of those funds' performance over the year to August is as low as 10.5% and as high as 24% (8% pa to 14%+ pa over three years) suggests to us that the robustness of a manager's investment process and its skill in selecting stocks is going to be a more important determinant of returns than ESG considerations alone. We've found that a "bad" company is not necessarily a bad investment, and a "good" company necessarily a good investment. But we have also found that taking ESG into account can alert you to risks and, in some cases, help you to identify opportunities.

ESG is one of the positive screens we employ, the other is the extent to which a company addresses Sustainable Development. But the final decision to invest requires the company itself to be a good investment according to our investment process, undervalued companies in an earnings upgrade cycle, which has delivered good alpha over the almost 15 years we've been applying it.


Leave a Comment:

RELATED ARTICLES

Why ESG can still play a crucial role in investor portfolios

Beyond the acronym, navigating important ESG choices

Mike Murray on watching for the changing narrative

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.