Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 203

Tax deductions are still available for property investors

When looking to purchase an investment property, most buyers consider location, purchase price and tenanting ability, while depreciation is often overlooked. Depreciation can unlock the cash flow potential within an investment property, often resulting in thousands of additional dollars for the investor each financial year.

Announcements made in the 2017 Federal Budget may change some of the eligibility for depreciation, but investors should not overlook where it remains available.


What is depreciation?

As a building gets older, items wear out – they depreciate. The Australian Taxation Office (ATO) allows property owners to claim this depreciation as a tax deduction by any property owner who obtains income from their property.

Capital works deductions are based on the historical cost of the building excluding the cost of all ‘plant’ and non-eligible items. As a general rule, residential buildings which commenced construction after 15 September 1987 and commercial properties after 20 July 1982 are eligible for the capital works allowance.

Although these time restrictions apply, older properties have often undergone renovations. Renovations completed within the legislated dates can also entitle the owner of the investment property to deductions, even if the renovations were completed by a previous owner.


Common depreciable items in an investment property

Plant and equipment items, commonly known as removable assets, are also eligible for depreciation deductions (but see comment on 2017 Budget later). Each plant and equipment item has an effective life set by the ATO which determines the deduction.

Some plant and equipment depreciable items commonly found within a property include hot water systems, dishwashers, carpets, blinds and curtains, light shades, ovens, furniture, range hoods, smoke alarms and cook tops.


Case study

An investor has purchased a property for $420,000 and is receiving $490 per week in rent for a total income of $25,480 per annum. The estimated expenses for the property include interest, rates and management fees, which total $32,000 per annum. The following scenario shows the investor’s cash flow with and without depreciation. A typical $420,000 unit will show a total deduction of $11,500 in the first full financial year.
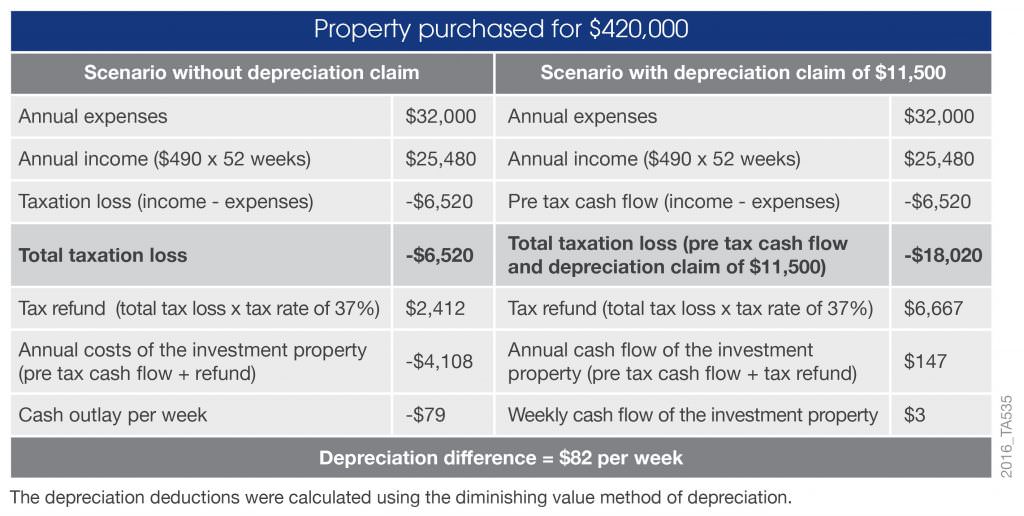
In this example, the investor uses property depreciation to go from a negative cash flow, paying out $79 per week, to a positive cash flow scenario, earning $3 per week, saving $4,255 for the year.


Claiming depreciation during renovation

When old assets like carpet or hot water systems are replaced during a renovation, the owners may be entitled to claim any residual depreciation as a tax deduction. Property owners should consider a pre-renovation depreciation schedule and update an existing tax depreciation schedule after work is completed to ensure they capture deductions for any new items added during the renovation.


Changes in the 2017 Federal Budget

Under proposed changes, investors who exchange contracts on a second hand residential property after 7:30pm on 9 May 2017 will no longer be able to claim depreciation on plant and equipment assets. Investors who purchase a new property will be able to continue to claim these items as previously.

We are currently speaking with government to further understand the intricacies relating to the proposed changes.


Claim property depreciation this financial year

To maximise cash flow, investors should engage a specialised Quantity Surveyor to complete a tax depreciation schedule. The fee for a tax depreciation schedule is 100% tax deductible. The schedule will show deductions for the life of the property (40 years) and will ensure the property owner improves the return on their investment.


Bradley Beer is the Chief Executive Officer of BMT Tax Depreciation, a leading provider of tax depreciation schedules for investors. This article is general information and individuals should seek their own tax advice.

  •   25 May 2017
  • 2
  •      
  •   

RELATED ARTICLES

Maximising your property tax depreciation and claims

EOFY and new depreciation rules for property

What tax deductions are available to property investors?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.