Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 125

Timing badly: generating poor returns in good strategies

In the 1987 film Wall Street, Gordon Gekko is challenged by his prodigy, Bud Fox, on how much money is enough. Gekko responds that it’s not a question of enough - it's a zero sum game. Money itself isn't lost or made, it's simply transferred. Somebody wins, somebody loses.

Significant new research soon to be published in the Journal of Portfolio Management* reveals a win lose dynamic in mutual fund investing (what we call ‘managed funds’ in Australia). The key finding is the average United States mutual fund retail investor underperforms the fund they invest in by about 2% a year. While the fund’s investment strategy may be sound and generating outperformance against a benchmark, investors’ poor timing of when they buy in and sell out effectively transfers elsewhere the value premium created by the fund.

In reaching this finding the researchers analysed over 1 million fund flow observations across 18,665 funds between 1991 and 2013. The dollar-weighted average of investors’ returns within a fund was compared to the buy and hold return for the whole fund.

As the researchers explain:

“The average return from a buy and hold implementation ignores the fact that many investors trade on a regular basis and that the actual return received by the average investor might be very different from the buy-and-hold return. Dollar weighted returns account for this trading by augmenting the average with information about fund flows.”

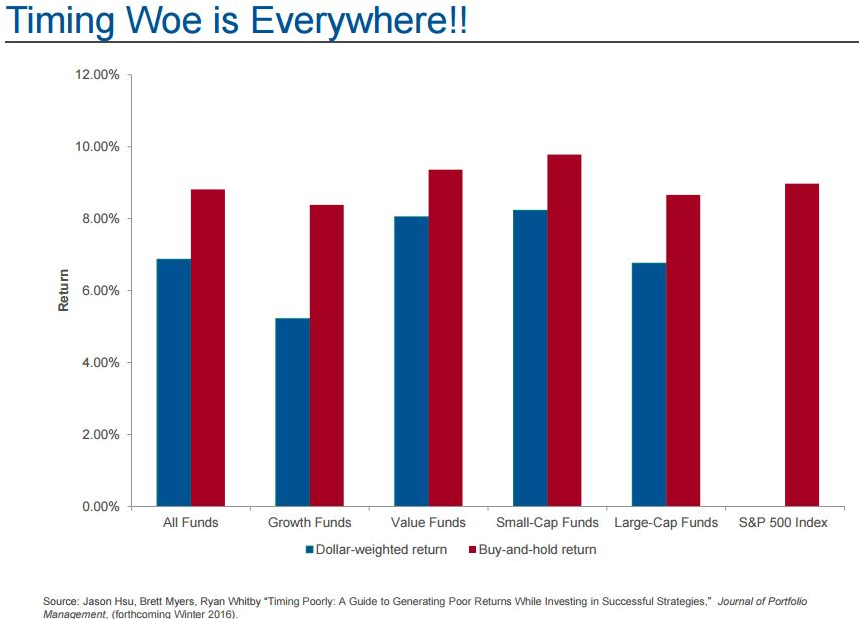
The pattern of average investors’ underperformance against overall fund performance was consistent across funds irrespective of varying investment styles – value, growth, large and small cap, as shown below:
The less sophisticated are worst at timing

Investors mistiming the market are underperforming by an average 1.3% to 3.1%, with worse investor underperformance seen in growth compared to value funds, and in large cap compared to small cap funds. For example, fund investors seem to time poorly by investing in value funds when the ‘value’ factor is expensive, and redeeming from value funds when ‘value’ offers opportunities. Poor timing is not confined to value funds, and confirms other studies which show investors attempt to time their allocations to funds.

The research reveals what is happening, but it isn’t possible to definitively conclude from the data why investors time poorly, and nor was this a stated purpose of the research. What is especially interesting is that it examines the actual investment outcome for mutual fund investors, not the performance of mutual fund managers.

The data leads to an hypothesis that investors who time poorly are less financially sophisticated. This is deduced from more detailed multivariate analysis revealing the worst average returns were seen by investors who hold funds with higher expense ratios, and who invest in readily available retail-oriented mutual funds. Investors in these funds were observed as more likely to time poorly, buying after and selling before periods of strong performance.

Their poor timing may be unintended – for example investors may withdraw to meet unexpected financial needs. It may be related to low financial literacy. They don’t understand their investment timeframe isn’t suited to the fund’s recommended timeframe. Or it may be from overestimating their investing prowess. They are consciously trying to time outperformance or chasing previous hot performance by the fund. Whatever the reason, they have timed poorly and are Gekko’s losers. In fact, the authors subtitle their paper, “A Guide to Generating Poor Returns While Investing in Successful Strategies.”

Value premium is transferred to the winners

So who are the winners on the other side of the trade? The research is based on United States data where mutual funds account for nearly 20% of the equity market. The authors suggest institutional investors are most likely to be capturing the return premium from retail fund investors: smarter traders adhering to more considered strategies. By giving away the excess return, retail investors in value funds might themselves be financing the value premium often seen in fund performance, and ensuring its continuance.

What might be done about it? After all, retail mutual fund Product Disclosure Statements are filled with recommended investment timeframes, likelihoods of negative returns over given time periods, explanations of different investment risks, statements that past performance is no indication of future performance and the importance of time in the market as distinct from timing. What is missing that will grab investors’ attention and help them avoid poor timing?

Investors may reconsider their own behaviour if presented with the hard real dollar impacts of poor timing experienced by others. Perhaps fund providers could undertake similar analysis on observations within their own funds and present key findings to investors and financial advisers (assuming of course empirically the same pattern holds). It points to a need for greater financial education to protect investors from themselves.

Without behaviour change poor timing will continue and many investors will miss the returns their mutual funds generate. They lose and somebody else wins.


*Jason Hsu, Brett Myers, Ryan Whitby, “Timing Poorly: A Guide to Generating Poor Returns While Investing in Successful Strategies”, Journal of Portfolio Management (forthcoming Winter 2016).


Iain Middlemiss was Executive Manager Strategy at Colonial First State and Head of Strategy at Superpartners. This article is for general educational purposes only.


  •   5 September 2015
  • 5
  •      
  •   
5 Comments
Adam
September 03, 2015

But who knows what they invested in for the periods they were not invested in the mutual fund? If you read it quickly a reader would interpret this as “the average mutual fund investor underperforms by nearly 2% a year” which is different to what is actually written.

Jerome Lander
September 03, 2015

Very simply, most investors, unfortunately, simply invest in something after it has had a good run, and is more likely to be overpriced and at risk of mean reversion. In other words they chase past performance for behavioural and psychological reasons. It is really that simple. They don't understand things from first principals.

Investors would be better off understanding that everything ebbs and flows. They should make sure that they are actually exposed to something good in the first place, and then generally stick with it subject to it being aligned with their objectives.

The problem currently is that most people are not exposed to something good or in any way genuinely value adding..., in an environment where they may be completely destroyed by such an approach. They have been taught that cheap is good, and that not doing due diligence and trusting the overall market will get them where they need to go. Such an approach is generally very dangerous and relies predominantly if not purely on luck, particularly given the potential scenarios that exist today. It is a critical and common mistake based on a misunderstanding of reality.

Of course, investors would be better off by investing alongside people with genuine expertise who use the foolishness and ignorance of the market at large as profit making opportunities, and who are able to genuinely add value through time.

Anthony Robinson
September 04, 2015

Why bother with fund managers just pick well performing (over 10yrs) listed investment companies. Much better than fund managers! They don't have to sell the position if the fund drops or invest if funds flow into the fund.

Paul G
September 04, 2015

Of all the value adding activities of a Financial Planner probably the most value is added for clients by convincing them to stay the course during market falls and not overexposing themselves to growth assets when times are good.
That is, to ensure their asset allocation is correct considering their personal objectives.
see Brinson, Hood & Beebower determinants of market performance.

Michael
September 24, 2015

If I may, I would really like to see a physical example of this...that is, let's say I bought xyzabc fund when it's unit price was relatively high, but, I am a long term investor and do not need the money immediately. Will it follow that in the long term xyzabc will return a positive ?


Leave a Comment:

RELATED ARTICLES

Ray Dalio on 2025’s real story, Trump, and what’s next

The psychology of REIT investing

My disinterest in investments as an investment specialist

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.