Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 355

Too many unknowns: hope isn't an investment thesis

Over the next several weeks, investors will experience horrendous macroeconomic data. For instance, based on initial jobless claims data, more jobs were lost in the US in four weeks recently than were created during the entirety of the now-ended 11-year business cycle. So yes, economic data will get worse, but it may not matter to capital markets because this is a market known.

Markets factor in expectations

Markets are a discounting mechanism of ‘known knowns’ and the weighted probabilities of many ‘known unknowns.’ And an upcoming earnings recession won’t surprise markets any more than terrible labour data will.

Two known unknowns are the pace of the economic recovery and the path of post-recession earnings. Since the March 2020 lows, US equities have retraced over half of their losses. Stated another way, in the face of the worst recession of our lifetimes, equity valuations are down only to June 2019 levels. Over the past few weeks, investors have increasingly assigned a higher probability to a shorter-than-anticipated recession and a stronger acceleration in profits.

We’re not epidemiologists, so we won’t opine on the infection curve or the risks of a second wave, though we certainly hope for the best. But as they say, hope isn’t an investment thesis.

Regardless of when the virus peaks or the economy reopens, life will be different. Politicians, the media and investment strategists and economists (but not us!) have equated the world’s efforts to contain COVID-19 with fighting a war. While it may feel that way with everyone pulling together (thank you to the brave health workers and first responders!), pandemics alter long-term behaviour differently than wars.

The catalysts that generally drive V-shaped postwar recoveries are very different from pandemic-driven ones. In short, precautionary savings by both consumers and businesses create different economic and inflation environments than those previously observed in postwar economies.

The scramble into new capital raisings 

A market known unknown, if you will, that we want to explore further is the likely earnings dilution resulting from future equity capital having to be raised.

During periods of economic strength, many corporations take advantage of all available levers to maximise their appeal to equity investors. Part of the reason for this is that the wrong incentive structure is in place for many corporate leaders. Over the past decade, working capital has been the priority for most CEOs, and lower balance sheet quality has been the lever. That dynamic has been on display more in the recent past than in any other period of recorded history. Exhibit 1 details the steady increase of billions of dollars’ worth of shares repurchased in the S&P 500 Index.
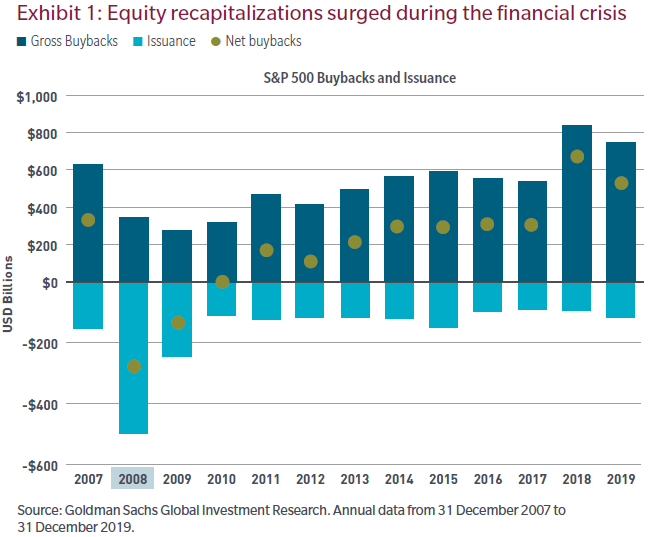
This isn’t new information, so we highlight 2008. As the fat tail risk of the GFC faded, emphasis turned from maintaining liquidity towards recapitalisation. That recapitalisation came via the equity market and at the expense of shareholders who suffered substantial dilution on a per-share basis.

Today, CEOs and CFOs — particularly those of companies that might not be able to carry on — are scrambling to secure liquidity. Profit maximisation is no longer the priority. Survival is the goal, as meeting next month’s debt maturity is all that matters. Balance sheets are now the focus, unlike in the past dozen years.

However, the nature of this recession is different from that of 2008, and not only because the recession is driven by a pandemic. The 2008 meltdown was driven by an overleveraged financial sector. However, this time around, banks and real estate investment trusts (REITs) weren’t the entities that extended balance sheet leverage to unsustainable levels in order to repurchase stock.

Instead it was every corporate sector but financials. And a fresh wave of recapitalisations is likely just getting started. There’s already been equity issuance by leisure and professional services companies in the US and Europe.

Too many unknowns for recovery conviction

None of us can guess what the duration of this recession will be, nor can we tell how strong the recovery will be. Yet many seem to believe they have sufficient visibility into any such recovery’s many known unknowns to make the high-conviction call that the recovery will be strong. We wish we had such conviction, but we don’t, and we don’t think you should either.

Instead of trying to make those calls, we’ve chosen to invest carefully, owning assets of enterprises for which the growth of working capital isn’t dependent on externalities such as financing, recognising that you can’t plan perfectly for black swan events such as the one we’re experiencing.


Robert M. Almeida Jr. is a Portfolio Manager and Global Investment Strategist, and Erik Weisman, Ph.D. is a Portfolio Manager and Chief Economist at MFS Investment Management. The comments, opinions and analysis are for general information purposes only and are not investment advice or a complete analysis of every material fact regarding any investment. Comments, opinions and analysis are rendered as of the date given and may change without notice due to market conditions and other factors. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343), a sponsor of Firstlinks.

For more articles and papers from MFS, please click here.


  •   29 April 2020
  • 1
  •      
  •   

RELATED ARTICLES

Market entry – dip your toe or jump in all at once?

The iron law of building wealth

The bright outlook for Australian fixed income

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.