Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 360

Welcome to Firstlinks Edition 360

  •   3 June 2020
  • 5
  •      
  •   

Weekend update: The US market rallied strongly on Friday with the S&P500 up 2.6% and NASDAQ another 2%, almost touching its all-time high. The creation of 2.5 million jobs in the US in May was much better than expected. Australia added 4.2% last week to continue the rebound, now only 16% off the February high. The market is firmly in 'risk-on' at the moment and ignoring bad news.

***

Drought, bushfires and coronavirus ... the Treasurer has admitted Australia is now in a recession after the fall in the March quarter GDP. The June quarter is certain to be worse. And such are the times we live in, despite blood and fires on the streets of dozens of US cities where 40 million people are unemployed, markets continue to rise and the ASX200 is now 35% up from its 23 March low. The market has factored in a V-shape recovery that still seems hard to fathom.

Much of the optimism is due to the stimulus packages. The withdrawal of up to $20,000 from superannuation is understandable for anyone struggling financially during the epidemic. A loss of retirement savings in 30 years is no match for a present-day need to put food on the table or pay the rent. But many young people who have accessed both JobKeeper and their super have more money during this crisis than ever before in their lives. Treasurer Josh Frydenberg actively encouraged it with statements such as “this is the people's money and this is the time they need it most”.  

There have always been rules that allow access to super for hardship, but it was previously difficult to qualify. Where the new policy falls down is the ease with which so many can withdraw. Although in theory it is targetted at people disadvantaged by the virus due to unemployment or a loss of hours, the guidelines say:

"You will not be required to attach evidence to support your application; however, you should retain records and documents to confirm your eligibility."

It's a low bar to jump over, and less than 1% of applications have been rejected. There is no requirement to confirm the loss of hours is not compensated by government support. About 1.8 million people have applied for $13.2 billion already. Given there is a month to go on the first $10,000, with another $10,000 from 1 July, withdrawals could top $30 billion.
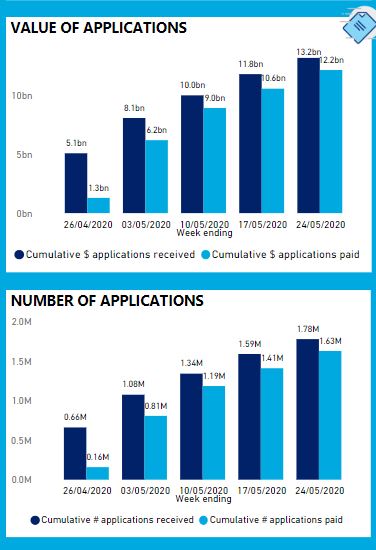
Source: APRA Early Release Scheme statistics

Most worrying is evidence (from a smallish sample of 13,000) from AlphaBeta (part of Accenture) that 40% of people who have withdrawn money have experienced no drop in income. The research suggests increased spending on discretionary items such as clothing, furniture, cars and alcohol, with about 12% spent on gambling. There's a lot of 'want' rather than 'need'.

As a recent article by David Bell and the compounding article last week both show, the long-term consequence of early withdrawal is a major loss of retirement savings. Scott Morrison says the Government has no interest in what people are spending the money on, but consider these statements from retailers (courtesy of NAOS):

“JobKeeper in our view is certainly fueling a lot of growth [in sneaker sales]. It really resonated with kids that they had some money.” Daniel Agostinelli, CEO, Accent Group, owner of high-end sneaker stores, HypeDC and Platypus.

“Used vehicles have really taken off – much stronger than new cars – and actually better than pre-COVID. It’s a lot of first-time younger buyers. In the past they would have caught the train or the bus – they’re now planning to drive”. Anthony Altomonte, Managing Director, The Alto Group, car dealers

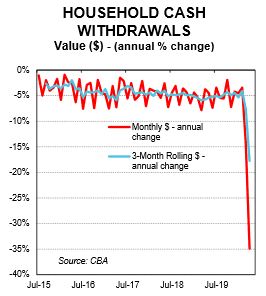
More cars on our clogged roads and less super in the accounts of young people with nice sneakers are two unwelcome, long-term impacts of COVID-19. The use of cash also has rapidly declined and this change will endure. Anyone who owns an ATM has become another victim of the virus.
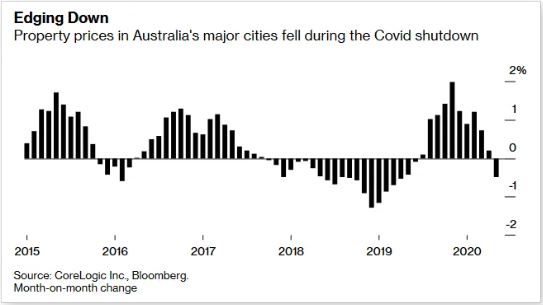
However, with $7 trillion in Australian residential housing, there is no doubt which asset class delivers the biggest wealth impact across the nation, and the first signs of a reversal from the boom of late 2019 are now in CoreLogic's numbers.
In Edition 360, a full 360 degree market review ...

Stephen Mayne is Australia's leading shareholder activist, and his analysis of Share Purchase Plans (SPP) shows how poorly retail shareholders are often treated. For example, in my own case, an allocation of only 672 shares with a refund of $27,048 on a $30,000 application for Auckland Airport was not worth the paperwork, and the Cochlear story in Stephen's article is as bad.

It's great to welcome back my co-founder Chris Cuffe who describes his use of private debt funds in managing the portfolio of the APS Foundation. Read about the tax advantages of charitable subfunds as we near the end of FY20.

Then updates from leading Australian investment managers. Matt Reynolds describes three market facts and three mistakes everyone should consider, Anton Tagliaferro shows the types of companies he is now looking for, and Kej Somaia discusses portfolio construction and explains how his asset mix has changed since COVID-19 hit. Decades of experience from these fundies.

It's easy to think that all index funds are the same, but it is often not easy to replicate an index. Duncan Burns describes what to look for.

Pamela Hegarty says the pandemic has accelerated digitial and disruptive changes, and she highlights the areas she is now watching closely.

The share price of Afterpay has moved from $8 to $50 in the space of only two months, and Lex Hall checks the fair value placed on the stock by Morningstar analysts. 

Each month, Jonathan Rochford reviews global media and provides links to stories most people have missed. Provocative, quirky, unusual and plain weird. 

This week's White Paper from Capital Group offers ten quick tips for retirees hit by market falls while drawing down a pension.

Graham Hand, Managing Editor


Latest updates

PDF version of Firstlinks Newsletter

ASX Listed Bond and Hybrid rate sheet from NAB/nabtrade

Indicative Listed Investment Company (LIC) NTA Report from Bell Potter

Plus updates and announcements on the Sponsor Noticeboard on our website


  •   3 June 2020
  • 5
  •      
  •   
5 Comments
Tom
June 03, 2020

Hi Graham,
Another great publication as usual. Thanks.
Do you have access to anybody who might be able to comment on the likely response of highly indebted governments to increasing inflation?

Graham Hand
June 03, 2020

Thanks Tom, we have published many articles on this subject because we think it will be important in years to come. Try these:
https://www.firstlinks.com.au/magic-money-printing-faces-reality-inflation
https://www.firstlinks.com.au/how-200-billion-is-magically-created
https://www.firstlinks.com.au/one-trillion-and-counting

David
June 03, 2020

Given the rush to withdraw money from super, I would have thought that most funds don't generally hold a lot of cash and therefore would have to sell assets (share holdings) in order to fulfil the amounts of money that fund members have requested. I have been expecting this to result in large sell-offs of share holdings and therefore downward pressure in the stock market. I am surprised to see that this is not happening, is there any light that can be shed on why the stock market is not weakening with so much cashing in of super?

Thanks

Graham Hand
June 04, 2020

Hi David, the amounts are not large enough to have the impact you suggest. There is $3 trillion in super with $2 billion new inflows every week. So 1% of all super assets is $30 billion. The total withdrawals to date are $13 billion. About 0.4% of assets. Cash on the balance sheet will easily cover that, even if most of it is withdrawn from one sector such as industry funds. A bigger issue for them is the switch from growth to defensive assets, but that has reversed since the market recovery.

Michael Pluta
June 04, 2020

They are not cashing all of their super only $10K. Most people might have $100K plus in super.
Some have used the money to buy shares which can be sold in a future liquidity crisis where this concession is no longer available.


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.