Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 560

Where Baby Boomer wealth will end up

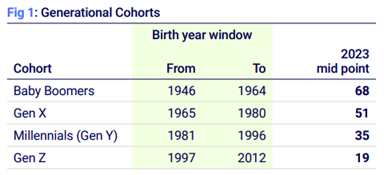
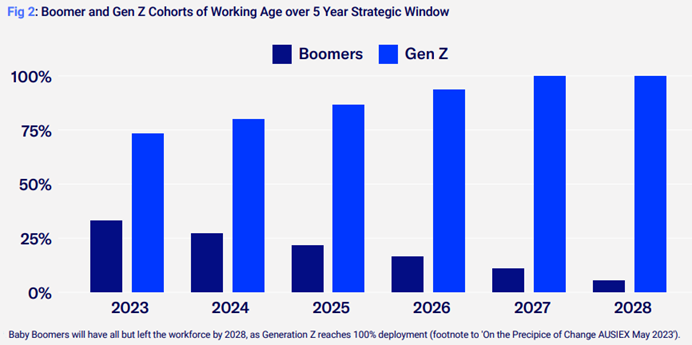
Within five years, all Baby Boomers will be eligible for retirement and the Boomer ‘bubble’ will have all but deflated out of the workforce by 2028. This demographic shift will have profound consequences for the financial industry and advisers.

A Productivity Commission paper, released in 2021, estimated that the transfer of inherited assets at about A$120 billion per year, and this figure is expected to grow to almost A$500 billion per year over the next 25 years.

The same research also found that the average age of inheritors is 50 years old, close to the mid-point of the age bracket corresponding with Gen X, which makes them an important part of the answer to the question about who will inherit the bulk of the baby boomer wealth.
Likely beneficiaries

Research suggests where money may be directed. The Future of Legacy Giving: Boomers and Beyond – Australia (November 2023), found that Baby Boomers and Gen X felt strongly that it was important to help others in need as well as your own family (55% and 61% respectively) and had a higher expectation that their family will need financial support from them (19% and 38% respectively).

Of arguably greater consequence, there also appears to be evidence that females will be the primary beneficiaries of financial flows from the transfer.

The report cites research commissioned by Schroders and McKinsey (UK and US respectively) suggests females will be the primary beneficiaries of the wealth transfer, inheriting 60% to 70% of the wealth transferred, this decade. As women statistically live longer than men on average, it’s not inconceivable they will have full control of their family wealth at some point.

All in all, it seems females are set to play a significant role in how the intergenerational wealth transfer will play out and this will likely have a profound impact on the adviser-client relationship and the advice industry overall. Whether the industry has adapted or is ready to is a different question.

Implications for financial advisers

According to The Value Gap, a report from Effortless Engagement, over 70% of clients would like their adviser to advise their children, though it may not be a fait accompli that children will use their parents’ preferred adviser. Overseas research suggests that many inheritors change their advisers.

Accordingly, working with clients to extend conversations about transfers to beneficiaries and including them in conversations, should be a key priority for the industry.

For advisers, Australian Ethical found in its 2023 Opportunity Next report, conducted with CoreData, that an overwhelming majority (77%) of advisers who engaged children in wealth transfer conversation, saw an increase in client satisfaction.

Education directly addresses a general need across generations but particularly for younger beneficiaries. Advisers are increasingly leveraging digital channels to help beneficiaries better understand the transfer and investment process and how decisions will impact them.

Advisers can also take advantage of new client portal and reporting technologies to be better informed as to the composition and performance of their portfolios and help strengthen communication and trust between transfer stakeholders.

Technology key

While the intergenerational transfer of wealth presents a substantial opportunity for advisers to engage clients and beneficiaries to establish resilient, long-term revenue streams, success is predicated heavily on their ability to add value as well as serve them profitably.

Naturally, technology is part of the answer. Modern and fully-featured trading platforms provide advisers access to the wide range of markets and asset classes required to build bespoke client portfolios in precise alignment with their objectives and risk profiles.

The net effect and arguably a key role of technology through the wealth transfer is to help address the challenges of communication and trust as root causes of transfer, ensuring there is a common and mutually agreed fact-base for stakeholders in order to deliver transfer plans their best chance of success.

At the same time, technology can help deliver significant operational efficiencies to a practice, allowing them to navigate the challenges and take advantage of the opportunities from the intergenerational wealth transfer.

Adapting to change

Investors and the wealth management industry has always adapted quickly to new technologies to improve products and services.

Our industry has, and will continue to be able to, deal with change. It is just happening faster and with higher impact than many realise.

With the older generations about to leave the system, the younger generations face different challenges than those that came before them, and the transition to innovation in the digital world is continuing apace.
The wealth management industry and equity capital markets are proven at adapting to help the economy find new ways to create capital and increase wealth. It is essential that industry participants become more active in understanding and discussing the changes that are now taking place and engage across the value chain to plan and execute change.

Industry participants need to accelerate their preparations for intergenerational transfer, as the Baby Boomer boom is over.

The full research paper on this topic can be found at: https://www.ausiex.com.au/media/202227/2024-ausiex-intergenerational-wealth-transfer-rgb.pdf.


Te Okeroa is Head of Sales, Trading and Customer Relationships at AUSIEX. This information contains general information only and has been prepared without taking into account your objectives, financial situation or needs.


  •   15 May 2024
  • 7
  •      
  •   
7 Comments
Ruth Henderson
May 16, 2024

It's difficult because of the privacy laws.

Andrew Smith
May 17, 2024

Relevant, but one would suggest that the baby boomer cohort will not disappear, but with remaining oldies account for a whopping 7+ million of the population vs. media focus on mislabelled temporary 'immigrants' i.e. students, who are 'net financial contributors'.

This will impact assets, tax income and budgets till mid century as we near the start of the 'big die off', mother lode of demographic change in permanent population.

One thinks our retirement income system i.e. hybrid means tested pension &/or super, according to offshore analysis, continues to rank in top 5 globally for sustainability versus nations using a social security insurance subscription, linked to years employment, leading to fund shortfalls etc., as working age declines.

Lex
May 17, 2024

I’m 74 and still working with my own business. Furthermore, I am working with my daughter. As for 2028 all but gone - not I!

John
May 18, 2024

Ruth is right. Also a fin advisor is not needed to work out any of the wealth transfer issues

Chris
June 22, 2024

"what are the implications for the wealth management industry"; well, shock and horror, financial planners MIGHT actually need to engage with Gen X. My personal experience has been that they don't unless they are also Gen X.

Jack Smith
October 17, 2024

I've heard that the median amount of wealth transferred is quite low, because there is a concentration of wealth in a small cohort. If that is true, then all this is moot.

Sam
January 03, 2025

As financial advisors rarely have understanding of crypto, they will become mostly redundant to the needs of younger generations that inherit this wealth


Leave a Comment:

RELATED ARTICLES

Super was built for a very different Australia

Super is catching up, but ageing is a triple-threat

Investment bonds for intergenerational wealth transfer

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.