Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 617

Will young Australians be better off than their parents?

There’s an unspoken pact in Western countries including Australia that each new generation will be better off than the last. Will that be the case this time around?

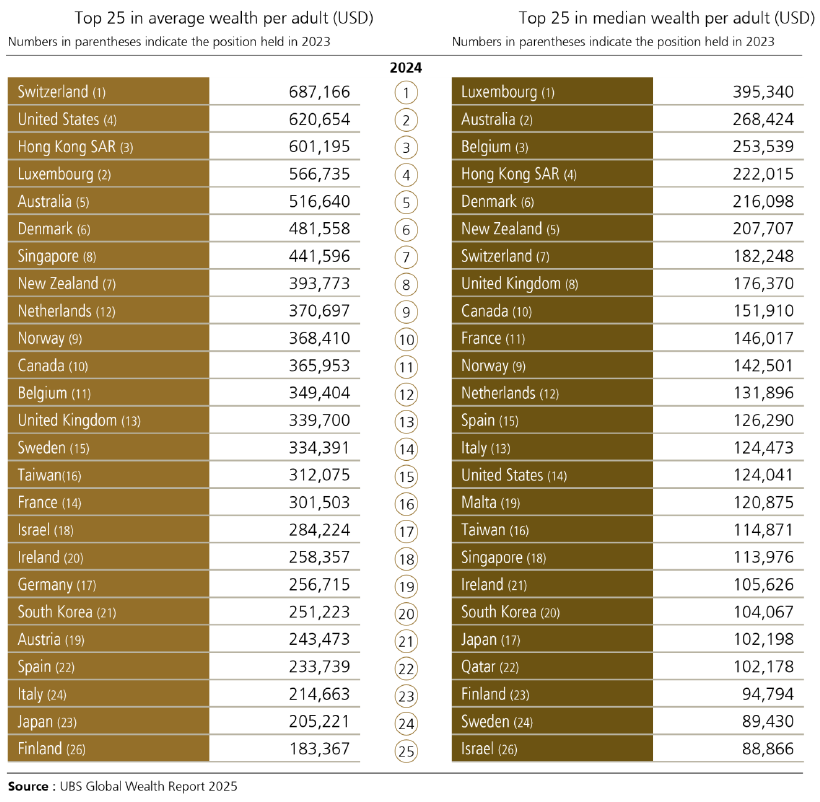
There’s an existential angst among young and old today that our kids will be worse off than their parents. On the surface, the angst seems hard to fathom. After all, Australia is wealthier than ever. According to UBS, our wealth grew 11% in 2024, and we rank second for median wealth per adult in the world.
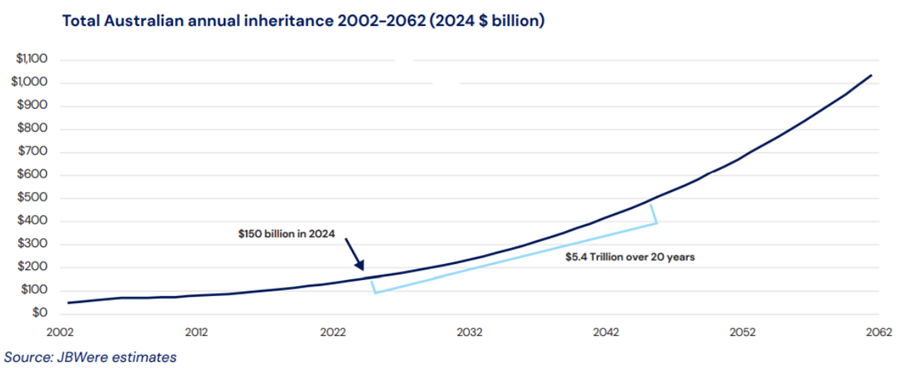
It’s true that much of this wealth resides with older Australians. Yet, JBWere estimates that some $5.4 trillion of this wealth will be transferred to younger generations over the next two decades.
What’s the problem, then? Well, dig a little deeper and the prospects for our young may be more tenuous.

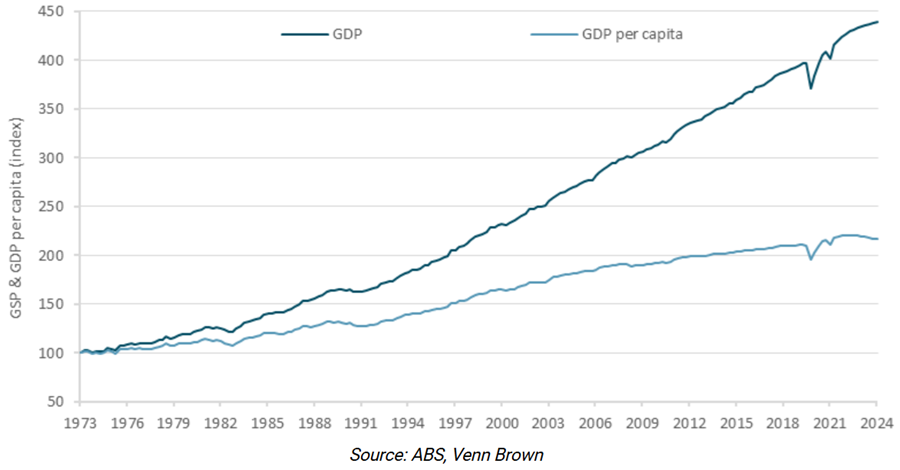
First, living standards have stagnated in Australia over the past decade. While economic growth has risen, it’s mostly been driven by increased immigration. On a per capita basis, GDP is barely above 2015 levels.
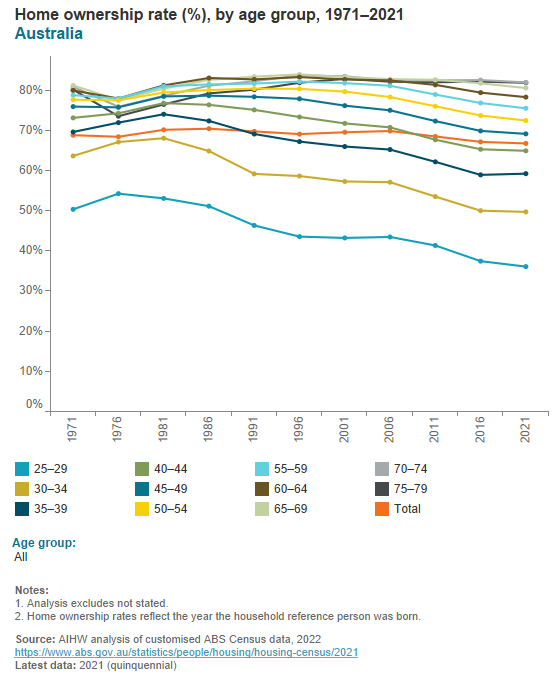
Wages have struggled to keep up with inflation. Meanwhile, costs in essentials such as groceries, education, and housing, have soared since Covid. That’s resulted in record university debts and declining levels of home ownership for younger age groups.
Tightening belts

The strains on the young show up in household spending data.

KPMG says that younger Australians are pulling back on recreational spending to cover costs like mortgage repayments, rent and other essential expenses, while older Australians are enjoying more travel and dining out.

The top five categories as a percentage of household spending for each age group in 2023-24 were:
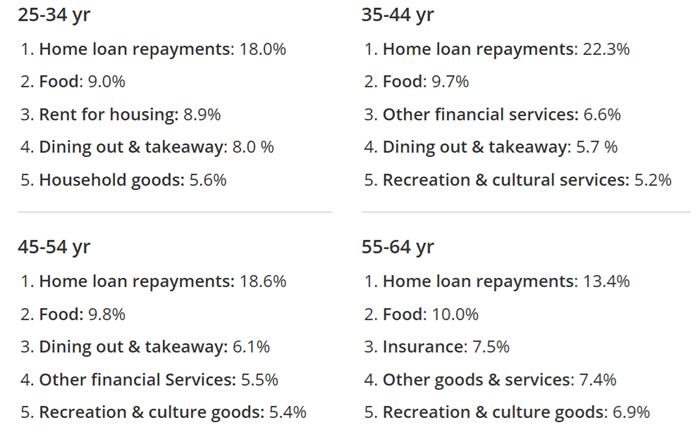

Note: the data captures the average spend of a household and does not reflect the average spending of an individual. Source: ABS: KPMG.

While the top expenses for all Australian households continue to be mortgage repayments and good, 25–34-year-olds are spending more on rent than any other age group, highlighting the declining homeownership rates of this generation.

KPMG Urban Economist Terry Rawnsley says that “we are witnessing the rise of 'Generation Rent’, with saving for a deposit and servicing a home loan increasingly challenging, especially in our capital cities.”

It may not be all bad

A new report from thinktank, E61, ‘Will young Australians be better off than past generations?’, suggests negativity around the outlook for younger generations may be overdone.

It admits that the young are more indebted. Since 2012, the number of Australians under the age of 35 with a HELP loan has risen from 20% to 30%. The average size of these debts has also increased by more than 30%, reaching $26,463. And younger people are taking longer to repay their loans. The average age for final repayment of loans has grown from 32.7 in 2012 to 34.8 now.
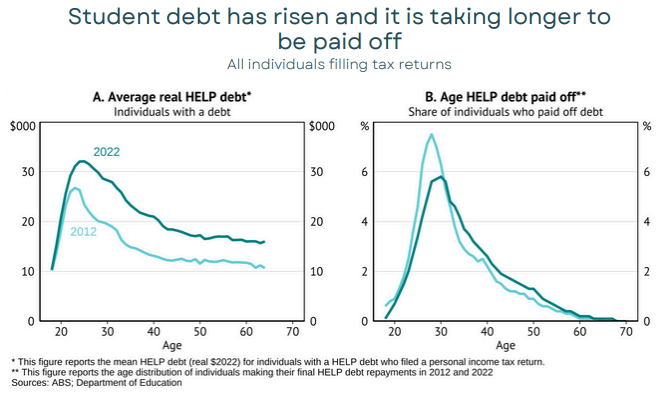
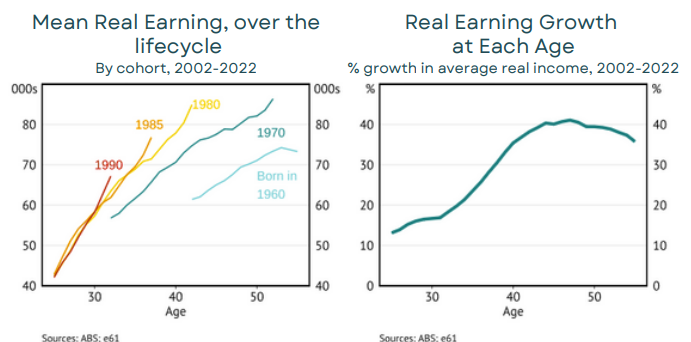
And wage growth has been slow. The report says that since the GFC, workers under the age of 40 have seen their income grow by less than half the rate of those aged over 40.  This trend has puzzled economists, who offer a variety of potential explanations, including rising underemployment, a shift toward more casual work, pay award decisions, and an oversupply of workers relative to available high-quality jobs.
Also, the report says that while the jobs market has been strong, it’s benefited women more than men. The unemployment rate for men aged 15 to 24 is 10.6%, far higher than their female counterparts at 8.3%. E61 partly puts that down to a structural decline in traditionally male-dominated industries such as construction, manufacturing, and mining.

The report notes that opportunities to get ahead in regional areas have also become more difficult. More than 10% of young people are neither in full-time study nor work, compared to 7% in capital cities. For young men in the country, this share has increased from 5% in 2000 to 9% now.  

Finally, E61 acknowledges that homeownership rates among the young are declining. Today’s 25- to 34-year-olds have lower home ownership rates than their parents when they were the same age, with a greater disparity in capital cities.

Despite these challenges, the report says there’s room for optimism. In many ways, young Australians have access to opportunities that weren’t available to their parents and grandparents.

Today, they’re better educated, earn more in the early stages of their careers, and have more diverse and flexible job paths. Young people are also benefiting from tremendous technological advances in artificial intelligence, robotics, and the like, which is giving them greater access to information through the internet, improvements in the availability of digital goods, and cheaper consumer goods.

Younger people are also building superannuation balances over longer careers at higher rates, and many of them will inherit a slice of the $5.4 trillion intergenerational wealth transfer over the next 20 years.

Lastly, the report makes the point that changing patterns in consumption and wealth-building mean economic achievements, like moving out of home, buying a house and starting a family – are still happening, but they’re often occurring later in life than with previous generations.

What should governments do?

The report says policymakers should consider the following to ensure younger people are better off than previous generations:

1. Don’t jump at shadows. 

E61 says young people may still experience traditional markers of economic security and adulthood but just later in life. Distinguishing between what is temporary, what is permanent, and what reflects a change in people’s preferences will be important. One risk is in assuming that younger people should have things at the same time as previous generations. That may not be the case.

2. Beware one-size fits-all solutions

The report says that this generation’s journey toward adulthood is far from uniform. It thinks gender and geography are key factors shaping outcomes for young Australians. That being the case, it will be important for governments to provide specific solutions rather than generic ones.

3. Manage economic and social trade offs

Change brings benefits and costs. For instance, technology is a wonderful advance though there’s also evidence that it’s impacting the mental health of young people, especially young women. Governments will need to be aware of the potential tradeoffs to future policies to help the young.

It doesn’t address the big issues

While the E61 report is a balanced one, its conclusions are vague and don’t consider the two issues that can most improve the lives of younger people: making housing more affordable and improving living standards via better productivity. Get these things right, and the young will be better off than their parents. Get them wrong, and the current challenges will only get worse.

Neither is an easy fix, though we’ve discussed some of the potential solutions in articles (here, here and here) in recent weeks.


James Gruber is Editor of Firstlinks.


  •   25 June 2025
  • 10
  •      
  •   
10 Comments
James
June 26, 2025

When you let speculation on property become the only national obsession to get wealthy, then we may super enrich a few generations, but impoverish all future generations.

CC
July 01, 2025

Australia has sold it's soul for a neverending property bubble, to the detriment of younger generations

GeorgeB
July 01, 2025

"we may super enrich a few generations, but impoverish all future generations"

All future generations will not be impoverished because property wealth will always be recycled from current to future generations. What may happen is that property ownership may become more concentrated as is already the case in much of Europe where a majority rent for life (eg.the average cost of a 100M2 apartment in London is about AU$1.6M and in Paris about AU$1.8M-that will still buy a median house in the capital cities in Australia)

CC
July 02, 2025

Can't compare Australia to those countries, George B.
England has about 60 million people in a country about a quarter the size of NSW, and France too is smaller than NSW but has 68 million people.
It is nonsensical for property prices in Australia to be approaching what occurs in Europe

CC
July 02, 2025

Actually I was wrong. England is only 16% of the size of NSW in square km !

GeorgeB
July 02, 2025

"Can't compare Australia to those countries"

Its true that Australia is a lot bigger than France or the UK, trouble is everybody wants to live in or near the capital cities which is where competition drives up prices for not dissimilar reasons.

Consider the following fun facts:
more than 2/3 of Australia's population resides in its eight capital cities: Sydney, Melbourne, Brisbane, Perth, Adelaide, Hobart, Darwin, and Canberra;
90% of Australians live on just 0.22% of the country's land and not many want to live in the other 99.78%;
87% reside within 50 kilometers of the coast;
Moreover, a significant portion of Australia's population GROWTH is concentrated in capital cities. In the 2022–23 period, over 82% of the nation's population increase occurred in these urban centers.

So maybe the comparison is not as invalid as it may first appear.

Greg Hollands
June 26, 2025

Just look at the dining and discretionary expenditure percentages in each age bracket. The older you get - the less you spend on nothing! Perhaps we could learn from that. No real analysis of HECS debt issue. If you don't have a repayment plan, and only pay off what the bare minimum is, then what a surprise that the balance due is higher than you think. Fundamentals of finance/economics says early repayment of principal is a ket=y factor in this. Why is this so hard?

Roger
June 30, 2025

My guess is the HELP debt will be fully “paid off” after the next few election campaigns.

Steve
June 29, 2025

The under 44s understand this only too well. Why Labor was re-elected - they need hand outs just to pay the bills. Interestly, the Russian Duma is looking at paying mortgages for under 26 year olds with children under 6 yrs of age.
https://wavellroom.com/2024/06/20/russias-collapsing-housing-market/

Peter Taylor
June 29, 2025

Uncharted waters. The fuel of cheap and freely available debt has kept asset prices spiraling upward. I assume the goverment debt of more than 1 trillion and extensive immigration programme has filled the vacuum caused by onsumer spending now servicing higher debt and rent. With China and the USA choking on debt it will be interesting to see how much longer the tool of debt can be applied to keep the party going. With customer service in a race to the bottom a recession will be almost welcome to reset the economy.

Sluggish wage growth is a result of policies to disrupt unions. Love or hate them they under pinned wage growth. Immigration has also assisted in low wage growth as for example Indian truck drivers are on fixed rate contracts and don't enjoy penalty rates


Leave a Comment:

RELATED ARTICLES

Preserving wealth through generations is hard

Three considerations before reshaping your legacy plan

Post-Budget blues? A knee jerk won’t help

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.