Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 589

Where is peak ETF?

The market share of ETFs and index trackers keeps rising and with it concerns about reduced market efficiency. In theory, if everyone would simply track an index, new information would no longer be reflected in share prices, and it would become highly profitable to be active and short stocks with negative news flow while buying stocks with positive news flow. This theoretical argument shows that there should be an equilibrium between index funds and active investors or that markets stop working. But where that equilibrium is, is anyone’s guess.

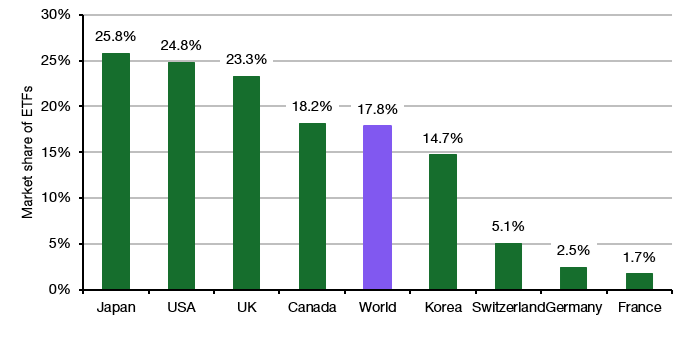
If we look at the latest figures from the Investment Company Institute about ETF market share in different countries (note this is across stocks, bonds, real estate, and commodities, so the numbers are lower than equity markets alone) we can see that in Anglo-Saxon countries, ETFs and index trackers typically have a much higher share than in continental Europe. Japan and South Korea seem to follow more the US and UK example, which is why we should consider Germany, France, or Switzerland outliers (there is a future post in that statistic somewhere).

Market share of ETFs across all major asset classes
Source: ICI, The Investment Association

The question is whether the market share of 15-25% reached by index trackers today is the peak. I doubt it and I expect index trackers to continue to gain share for many years to come.

But there are also increasing signs that with the rising share of index trackers, markets are becoming less efficient, particularly in the large-cap space.

Theresa Hambacher reviewed the last 20 years of research on index funds to see if index funds really reduce market efficiency and if active managers can drive markets back toward efficiency if too many investors switch to index trackers.

Her literature review concludes that the majority of studies show that the rise of index investing creates an ‘index inclusion effect’. Historically, this index inclusion effect meant a price jump in stocks that are newly included in an index and a drop for stocks that are excluded. But this price impact has declined significantly and all but disappeared in the US.

Nowadays, the index inclusion effect is more related to other metrics, most notably an increase in liquidity in stocks in an index. With this increase in liquidity also comes an increase in investor attention and a somewhat higher valuation. The increase in investor attention leads to higher institutional ownership, higher analyst coverage, and increased media coverage. But it also has other, more material effects. Most notably, increased liquidity and higher valuations reduce the cost of capital for both debt and equity capital and thus give index constituents an advantage over smaller stocks that are not part of the index.

On the other hand, there is ample evidence that market efficiency and price discovery decline if index funds capture a larger share of the market. This should in principle give an opening for active managers, who on average increase price efficiency and take advantage of market mispricing.

The reality, however, is more complex. Market efficiency is driven by a whole lot of factors, not just the share of index funds. This means that if active funds capture market inefficiencies and make markets more efficient, this does not drive investors away from index funds. Instead, markets may adjust in such a way as to become more efficient without reducing the market share of index funds. Plus, market efficiency is not the only driver of index fund market share. Hence, active funds may outperform index funds and improve market efficiency but get no reward in the form of higher market share. Instead, index fund investors may simply free-ride on the work of active fund managers.

These two effects are not new. They have been known for some time. But taken together they imply that the market share for index trackers may well increase past the optimal level and stay there for many, many years. And there seems very little if anything that active managers can do to reverse that. Hence, we do not know where peak ETF is, and while active managers provide a valuable service in making markets more efficient, they are not necessarily rewarded for it by capturing a larger share of investor assets.


Joachim Klement is an investment strategist based in London. This article contains the opinion of the author. As such, it should not be construed as investment advice, nor do the opinions expressed necessarily reflect the views of the author’s employer. Republished with permission from Klement on Investing.


  •   4 December 2024
  • 3
  •      
  •   

RELATED ARTICLES

Are markets broken?

The challenges of building a lazy portfolio

Four options for an income investor’s next dollar

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.