Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 406

Why does Australia’s skewed stock market underperform?

Australia’s mix of industries in its economy is broadly similar to all advanced economies. It is dominated by the fast-growing information and financial sectors (quaternary) as well as health, hospitality, culture and other service themes (quinary), as we see below.
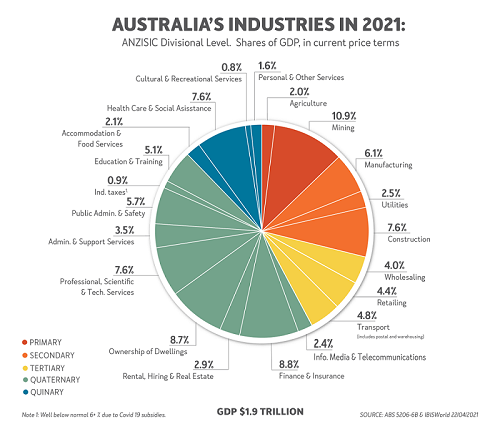
Indeed, these two sectors, mainly growing fast in the post-industrial age since the mid-1960s, now account for almost 60% of our GDP.

Agriculture is tiny but mining stands out

Agriculture is a fraction of the importance it had in the 1960s and is nearly as tiny a share as the USA’s 1% of their GDP, such has been the increasing capital-intensity of agriculture that has displaced its millenniums-long labour-intensity.

But our mining industry stands out with over 10% of our GDP compared with other developed economies where this industry is a quarter or less of that importance. And it is reflected in our exports where over half our half our $400+ billion are minerals. More if downstream manufactures are added.

Stock market weightings, Australia v US

Which leads to our industry shares in the stock market, which is skewed both by minerals and financial services. As shown in the exhibit below, these two industry divisions account for a whopping 55% of the ASX's total market capitalisation.

This mix stands in vivid contrast to that of the USA, where these two divisions account for around 17% (a sixth) compared with Australia’s well over a half.
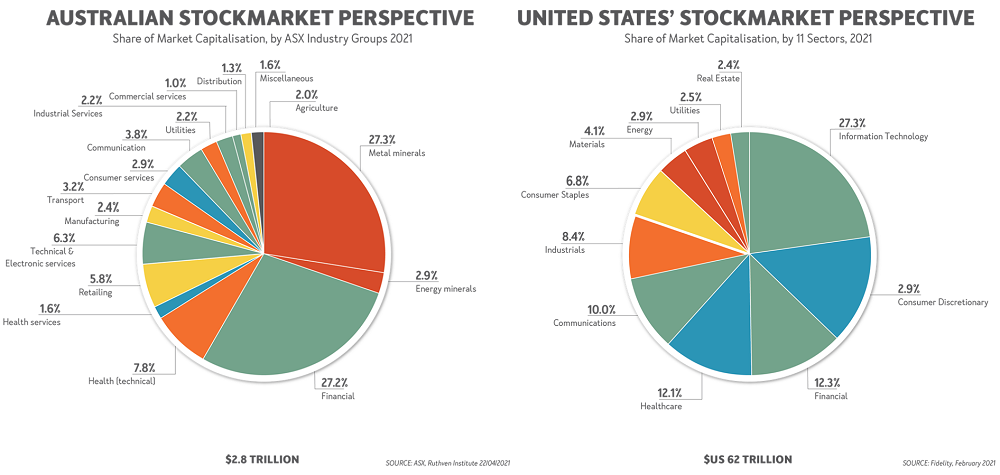
The USA has a stock market much more in tune with the new Infotronics Age of services, information and communication technologies (ICT) that displaced the goods industries and utilities of the Industrial Age up to the mid- 1960s. Their information technology sector (23% of the market capitalisation) rivals our mining industry for relative size. Then add the communications sector (10%) and ICT in total is a third of the market. It is bigger than either our minerals sector or financial services sector.

But does that explain our underperformance?

Does our skew to minerals and financial services explain why our All Ords has underperformed both the Dow Jones and NASDAQ for over 30 years and been left in their wake in the last 10 years?

No, that’s not the reason: profitability and wealth creation (dividends and share price growth) are independent of the industry. Any industry can have players with world best practice (WBL) performance. We have WBP performers in all our 19 industry divisions (as described in the first exhibit on our industry mix). As does the USA and most other advanced economies.

Other explanations often used are equally untrue, including: population size, fewer hi-tech companies, distance from markets, corporate tax regime and others.

Why are Australian companies not more profitable?

About one in 10 Australian companies achieve WBP profitability over 5-year periods while four in 10 companies do so in the USA.

The real reasons why we are lagging are more fundamental. We break too many of the keys to success rules and the most frequently breached are shown in the table below. We have to get smarter and understand strategic planning much better than we currently do.
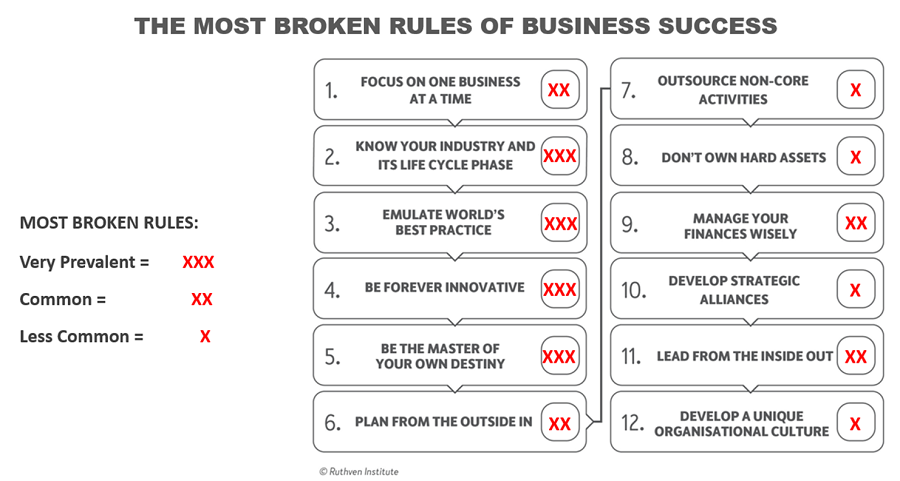
 

Phil Ruthven AO is Founder of the Ruthven Institute and Founder of IBISWorld. The Ruthven Institute was created to help any business that wants to emulate world best performance and profitability using the Golden Rules of Success, based on over 45 years of corporate and industry analyses and strategy work. The Ruthven Institute is happy to provide a fuller explanation of these 12 Golden Rules.


  •   5 May 2021
  • 4
  •      
  •   
4 Comments
Jennifer J
May 05, 2021

We're lucky when all we do is dig up rocks, grow stuff and provide services to others. The US is 27% IT and we are always criticising them.

Dane
May 06, 2021

It's mind boggling that investors can have over half their equity exposure in a skewed market that represents 2-3% of the investable universe. 'Home bias' on steroids. This article is quite revealing. Shows there is some work to do if we wish to become a dynamic economy and produce more national champions that compete on a global stage. What always stands out to me is that if you compare the top 20 stocks on the ASX there has been almost no change for decades, save for a few buy-now-pay later stonks. Whereas the US market has completely evolved.

john
May 07, 2021

It doesn't matter if you only have equity in 0.1% of "the investable universe", so long as it performs, and the ASX20 certainly does. Not so much as the US in the last decade, but the comparison is complex, eg. the ASX pays higher dividends [which can be re-invested more profitably by an individual than automatic reinvestment into their company of origin], and their mostly fully franked. Ashley Owen's articles in Firstlinks [Nov & Dec 2014] and ensuing comments discusses it all in more detail. The fact that the ASX20 stocks 'haven't changed for decades' exemplifies the simplicity of the strategy, most years they churn out some billion dollar profit, and you don't need to worry about currency issues, higher brokerage, fees to advisors who want you to invest in the whole universe and beyond. But this is not what the article is about.

Angus
May 08, 2021

Did we establish there is an underperformance and the size and duration of it? I was hoping to learn something. This is just an opinion piece.


Leave a Comment:

RELATED ARTICLES

In a short-term world, take a longer-term view

Why Australian shares are falling behind the world

The next phase of Australian equity leadership

banner

Most viewed in recent weeks

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.