Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 249

$1 million v $500,000 and accepting a pension

The article on why $1 million is always superior to $500,000 despite the potential loss of franking credits and age pension attracted many worthy comments. A reader, John Hyslop, asked about self-funding a retirement and staying off the age pension. John asked:

“This is a powerful analysis with great supporting graphics. Could you please run some numbers on two other couples?

Let’s use the same basic assumptions as in your article but with a different mindset. The couples have always been self-reliant. They realise that they have been fortunate to save well, with generous taxpayer help in tax concessions, and essentially tax-free retirement. They are concerned that coming generations are being asked to fund a great lifestyle.

They aim to refrain from being on the age pension for as long as possible can. They realise that they can live a good life on $50k p.a. They will avoid major house extensions or ‘unnecessary’ spending simply to qualify for the age pension. Although being forced to make annual withdrawals from their SMSF, they could build up another investment reserve fund outside super using any surpluses.

Could you re-run the numbers to assess when they ‘have to’ go on the pension and with the possibility of being able to leave some inheritance for the kids? I believe the system is unsustainable and is likely to produce inter-generational conflict.”

Hi John

Under age pension rules, a couple can have a home of unlimited value and receive a full age pension if their other assets are worth less than $380,500. The pension cuts out when assets exceed $837,000.

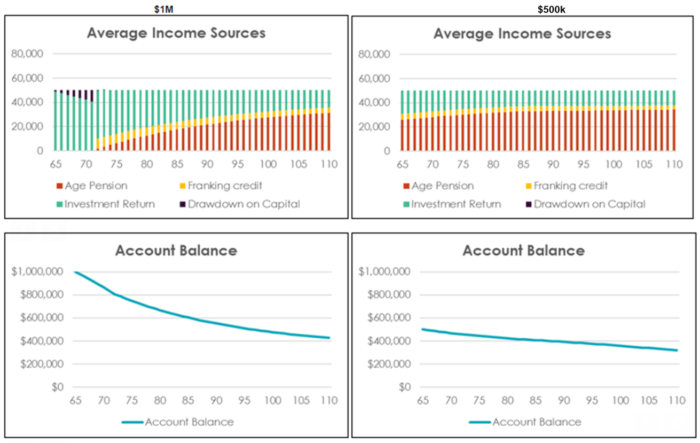
The couple with $500,000 will be eligible for a part-pension from the start which will make up half their annual income. The couple with $1,000,000 will start to receive a part-pension when they reach age 72 after drawing down some of their capital. Using the minimum drawdown rule would not impact the period until they become eligible for age pension because from age 65 to 75, the minimum drawdown rate is 5%, the same as the investment return.

The charts below show:

  1. Both couples will go on the age pension, unless they feel strongly that they should not be a ‘burden’ on the budget. This is typical of most retirees as even with compulsory superannuation since 1992, it is expected that 70% of Australians of eligibility age will still be drawing a part-pension by 2055 (see 2015 Intergenerational Report).
  2. When the Smiths become eligible for the age pension, they also receive their franking refunds (assuming not in an SMSF), and no longer need to drawdown capital to spend $50,000 a year.
  3. Due to the more modest lifestyle, neither couple runs out of other capital, so there will always be something in reserve for unexpected costs or a bequest.

It’s especially interesting to contrast the consequences of living on $50,000 versus $80,000 (in the previous article), with both couples trading off greater financial security for a lesser lifestyle, assuming money delivers lifestyle benefits.

Smiths ($1 million) versus Joneses ($500,000) based on $50,000 annual expenditure
Graham Hand is Managing Editor of Cuffelinks. My thanks to quantitative analyst Estelle Liu for assisting with the calculations.


  •   19 April 2018
  • 8
  •      
  •   
8 Comments
Bill Buttler
April 19, 2018

Thanks for this article. It's great to read something aimed at the man in the street for a change. $500k is a realistic target for most employed Australians, who cannot hope for the luxury of being able to live off income in perpetuity. However, there is a major qualification in the shape of the planning risk of relying on the continuation of current Age Pension eligibility rules.

Mark Reynolds
April 19, 2018

Is it just me, or is the assumption about franking credits "becoming available again once on the aged pension:, an acceptance by the author that the current government is doomed, and labor is set to win the next Federal election?

Neil
April 21, 2018

"When the Smiths become eligible for the age pension, they also receive their franking refunds (assuming not in an SMSF),"? How So? There is no return of franking credits other than to offset tax liability.

Neil
April 21, 2018

Just to clarify, my previous comment is assuming the ALP form government and get its changes passed. My understanding might be wrong; that a person who was receiving an Age pension on the day the changes were announced keeps ALL franking credits. If one BECOMES an Ap after that one does not.

Laine
April 22, 2018

Neil

Any aged pensioner will still receive the full franking credits on their individual income with any excess refunded as cash. This is regardless of when they first became (or become) an aged pensioner.

Any aged pensioner who was a pensioner as at 28 March this year will also continue to receive the excess franking credits within their SMSF.

If you were not a pensioner at that date but later become one, you will receive the refund of unused franking on your individual income but not within your SMSF.

All this applies to a change in the system which is not yet law and may never become law.

There is also talk of them backdating their proposed changes to capital gains tax so the new rate affects any property bought from 1 July 2017.

Does this mean theat if you buy in 2017 and sell in 2018 after holding for more than one year and the ALP form govt in 2019 they can come back and charge you extra tax ???

How can anyone plan anything with these sorts of ad hoc and back dated policies.

Graham
April 22, 2018

Hi Neil, assuming Labor is elected and can pass its plans, they announced a 'pensioner guarantee' that anyone on an age or disability pension will receive excess franking credits, including future pensioners. The date you mention (28 March 2018) specifically applies to SMSFs, where the SMSF must have had at least one member on a pension on that date to receive the franking credit refund. Disadvantages SMSFs. 'Pensioner' in this context does not mean a person with an SMSF drawing a pension from their fund.

Graham Hand
April 13, 2019

Hi KW, Thanks for your comment. Please note, we are not licensed to give personal financial advice, and we don't know your full circumstances.

We also do not know the credentials of people who respond. They might not be properly qualified.

A better approach would be for you to contact a good financial adviser.

Dudley
April 13, 2019

Until the home owning couple's capital reduces to less than the asset test $840,000 limit the comparison is between the risk free Age Pension and a risk free investment.

A home owning Age Pensioner couple with $0 capital receives a risk free $36,000 per year indexed to the highest of Wage, Consumer Price or Beneficiary Living Cost inflation.

A home owning Self Funded couple with $1,000,000 capital earning 1% real risk free has an income of $10,000 per year. To receive risk free $36,000 per year they need $3,600,000 invested at 1% real.


Leave a Comment:

RELATED ARTICLES

Why spending more in early retirement can improve lifetime income

Super is delivering for people about to retire

$1 million is never worth less than $500,000

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.