Mined gold production reached a record high in 2025, based on our 2025 Gold Demand Trends report (Chart 1). Global miners produced 3,672 tonnes of gold, a modest year-on-year increase of 1% and the highest in our data series – albeit this may be subject to revisions when more data becomes available.[1] And we expect mined gold production to further increase in 2026 – at a mild pace – as operations resume at two major mines.
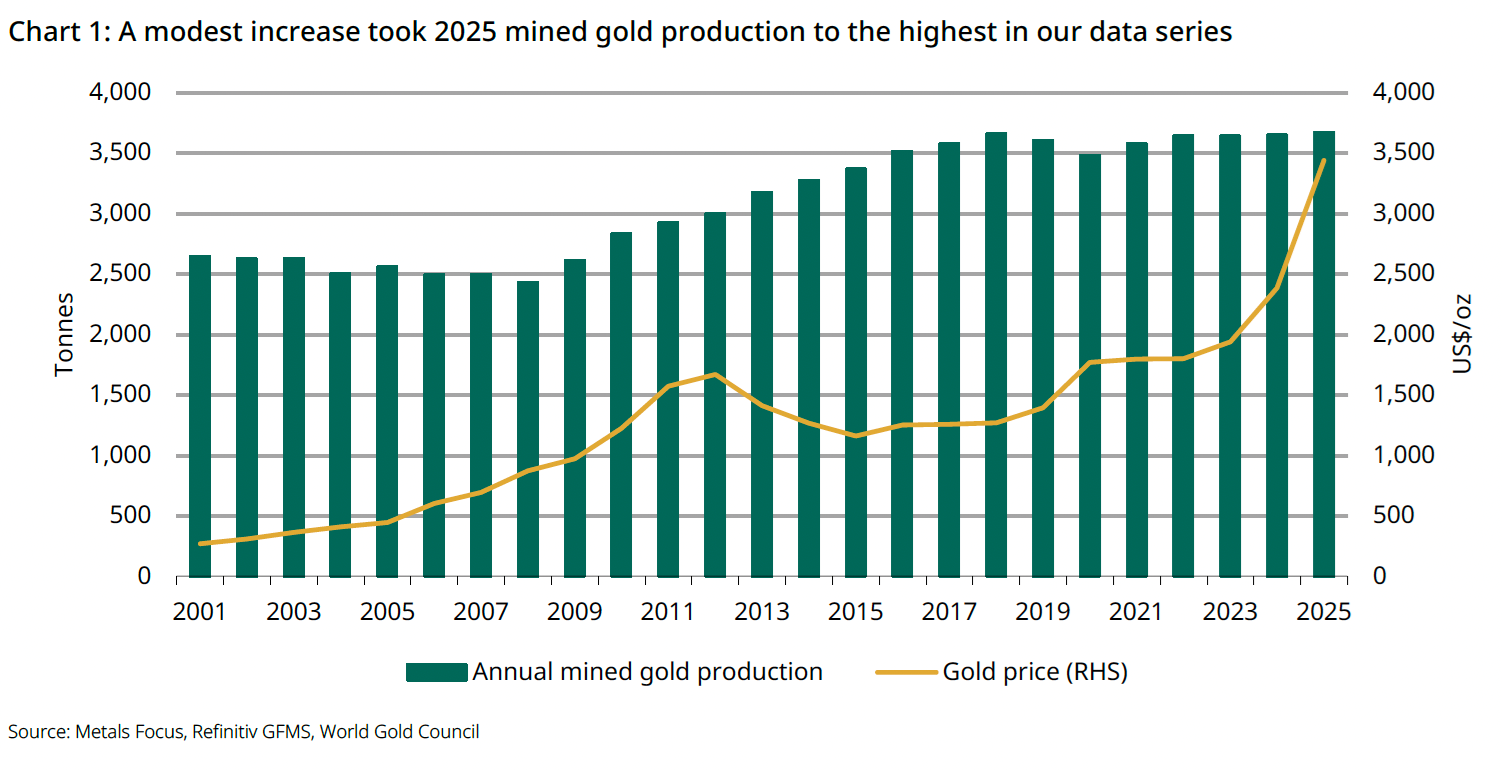
In a previous article, we explained why gold mine production typically lags the gold price and we discussed the possibility that production will plateau over the coming years. A key reason for this is that the new gold mining projects are getting harder to discover, due mainly to geopolitical instability in many prospective regions; lengthening development timelines amid protracted permitting processes for environmental and social licenses; rising capital costs; and complicated project financing in remote areas.
Based on the annual reports of major gold mining companies, the 2026 production outlook is generally cautious – most forecast declines compared to 2025. Without more discoveries, current reserves naturally deplete – perhaps at a faster pace should the gold price keep rising – which could possibly encourage production to accelerate. This has raised concerns from investors:
- Are we approaching a structural shortage of mineable gold?
- If not, when can a meaningful supply response be expected?
- Should any major discoveries be found, will they suppress the gold price?
- Could gold supply be manipulated?
In this update, we aim to provide some guidance for investors regarding these questions.
Will we eventually run out of gold?
There are two parts related to this question – the broader gold supply and mined production. Our answer to both is: not likely.
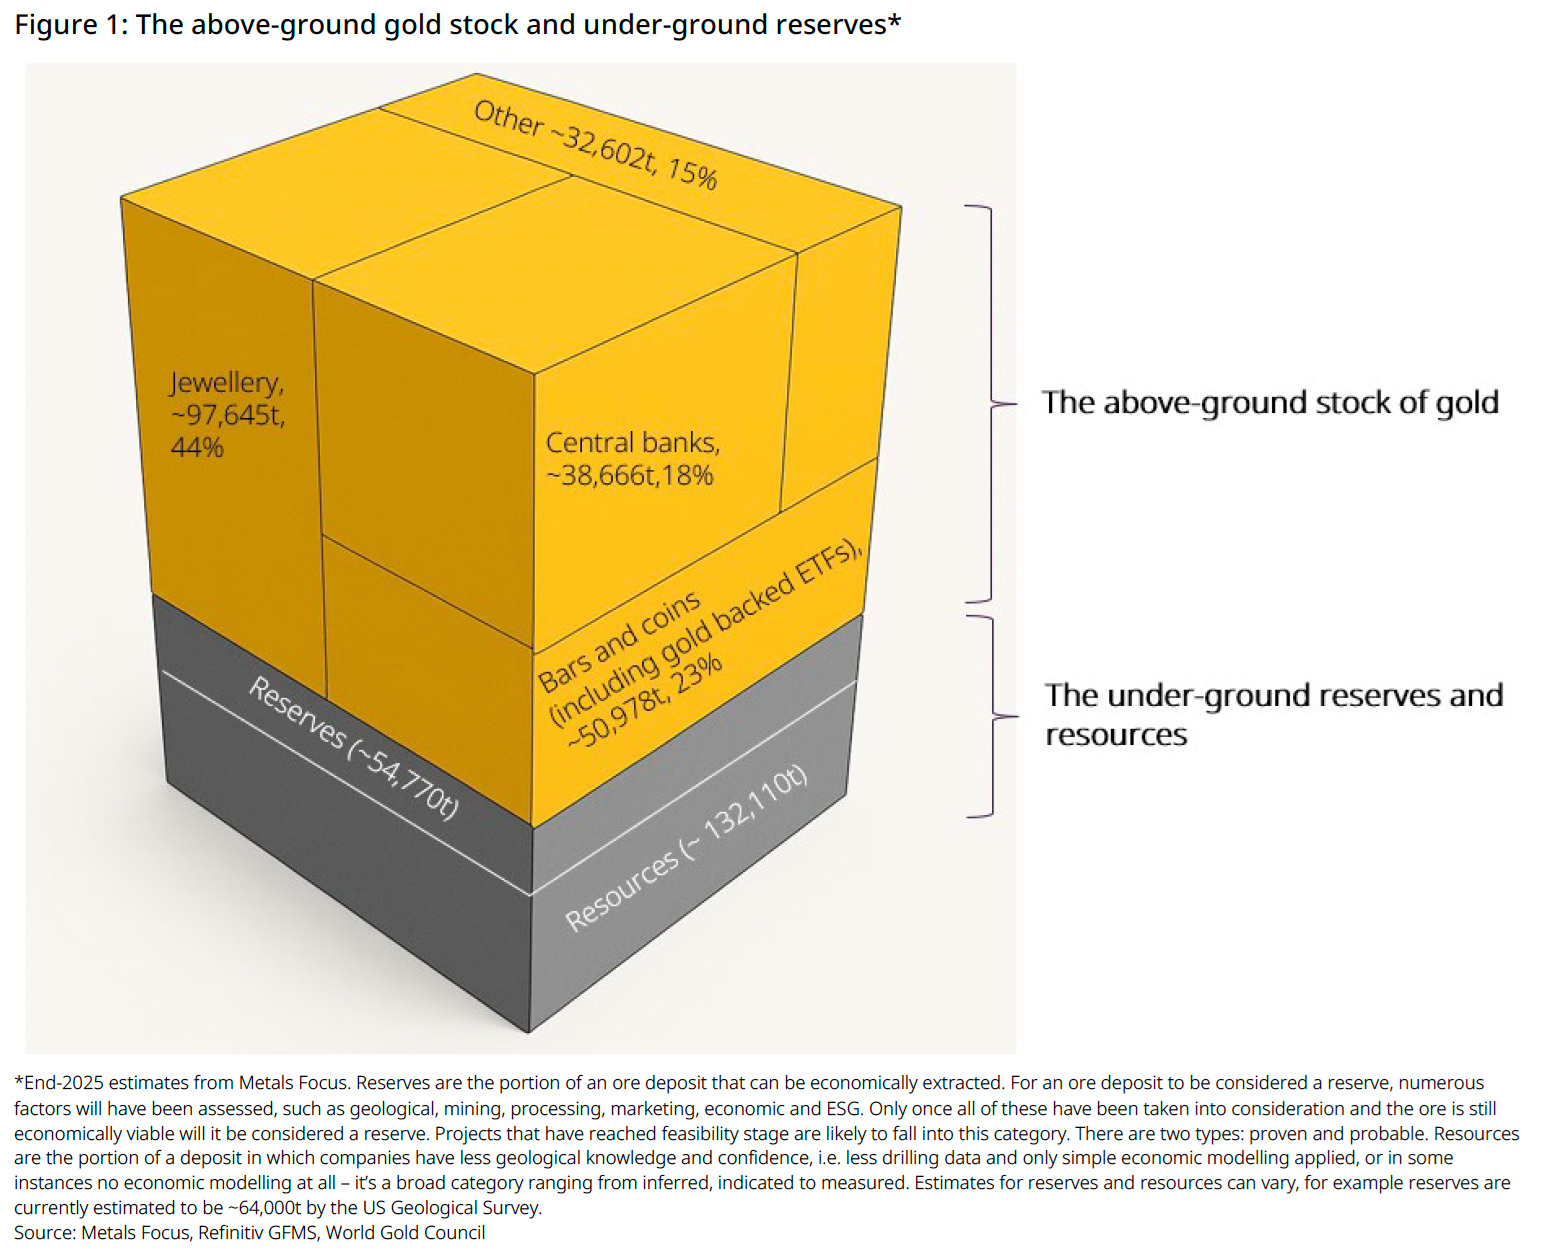
First, we are not likely to run out of gold supply. There are two major parts to supply: recycled gold and mined gold. While mined gold may be plateauing as noted previously, recycled gold supply comes from various sectors. As shown in Figure 1 below, total above-ground gold amounts to 219,891 tonnes. And because gold is virtually indestructible, almost all of it is available to come back to the market under certain market conditions. For instance, when the gold price is high, it may trigger sellbacks of gold jewellery from consumers and more industrial recycling – factors that are far more responsive to price than mined gold production.
Second, we are not likely to run out of gold to mine either.
Metals Focus estimates that there were 54,770 tonnes of gold reserves by the end of 2025, i.e. the portion of an ore deposit that can be economically extracted under conditions as of 2025, whereas the US Geological Survey (USGS) data estimates gold reserves to be around 64,000 tonnes.
And resources – the total potential of gold deposits based on geological evidence and sampling, including the part that is economically minable and the part that is not – are estimated to be 132,110 tonnes, based on data from Metals Focus.
There is a common misconception that proven gold reserves can only last ~15 years at the 2025 rate of production. But it is important to note that estimates of below-ground reserves have remained stable for decades even as gold is being continually mined out.
This stability is explained by several factors, which will likely continue:
- Lower-grade deposits once unprofitable become economically viable – in other words, they move from resources to reserves as the gold price increases
- More gold is discovered, albeit at a slower pace. When a gold deposit is discovered, sufficient reserves are drilled out to justify the project construction.[2] But as some of the deposit depletes, further exploration often takes place, keeping total resources relatively stable.
- Often when a mine is built and brought into production, exploration geologists start to look for near-to-mine resources (often small deposits, sometimes known as satellite deposits), that can supplement reserves.
Also, with technology advancing, better geological modelling and deeper underground mining becoming more effective, making new discoveries more viable and extending current usable supply. Theoretically, gold exists deep under earth’s crust[3] and even under oceans,[4] although these are not currently viable due to technological constraints or cost considerations and, in some case, due to ESG concerns.[5]
In conclusion, while there is a slim possibility that we run out of ‘easy’ and ‘cheap’ gold to mine – if all discoveries stopped, technological advancement and a price that is high enough could see gold extracted from previously unfeasible supply sources.
How would sizeable changes in mined gold production impact the gold price?
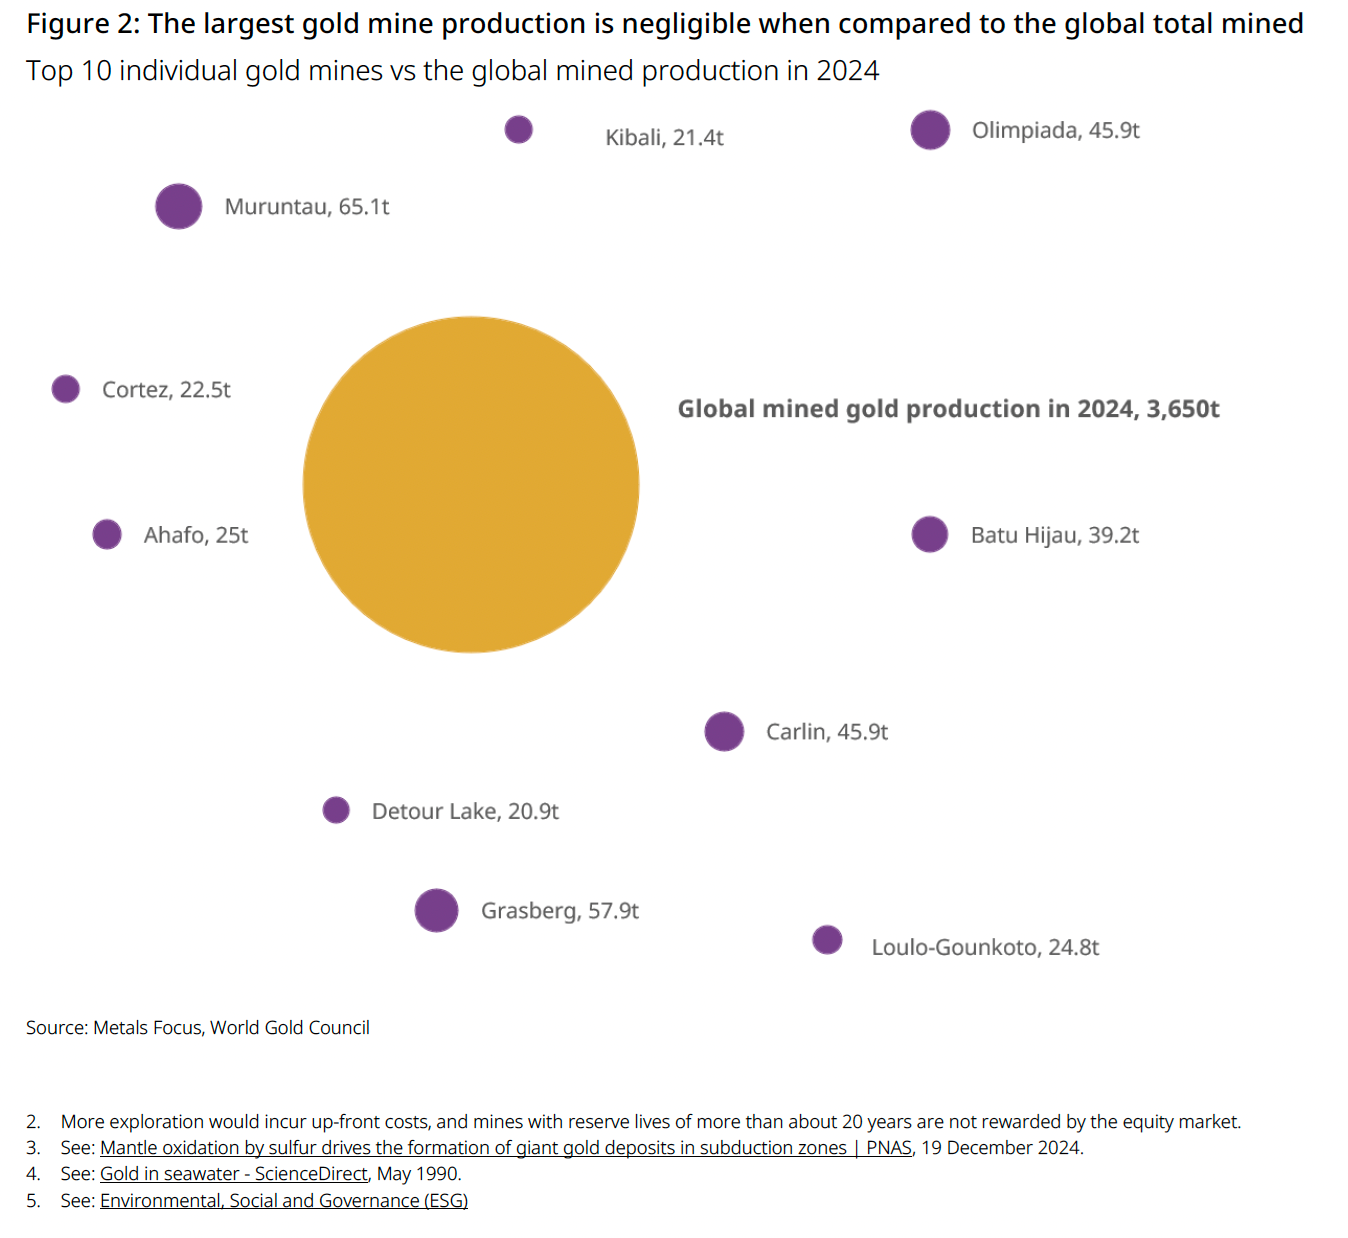
Changes to gold production are normally only reflected in changes to the price over the long term; any immediate impact will likely be mild. First, any new discovery is unlikely to be large enough to move the needle. Based on data from Metals Focus, the Muruntau mine in Uzbekistan was the largest in the world in 2024, producing 65 tonnes of gold during that year. But compared to the world total of 3,650 tonnes, it is small (Figure 2). Second, as we previously noted, any new discovery is likely to take more than a decade to be explored, permitted, built and ramped up to full production. The market will have had time to absorb the news and may gradually price in such expectations, making little impact in the short term.
From a modelling perspective, holding all else constant, QaurumSM suggests that every ~25 tonne gold supply increase/decrease leads to an approximate 1% decline/rise in the gold price during the same period. But both our model and the real world function in a more complicated way. For instance, any decline in the gold price caused by a rise in mine production may lift demand for gold jewellery and industrial use, offsetting the negative price impact. Furthermore, recycled gold supply may also taper off as the gold price declines, counteracting the increase in mine production. Lastly, changes that feed through each segment may not happen during the same period, further complicating the impact. It is important to note that it is the overall supply and demand conditions that collectively impact the gold price.
Is it possible for gold producers to collectively impact mined gold supply?
The answer is “probably not possible in the real world”.
First, gold supply comes from various sources, including mine production and recycling. If we assume that gold miners collectively limit production to drive up the price, recycled gold supply is likely to rise in response to the higher gold price as it often does, potentially inserting pressure on the price. With above-ground gold holdings at 219,891 tonnes, the potential for recycled gold supply is vast – although not all of it can be mobilised quickly – compared to mined gold supply.
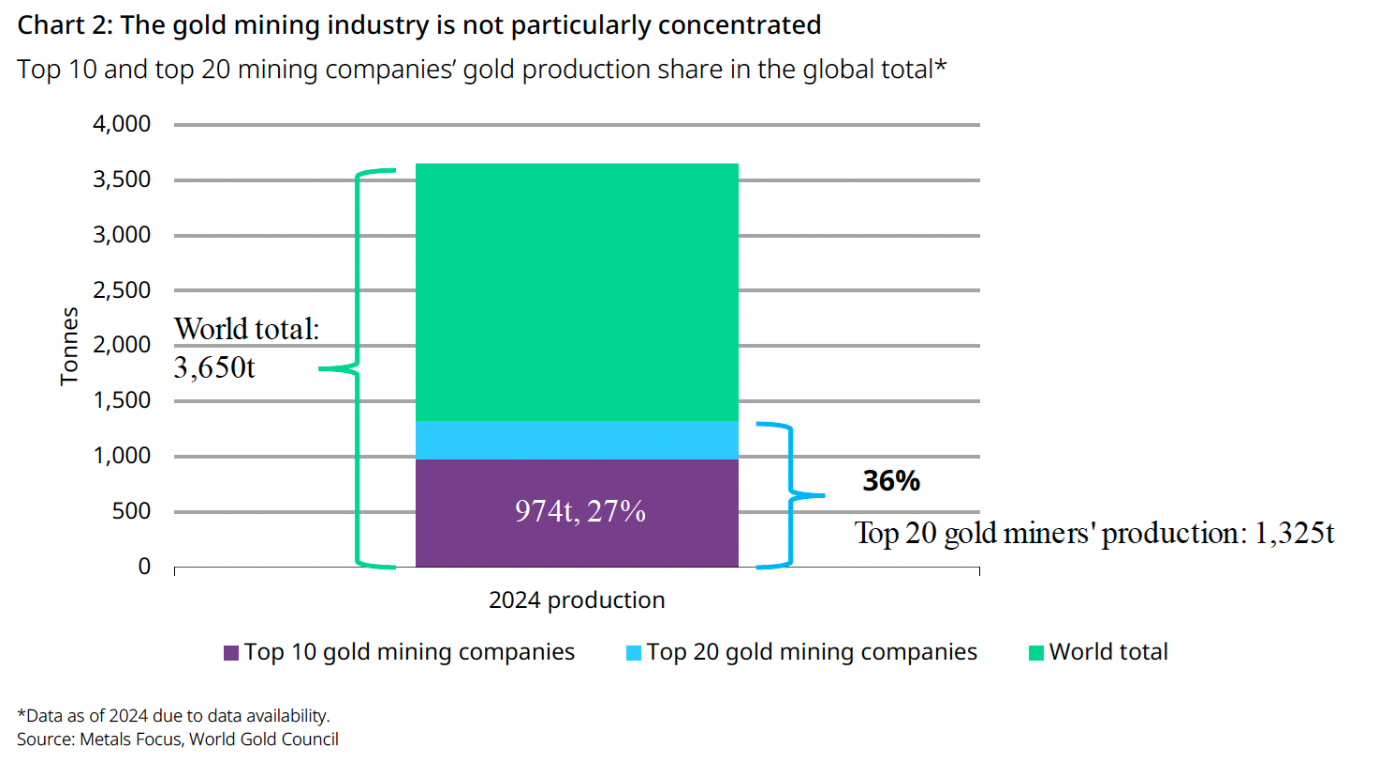
Second, the gold mining industry is globally diverse and its concentration ratio is low. The top ten gold producers accounted for 27% of total global production. It would be difficult to persuade all gold miners to act collectively, not to mention artisanal and small-scale gold mining (ASGM) supply, which accounted for around 20% of the global total in 2024, based on our estimate[6]; these ASGM sources are even less likely to be responsive to attempts to constrain production. Lastly, monopolistic actions, such as coordinating production cuts across the gold industry, are illegal in many jurisdictions.[7]
Summary
Despite higher gold prices, mined gold production has grown only modestly, raising questions about long-term sustainability. While the risk that we run out of ‘easy’ reserves appears limited, technological advances and a gold price that is high enough should help unlock currently uneconomic supply. And sizeable above-ground stocks – though not all readily accessible – can supplement mine output when conditions allow, supporting overall supply stability.
Even when large projects come online, their near-term price impact is likely limited. Our model suggests a 25 tonne change in supply translates into roughly a 1% price move, all else equal, but real-world dynamics are far more complex. Lastly, fragmented production, artisanal mining, and recycled supply make coordinated supply responses unlikely, reinforcing gold’s long-term market stability.
[1] We published our FY 2025 and Q4 data ahead of most companies’ quarterly reports, so the final numbers will differ from our estimates. Revisions to our mine supply dataset are usually concentrated in recent quarters, but revised mine production data released by the government of Indonesia saw a 7t and 5t increase in estimates for mine production as far back as 2015 and 2018, respectively.
[2] More exploration would incur up-front costs, and mines with reserve lives of more than about 20 years are not rewarded by the equity market.
[3] See: Mantle oxidation by sulfur drives the formation of giant gold deposits in subduction zones | PNAS, 19 December 2024.
[4] See: Gold in seawater - ScienceDirect, May 1990.
[5] See: Environmental, Social and Governance (ESG)
[6] See: Understanding ASGM: A Vital Segment of the Gold Sector | World Gold Council, 27 June 2025.
[7] See: The Antitrust Laws | Federal Trade Commission; International Competition Law: A Global Perspective for Multinational Corporations - Michael Edwards | Commercial Corporate Solicitor
John Reade is a Senior Market Strategist, and Ray Jia is Research Head APAC ex-India at World Gold Council, a sponsor of Firstlinks. This article is for general informational and educational purposes only and does not amount to direct or indirect investment advice or assistance. You should consult with your professional advisers regarding any such product or service, take into account your individual financial needs and circumstances and carefully consider the risks associated with any investment decision.
For more articles and papers from World Gold Council, please click here.