Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 517

Can quantitative tightening help tame inflation?

The parallels between today’s inflation and the inflationary period of the 1970s are stark.

Australia's inflation-stricken period of today was largely brought about by a rapid increase in the money-supply, in tandem with significant government spending to combat Covid.

In many respects, it mirrors the massive fiscal spending in the mid-70s which occurred at a time when loose monetary policy was stoking inflation.

Similarly, the so-called Great Inflation period during the 1970s in the US was spurred by expansionary monetary policies pursuing full employment, at a time of profligate government spending on the Vietnam war and social policies.

The Great Inflation only began to retreat when Paul Volcker became the Fed chief in 1979, and commenced aggressive monetary policy tightening by raising interest rates and curbing the money supply.

Money supply remains elevated

Today the response to inflation in advanced economies has seen rapid interest rate rises, but the money supply thus far has remained elevated by pre-Covid standards, particularly here in Australia, where the M1 money supply measure sat at $1,632 billion at the end of April, up more than 50% on pre-pandemic levels (see chart).

The increased money supply coincided with the RBA’s Quantitative Easing (QE) program which saw it accumulate some $330 billion of Australian government and semi-government bonds, expanding its balance sheet in the process (again, see chart). So would not reversing that QE, known as Quantitative Tightening (QT), have the opposite effect in sucking money out of the system and subduing inflationary pressures?
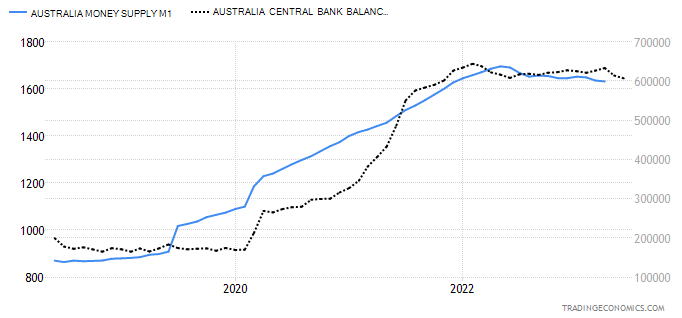
QE recall, involves the RBA purchasing longer-term government bonds to increase bank reserves and encourage lending, which in turn increases the money supply. QE therefore aims to lower borrowing costs and stimulate investment, a consequence of which could be higher inflation.

Quantitative tightening

The exact reversal of QE is known as active QT. This occurs when the central bank sells its balance sheet assets back into the secondary market before they mature, reducing its balance sheet rapidly, and taking base money out of the system.

Instead the RBA has chosen to implement passive QT, whereby it allows its bond holdings to mature over time and to not reinvest the proceeds. In this way, the central bank balance sheet contracts more slowly.

Specifically, when government bonds held by the central bank mature, deposits held at the central bank by Treasury fall by the same amount to pay for the maturity. Treasury issues new debt to the market to replace its central bank deposits, and banks buy the securities reducing their reserves held as liabilities by the central bank. The central bank balance sheet therefore contracts by the amount of debt maturing, and the reversal of QE is complete.

The RBA said in its May board minutes that it had reviewed its “approach to reducing its holdings of government bonds”. And that “the strategy was to hold these bonds until maturity rather than selling them prior to that”. Members agreed that that approach “remained appropriate for the time being”.

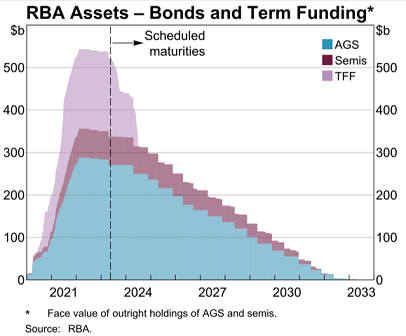
This passive approach recognised that the RBA balance sheet was “already set to decline rapidly given the maturity of funding under the Term Funding Facility” (TFF). But it did not rule out actively offloading its bond holdings in the future, agreeing that “it was appropriate to review the current approach periodically”.

The TFF was basically low-cost funding the RBA offered to banks, fixed for three years, enabling them to on-lend that money at record low interest rates. About $190 billion was drawn down by the time the facility closed in June 2021. It basically complemented the QE program.

Below is a chart showing the projected decline in the RBA balance sheet. Note that it doesn’t return to pre-Covid levels until after 2030. Time will tell whether passive QT will draw money out of the economy fast enough to help stifle inflation.
Other RBA tools to fight inflation

While inflation is proving to be stubborn, draining money out of the system with bond holdings maturing and TFF loans being clawed back, along with the rapid interest rate increases to date, should have the desired effect eventually. And if it needs to kick up a gear, the RBA has even more deflationary levers at its disposal.

It could mandate that banks hold increased reserves, thereby reducing lending, which can restrict spending and investment, dampening inflation.

In a similar vein, it could influence stricter lending standards, preventing excessive lending and reducing inflationary pressures.

Forward guidance. In much the same way the RBA influenced aggressive bank lending by verbally communicating that interest rates were likely to stay near zero until at least 2024, it could put that practice in reverse to influence expectations and put downward pressure on inflation.

It could intervene in currency markets. All else being equal, a stronger currency could weaken export competitiveness, lowering export demand and possibly inflation.

The extent to which the RBA employs these tools, if at all, can vary depending on economic conditions, bearing in mind that it must promote overall economic stability. Meanwhile, the interest rate lever will remain the headline act until such time that the inflation beast has been tamed.


Tony Dillon is a freelance writer and former actuary. This article is general information and does not consider the circumstances of any investor.


  •   12 July 2023
  • 2
  •      
  •   
2 Comments
Tim Farrelly
July 13, 2023

I think the best clue to the likely impact of QT is to look at the impact of QE on inflation in Japan since 2000, Europe and the US since 2010. Lots of QE, hardly any inflation. If that is any guide, and I think it is, the impact of QE on inflation is likely to be very modest.

Warren Bird
July 13, 2023

One of the great misunderstandings of monetary economics since the GFC is that QE is "printing money". It's not. It may or may not lead to higher money supply growth, but doesn't automatically produce it.

Related to that is the misconception that QE must create inflation. It might or might not, depending on what actually happens to money supply growth.

Which ultimately depends on the response of demand growth in the economy to easy monetary policy and other macroeconomic policies.

Central banks don't create money. Banks and governments do that. Banks do it by writing loans, but that's always in response to demand for credit which reflects underlying demand in the economy.
Governments do it by running budget deficits while QE is going on, injecting cash directly into the goods and services they're spending on, using funding that hasn't ultimately come out of the banking system. (If no QE then all government bond sales take money out of the economy so don't result in "printing money".)

I'm no expert on Japan, but I don't agree that the macro outcomes in that country prove anything about the links between QE and inflation. All it proves is that Japan is a low inflation economy. Quite likely without QE it would have been a deflationary economy.

In other economies like the US, QE in 2008 and following didn't create inflation because the liquidity didn't turn into higher bank lending. They were battoning down hatches and reinvested just about everything with the Fed instead. In conjunction with fiscal stimulus, bail outs etc this prevented what was shaping up as a massive monetary contraction and helped produce the great recession instead of a depression, so I think QE worked and played a role in averting the worst of the GFC. But it was never going to create inflation under those circumstances.

2020 was different. Fears of a pandemic-led downturn were averted by lots of factors including fiscal responses. EG in Australia, Job Keeper meant that many who would have lost their jobs and income didn't. That meant that QE - which the RBA implemented for the first time - did create money growth and inflation because the banks kept lending (at low rates) and the government ran deficits that resulted in "printing money". At one point M6 was growing at 27% pa, but in trend terms it was well in double digits through 2020 and 2021.
We have had the inevitable rise in inflation that was predicted in articles published by Firstlinks in mid-2020.
QE works like all monetary policy works. It creates an environment for demand growth to happen and money to be created. But central banks have only ever been able to provide incentives or inducements to behavioural change. To what extent and in what ways behaviour changes is subject to many other factors. The horse that was led to the water may drink gallons or refuse to drink at all. But he's at the water trough and it's then his choice.


Leave a Comment:

RELATED ARTICLES

Shares rebound on hopes of war ending, but stalemate the likely outcome

Five simple reasons why Australian cash rates are highest

This 'forgotten' inflation indicator signals better times ahead

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.