Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 482

Fighting the last war

In November 1918, France was physically and mentally scarred. World War One was ending, yet the victory had come at an enormous cost. Of the 8 million Frenchmen mobilized, more than a million had died and another million were crippled. Eastern France had been almost continuously occupied by enemy forces for four years. Consequently, the country’s most advanced agricultural and industrial areas were devastated.

A big question emerged after the war: how could France best defend itself against future attack? The question took on greater urgency after the signing of the Treaty of Versailles in 1919. The treaty punished and crippled the war’s aggressor, Germany, yet France believed that the Germans had gotten off lightly and war would resume soon enough.

A safe France

After a decade-long debate, a key pillar of French defence against future attack was decided. It became known as The Maginot Line. The idea came from fortifications around Verdun which had worked well during World War One. They had held up to extensive artillery fire and suffered minimal damage.

The Maginot Line would be an extended series of large-scale buildings along the south-eastern French border. It would defend the region most vulnerable to attack. With the south-east fortified, France could focus on gathering forces in the north-east of the country, to get ready to enter, and fight in, neighbouring Belgium. Belgium was a key ally of France in 1930, when the building of the Maginot Line commenced.

Not as safe as assumed

France largely completed construction of the Maginot Line (pictured below) by 1936 and the country felt safe. After all, what worked in World War One had been extended and would shield the country from future attacks.
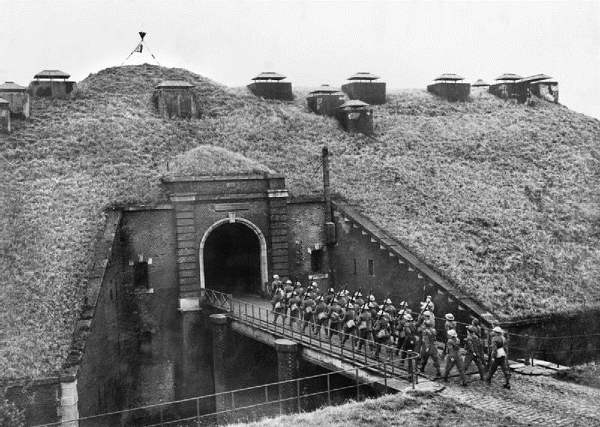
There was one problem: Germany didn’t end up attacking France via the Maginot Line. In 1940, it attacked the Netherlands, then moved through Belgium, to enter France. Germany met little resistance and France was subjected to a quick and embarrassing conquest.

After World War Two, the Maginot Line came under severe criticism both in France and abroad. In hindsight, it’s easy to pick flaws with the idea. At the time though, France thought it was learning from the recent past and applying that knowledge to the future.

Recency bias

Investors often make the same mistake that undid France. Behavioural economists call it recency or extrapolation bias. It’s a cognitive bias, or mental mistake, where investors incorrectly believe that recent events will happen again soon. Put another way, investors often overweight new events or information without looking into the objective probabilities of those events occurring in the long run.

Think of last year’s bubble price action in the likes of Bitcoin and GameStop, and how investors (or more aptly, speculators) thought the huge increases in prices for these things would continue without looking objectively at the long-term fundamentals.
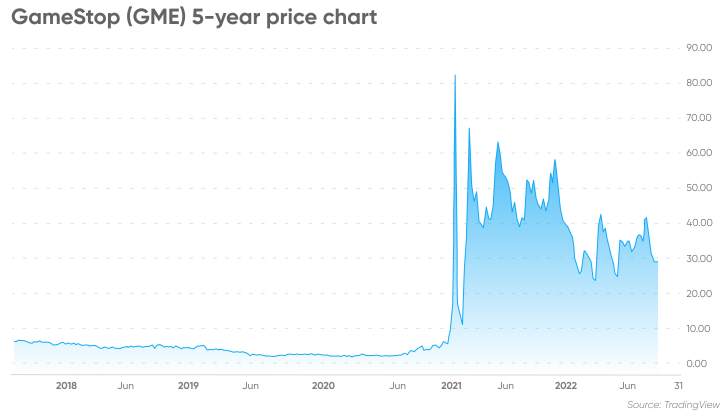
To avoid the fate of France and indeed Bitcoin and GameStop speculators, it’s worth looking at recent events which investors may need to be careful extrapolating or overweighting into the future. They include:

  • Rising interest rates though everyone expects them to remain relatively low.
  • A pullback in bond prices making them attractive versus recent history.
  • The traditional 60:40 equities/bond portfolio failing miserably this year, with calls for it to be adjusted or discarded.
  • The US$ becoming ‘king dollar’ and the pound, Euro and Yen getting pulverised.
  • Growth stocks coming back and being set for further outperformance given their superior performance since 2008.
  • Most Australian superannuation funds having outperformed their benchmarks, with expectations of more to come.
  • Venture capital and private equity continuing their ascent in the finance industry.
  • Significant government debt having not been an issue (until very recently).
  • Gold being one of the few assets to have performed well in A$ terms this year, with predictions of further outperformance going forward.
  • Volatility being back. Period.

Building a durable portfolio

How can investors reduce the likelihood of them applying recency bias to their portfolios? Perhaps it’s moving in the opposing direction? Instead of overweighting recent events; underweighting them. Instead of investing in what’s worked for the past decade; investing in what hasn’t worked.

For example, since investing in growth stocks has worked since 2008, one should take the opposite tack and invest in value stocks. The trend in growth to value has ebbed and flowed throughout history and value could make a comeback.

The problem with this contrarian approach is that though many things in markets do mean revert, they often take longer than investors think. Or they may never mean revert, as a new event may prove enduring rather than fleeting.

Instead, the best strategy for investors may be a more balanced one: to be aware of mental biases such as recency bias and build a portfolio which is neither overweight nor underweight recent events. In other words, constructing a durable portfolio of investments which will perform under most, if not all, future circumstances.


James Gruber is an Assistant Editor at Firstlinks and Morningstar.


  •   2 November 2022
  • 1
  •      
  •   
1 Comments
R S Gupta
November 08, 2022

Very good way to invest in durable portfolio


Leave a Comment:

RELATED ARTICLES

Investing is like water, but what the hell is water?

10 cognitive biases that can lead to investment mistakes (Part 2)

10 cognitive biases that can lead to investment mistakes (part 1)

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.