Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 168

Income inequality and a crumbling model for capitalism

Economic rationalism – that is, a belief in free markets, deregulation, and globalisation – has been a hallmark of progressive governments in the West since the demise of socialism. While these policies have sustained productivity and growth, the spoils have not been evenly shared as living standards in low and middle income households have stagnated in many developed countries. The median income for an American male is unchanged in real teams over four decades. The promise of open markets and capitalism has sadly failed the middle class and their dissident voice is becoming louder.

You can see a clear divergence emerging in the share of incremental growth going to labour versus capital by way of profit share in the graph below.

US labour income and profit share
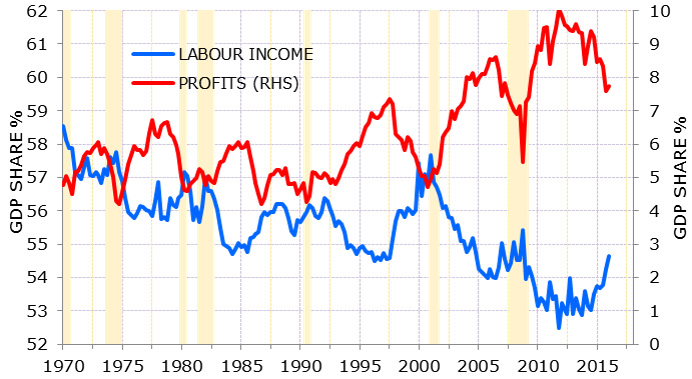
Source: Minack Advisors

Owners of capital, aka the wealthy, have benefited tremendously from soaring returns on capital. Real wages on the other hand have lagged well behind productivity improvements. The impact of globalisation on low-skilled jobs has been an important contributor here. As capital has shifted to lower labour-cost destinations, the owners of capital have benefited from the immediate uplift in productivity, while the workers that have been displaced have seen living standards fall. The graph below illustrates the 10-fold increase in real wages in China versus stagnation in the US and Japan.

Manufacturing hourly pay in real US$ terms
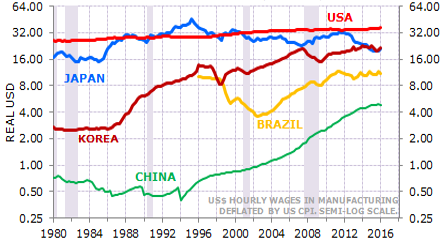
Source: Minack Advisors

Migration and open borders, another feature of globalisation and political union, has intensified this threat to job security. In the graph below, you can see how immigration has put downward pressure on the real wages of unskilled workers in the US. Austerity policies in the aftermath of the financial crisis have further stressed households dependent on social services. To them it seems unfair that the banks get bailed out yet they pay the cost through austerity.

US weekly median pay by education level
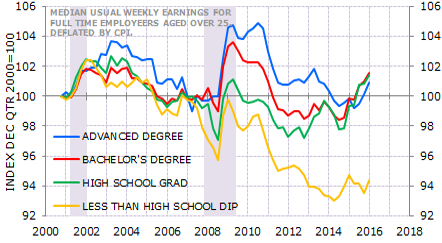
Source: Minack Advisors

Falling interest rates, another feature of the ‘great moderation’ of the past 20 years, have only exacerbated this trend toward inequality. Those who own most of the assets have benefitted as asset values have been bolstered by lower interest rates. The asset poor have missed out, while real wages have fallen.

Financial markets and politicians missing the signals

The disenfranchised are rejecting these liberal beliefs, giving rise to the nationalist and extremist views that are gaining popularity in many western countries. The unexpected Brexit result in the UK, the ascendancy of Donald Trump in the US, and the rebuke to the LNP in the Australian election are all manifestations of this. The political class appear detached from the shift in public opinion. Financial markets, where the true acolytes of the neoliberal church reside, are even further removed. A consequence is the ongoing failure of markets to recognise the importance of this protest vote and the potential impact on favourable policies that have been tremendously beneficial to investors.

The shift in political mood and the prospect of a reversal in these market-friendly policies are a negative for the market outlook. The political establishment also seems a long way from recognising the problem. Consider the retribution to Brexit voters the European Commission is calling for, clearly far from a workable solution.

Make no mistake; this is a very loud voice, a voice that will become louder until we see a reversal in the divergent trends in the above graph. In the meantime, the political risks will grow, unsettling financial markets.

Shifting demographics, weak productivity and deleveraging are all features of slowing global growth. The precipitous fall in bond yields in recent weeks reflects this outlook, with many bonds now trading below the zero bound. Australia’s 10-year government bond rate has slipped to 1.8%, fractionally above the cash rate. With the yield structure so flat and no carry or compensation for duration, it is hard to see any scenario where bonds can deliver anything but horrible returns in the medium term. Investors have been left with few choices, explaining the resilience of shares in the face of disturbing developments both politically and economically.

We feel more confident than ever in the merits of hedging strategies like those employed by Watermark. Bond yields are telling us the outlook for growth is as weak as it has been in a generation. There is no carry; a passive, buy and hold strategy will deliver low returns at best. Only an active strategy that can deliver enhanced returns through security selection stands a chance of delivering acceptable returns in this climate.


Justin Braitling is Chief Investment Officer at Watermark Funds Management. This article is for educational purposes only and does not consider the circumstances of any investor.


  •   11 August 2016
  • 5
  •      
  •   
5 Comments
David
August 11, 2016

Good article with many strong points but is it a little loose on the definition of productivity – my understanding is that within country productivity gains have been weak but productivity on capital (by switching to offshore manufacturing) has had a good run.

Garry Anderson
August 11, 2016

I live in UK and made analysis of income inequality metrics - after our government stated that inequality improved under them.

My findings destroyed the myth that inequality improves.

It is a fact that inequality in society - the range of incomes from the poorest family in poverty (with little or no income) to the richest (with great wealth built up because governments squeeze worker's not the rich) - increases massively every year.

Government authorities 'fiddled the figures' with statistical confidence tricks.

Analogy: If the government measured weight problems by ignoring the obese and dangerously underweight - you would say they were corrupt and trying to hide the problems - wouldn't you?

That is how they measure inequality - ignore the richest and poorest groups - those millions of people most affected by what is being measured.

Indeed, our highest authority with official oversight, the UK Statistics Authority (Deputy Head of Regulation) actually admitted to me about the Gini coefficient, “I agree with your observation that it is not ideal if your particular interest is in inequalities at the top or bottom of the spectrum”.

The authorities admitting the fact it is "not ideal" if you care about rich or poor.

The first time they disclosed the fact they know it hides the inequalities of the rich and poor – yet the media will not report it.

This is not just the Gini coefficient but also other metrics including the much praised Palma ratio.

I made a video of my findings on the Gini explaining so that even a school kid could understand:

https://www.youtube.com/watch?v=x1Y_fUlYs-Q

Jamie Forster
August 12, 2016

This study by the IMF (http://www.imf.org/external/pubs/ft/wp/2016/wp16160.pdf) provides an interesting counterpoint to the theory, developed by Thomas Piketty, that incomes had suffered because returns on capital had outpaced economic growth. The IMF's thesis exposes as flawed Piketty's assumption that correlation equals causation. In the absence of that assumption, the theory crumbles.

Thomas Sowell also provides thoughtful input into the debate https://www.youtube.com/watch?v=EgVDyBqAQNw

Gary Judd
August 12, 2016

"Those who own most of the assets have benefitted as asset values have been bolstered by lower interest rates."

It can be added that benefits also go to those who are able to be the first ones to access the new money whether the new money has been created through the banking system and at an added pace because of low interest rates or through QE.

Central banks' actions are the cause of interest rates being forced down and additional money being put into the system through QE. The reason is the belief that this interference with the market is in some way beneficial to economies. It hasn't been so central banks having dug the expanding money hole now dig it deeper by forcing interest rates down even further and, in some cases engaging an even more QE.

Is it rational to pursue these failed policies? A rational response is surely to note that the policies are failing to do what they are intended to do and to stop them, not to continue with them in the vain hope that what failed in the past may somehow succeed in the future.

In the meantime great damage is being done to the economic interests of those who are unable to benefit, to those who have ceased to be able to earn and increase wealth because the returns on their assets are being forced down and, socially, people are seeing the effects described in this article which may lead to all sorts of social consequences which in turn will exacerbate the cause of the problems by forcing governments to introduce even more regulation and control as well as engaging in the irrational policies of trying to get more money into the system.

Jonathan Hoyle
August 13, 2016

Justin,

Deregulation and the freedom of movement of people and goods (economic liberalism or 'rationalism' to use a pejorative term) has lifted some 500 million people out of poverty over the past three decades. Living standards have risen exponentially for middle and upper class Westerners, and for all people, especially the poor, in the developing world. The (relative) losers have been unskilled Westerners. We shouldn't lose sight of this fact. Let's not forget the economic horrors of government ownership, fixed markets and closed borders.


Leave a Comment:

RELATED ARTICLES

If rising inequality leads to social unrest, we all suffer

Taxing the ‘rich’: the potential tax consequences of inequality

In Australia, who’s got the money?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.