Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 66

Making judgments based on age

Complexity is one of the challenges of our information society, and we typically respond by making simplifying assumptions. This helps us manage the complexity but increases the risk of focusing on the wrong things. Worse, our prejudices easily lead us to simple answers which are consistent with our views but are often biased and misleading.

The complexity of longevity

Increasing longevity is one of the most challenging and complex issues we face – as a community and as individuals. It’s easy to fall into the trap of making sweeping statements. Prejudice, often fuelled by personal fear of our own mortality or that of our parents, can lead to big errors of judgment.

Why, for example, is there a disproportionate number of professional ice hockey players in Canada born in the first months of the calendar year? Readers of Malcolm Gladwell’s Outliers know that the selection of young players for higher-level ice hockey coaching starts in year seven or eight. Children born early in a calendar year are more mature than their age peers born late in the same year. So they tend to be chosen for further coaching. Same ‘age’ but different capabilities.

We become increasingly individual and different as we mature. Our community largely avoids using age as a basis for judgment until around age 60 when quite suddenly ‘age’ again becomes an issue. It’s used as a decision point if we want to ‘retire’ or access our super or get a free transport pass. In its report ‘Access All Ages – Older Workers and Commonwealth Laws’ (March 2013) the Australian Law Reform Commission identified a plethora of areas in which age has become more obviously a basis for discrimination than it might have been at the time the original legislation appeared.

‘The end of the Age of Entitlement’ has now entered our vocabulary as a justification for a series of age-based changes to government support (along with many other changes).

Has the notion of a numerical age outlived its usefulness? We are already evolving more sophisticated ways of evaluating ourselves. Could we be heading for a new ‘Age of Enlightenment’ where we create more contemporary models to help us know and manage ourselves better with increasing longevity? If so, this should lead to more effective allocation of expensive resources. Benefits would accrue to both individuals and governments.

Personal capital or value

At My Longevity, we developed a simple model which a person can use to help with their ‘retirement’ decisions. It shows how our personal value (capital) can be seen as a simple combination of our capability and experience. These accrue and eventually decline at different rates over our working life. The model invites people to consider the impact of retiring on their personal value. Each of us is different so the individual model varies accordingly. It can help shift the retirement focus to one of personal value rather than just financial value, and introduces the notion of a personal time frame to underpin decisions. It also fosters the important notion of mastery over personal circumstances which in turn supports the quest for independence.
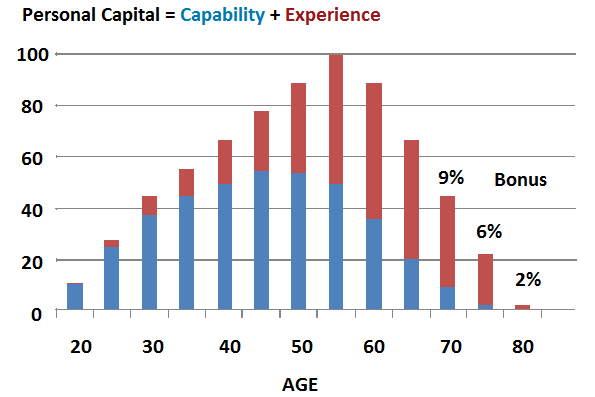

Source: My Longevity Pty Ltd

This illustration shows how personal capital can accrue over time with a potential bonus from deferral of retirement. Personal circumstances can vary a lot from this model. Although our capability might decline in later years, it can be compensated for by our experience.

There are many other ways of showing people the diversity of options that can open up with greater longevity awareness.

Older people are increasingly seeking information and services which help them manage their lives better. Many of them want to continue to contribute to society and do so.

When governments discriminate in delivering services using outdated metrics like age, they risk giving the message that they are behind the times and out of touch with reality. They attract criticism and waste opportunities to encourage informed independence.

Success in managing longevity requires an effective partnership between individuals and governments. Maximising personal capability requires an environment that is supportive and nurturing.

As Malcolm Gladwell suggests: “It’s true in sports and it’s true in the rest of our lives as well. We need to wake up to the fact that as a society we haven’t been doing our part.”


David Williams began longevity research in 1986 and was a Director with RetireInvest and CEO of Bridges. He chaired the Standards Australia Committee on Personal Financial Planning. David founded My Longevity Pty Limited in 2008.


  •   13 June 2014
  • 2
  •      
  •   

RELATED ARTICLES

Retiring from work is easy, retiring into life is harder

Why a traditional retirement may be pushed back 25 years

Let's ditch the idea of retirement

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.