Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 220

Six ways to improve your term deposit outcome

Investors who want a secure place to keep their money without any market risks are faced with meagre choices. The cash rate is only 1.5%, and term deposit rates are around 2.5% for most terms, which is barely higher than inflation.
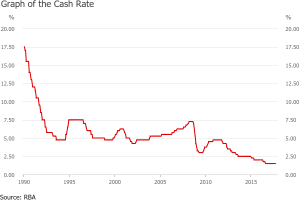
Yet term deposits and cash accounts are the mainstay of most personal investment portfolios, including about 30% of the assets of self managed super funds. With such low rates, investors need to rethink their term deposit rollover strategies and not simply accept the poor rates offered by their bank at maturity time.

The power of ‘retail inertia’

Back in the good old days, before political correctness, banks used to describe the willingness of customers to accept poor term deposit rollover rates as ‘retail inertia’. This means that banks might have a term deposit special at 3% and rollover similar deposits at 2%. The vast majority of existing customers accepted the lower rate.

Check what it says on a typical term deposit rollover letter: “If you have a special rate, that rate will generally apply for a single term. Standard term deposit rates may apply for subsequent terms.”

Which is bankspeak for: “You’ll receive a lower standard rate on rollover unless you ask for a special one.”

Banks also offer special bonus rates for the first four months on some at-call deposits. At the end of the four months, customers fall to the ‘standard’ rate, and most don’t leave.

A 0.3% bonus for four months is equal to only 0.1% per annum, an immaterial cost to the bank for gathering genuine retail deposits. It’s the same with credit cards and the ‘six months interest free’ for switching banks. They hope customers can’t be bothered changing again.

Don’t ignore the bank rollover letter

The term deposit rollover letter is not like the gas or electricity bill where the customer must accept the cost. There are many ways an investor can improve the outcome:

1. Critically review the rollover rate. Most depositors tick ‘rollover for the same term on maturity’ when they open a term deposit, and if no action is taken, the rate offered by the bank will be locked in. Most banks give a one-week grace period if the rollover date is missed.

2. Phone your bank and ask for a higher rate. First, go to a comparison website such as ratecity.com.au or mozo.com.au, and arm yourself with the highest rate. Deposits of less than $250,000 with any ‘Authorised Deposit-taking Institution’ (ADI) are guaranteed by the Government.

Even if the bank is not prepared to match the offer from a small credit union, the bank will probably offer more than in the rollover letter.

3. Watch changes in terms and conditions. In the past, banks allowed early access to term deposits but they have become much stricter and usually impose penalties for early withdrawal. In some cases, banks have written to customers saying funds cannot be accessed (even with a penalty) inside a 31-day notice period.

4. Consider another term, although accepting higher rates for longer terms carries risks of being locked in for longer. A five-year rate at only 3% might be too much exposure to rising rates.

5. Don’t leave the paperwork until the last minute. Although banks usually nominate a grace period to negotiate a rollover, some require attendance at a branch to verify a variation.

In today’s online and mobile world of banking, it can be frustrating finding a branch just to sign a form. Also, the interest rate paid during the grace period is nominal, 0.5% to 1%, so act early.

6. Review the range of alternatives. Where term deposits once offered decent rates, now they give little more than capital security with the protection of the Government Guarantee for ADIs.

It’s worth checking alternatives such as bonds, bond funds, Exchange Traded Funds or listed securities, but they come with more risk and professional advice may be useful. All investment platforms have a range of bond funds and income-based options.

Whenever you see the words ‘Automatic Renewal’ on a term deposit rollover, there’s a strong chance you can do better.


Graham Hand is Managing Editor of Cuffelinks. This article is general information and does not address the circumstances of any individual.


  •   21 September 2017
  • 1
  •      
  •   

RELATED ARTICLES

The terms they are a-changin’

Finding income in an income-starved world

Why bank hybrids are being priced at a premium

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The investing rule that explains the next market crash

What if investment success depends less on picking the right assets and more on understanding the decisions of other investors? A principle borrowed from game theory offers a different perspective on markets.

Latest Updates

Fixed interest

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Economy

Are we in a recession?

What if the warning signs are already everywhere? From supermarket aisles to company failures, investors are being bombarded with recession signals. But most face a different risk that can be just as dangerous for portfolios. 

SMSF strategies

Meg on SMSFs - Division 296 actuarial certificates

The tax bill might be yours, but the event that caused it may not be. A key Division 296 calculation can sometimes attribute earnings in ways that many SMSF trustees won't instinctively expect or fully appreciate.

Property

The first impact of negative gearing reform is not the tax bill

Negative gearing changes formally begin in 2027, but the first consequences may already be here. A subtle shift is quietly influencing who can borrow, how much they can access and which property strategies still stack up.

Economy

The oil market is running out of easy answers

The biggest threat to markets may not be what investors are watching. The numbers have stopped adding up and supply is harder to measure, with forecasts becoming simple guesses. A more fragile reality is being masked.

Investment strategies

The state of investor knowledge in Australia

Australians are investing more than ever, yet a surprising divide is emerging between those building wealth effectively and those making costly mistakes. Surprisingly, the gap has little to do with income, age or starting capital.

Taxation

Complexity and capital gains

A case study shows that the ‘30% minimum CGT’ is a poorly conceived tax that adds significant complexity to an already over-complex system. A less complicated model would create a much fairer progressive tax scale.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.