Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 501

Three themes and companies to play China's rise

The structural drivers for China's growth remain intact, and we expect Chinese companies to benefit from trends such as rising incomes and wealth, increasing demand for premium goods and services, and burgeoning sophistication in technology and manufacturing. There will also be opportunities for companies to innovate and move up the value curve. This, coupled with China’s increasing role in global trade, should bode well for exports as well as domestic consumption.

We highlight three examples of long-term themes and companies which are likely beneficiaries.

Industrial automation aims to offset a shrinking workforce

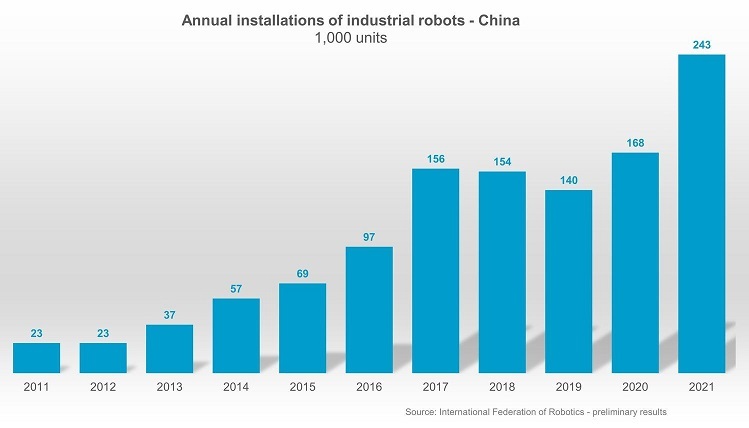
The impact of China’s earlier one-child policy will continue to be felt in the coming decades. Its working age population, or people between 15 and 64, will contract by 22% or 217 million people. To counter the anticipated labour shortages, the government seeks to improve manufacturing through automation and robotics, which means China’s automation market will see strong secular tailwinds. For example, the country set a record of 243,300 industrial robots in 2021, a 44 per cent increase from the previous year.
Shenzhen Inovance is an industrial automation company with leading positions in inverters, servomotors and new energy vehicle (NEV) controllers. It has repeatedly proven its capability in developing new products and entering new markets, where it can compete with multinational peers. As of March 2022, the company has generated 28% per annum shareholder returns since its IPO in 2010, with 40% compound annual growth rate (CAGR) in sales and 35% net profit CAGR*. Despite its size, our view is that Inovance can continue to generate attractive growth over the next 5-10 years as it gains market share and continues to innovate.

Healthcare companies stand to gain market share

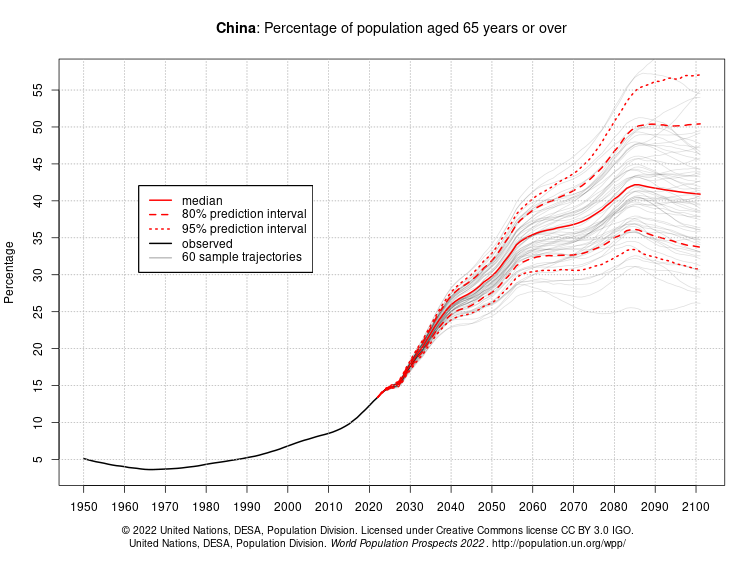
Healthcare spending, while much lower than in developed countries, is expected to grow as China’s population ages. The population over 65 will increase from 14% of the total population in 2022 to 30% in 2050.
Shenzhen Mindray is China’s largest domestic medical devices company and a market leader in patient monitors and life support systems. Growth across categories has picked up in recent years, and Mindray’s market position for each category has been improving as well. It has gained market share from global leaders as it expands its presence overseas and has more than 40% of its sales through exports*.

In the domestic market, we expect increased hospital spending on medical equipment to contribute significantly to its revenue. There are also growth opportunities ahead, as the penetration level of medical devices in China is still low and there is a growing preference for import substitutions.

Domestic brands may benefit from premium consumption

Structural growth is expected to return to domestic spending with the recovery of consumer confidence. Amid weaker consumer demand resulting from the pandemic in the last two years, we focused on buying high-quality franchises and market leaders – those companies with above-average margins and returns, and which can increase selling prices.

One sector we looked at was China’s beer market, which is different from most other countries. It is highly consolidated with the top three companies, China Resources Beer (CR Beer), Tsingtao and Anheuser-Busch InBev, sharing 75% of the market as per our research in 2022*. Despite beer volumes declining since 2014, the improving economy and a growing middle class has seen some brands looking to develop more premium products, improving unit economics. Sales and profitability have also improved as beer companies consolidated their breweries.

CR Beer’s share of premium sales has grown with the help from a 2019 merger with Heineken China, resulting in higher average selling prices. Although the company is a state-owned enterprise, China Resources businesses have typically been well run, with returns comparable to private enterprises. Additionally, while investors were worried about higher prices of inputs like aluminium cans, historically beer companies have been able to pass on costs, while the gross profit margin of circa 40% should limit the impact on profits.

Conclusion

This year marks the 30th anniversary of the FSSA China Growth strategy. While China has changed significantly over the last three decades, the key driver of share prices over the long term remains companies’ ability to generate value by growing their earnings or net asset value. Therefore, we use bottom-up analysis and focus on quality companies, with capable leaders who are aligned with shareholders. 


*N.B. Source: FSSA Investment Managers, company data retrieved from company annual reports or other such investor reports. Financial metrics and valuations are from FactSet and Bloomberg. As of February 2023 or otherwise noted.

Martin Lau is a Managing Partner and Lead Portfolio Manager at FSSA Investment Managers, based in Hong Kong. FSSA is part of First Sentier Investors, which is a sponsor of Firstlinks. This article is intended for general information only.

For more articles and papers from First Sentier Investors, please click here.


  •   22 March 2023
  • 4
  •      
  •   
4 Comments
Harry H
March 26, 2023

The issue with thematic investing is that the themes are normally well known and priced in.

Often it also hides complexities. I've covered Chinese healthcare and it is a minefield of regulation and bureaucratic layers and picking winners and losers is very difficulty.

Peter
March 26, 2023

I would never invest in China/Russia or any authoritarian controlled country. These types of governments can change the rules overnight with investors losing their money. I believe Russia has made decisions that investors from "unfriendly countries" will no longer receive dividends and some significant investors such as international airline companies have lost their money entirely or are having difficulty getting it out of the country. Why would you risk your money when these dictators have proven to be unpredictable and untrustworthy.

Trevor Cheng
March 28, 2023

Need to be more convincing especially given the local corruption and the state ability to step in to keep money in the country.

Warren Bird
March 28, 2023

Martin is one of the most experienced investors in the world in Chinese companies (and other emerging markets), the portfolio manager for one of the most successful funds in that space, and one of the smartest people in the EM field you could ever meet. The funds he manages have always taken governance issues seriously and he would be more aware of the reality of corruption in certain places than anyone else. Full disclosure - I worked alongside Martin when I had oversight of the Asian fixed interest team for Colonial First State from 2005 to 2012. He's one of the most decent people in the industry I've met.


Leave a Comment:

RELATED ARTICLES

China in advanced stage of demographic collapse

Is China’s regulatory reform stifling ‘animal spirits’?

China’s new model is a plan for a hostile world

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Latest Updates

Planning

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Investment strategies

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Economy

Population growth masks Australia’s productivity problem

For years, investors have benefited from a seemingly reliable growth story. But recent national accounts raise uncomfortable questions about what has really been driving Australia’s economy and whether that can continue unchecked.

Investment strategies

Why tomorrow’s winners may not be today’s index leaders

The stocks that built retirement balances over the past decade now dominate many portfolios. The new challenge is whether these companies can continue meeting the increasingly high expectations embedded in today's share prices.

Investing

What earnings surprises reveal about future returns

Sometimes the most important information in an earnings result isn't the number itself. It's the possibility that the market's assumptions have been fundamentally wrong and future earnings may look very different.

SMSF strategies

Individual SMSF Trusteeship directly liable for ATO fines

A rarely discussed detail buried in SMSF structures could dramatically change who wears the cost when something goes wrong. With penalties rising, a decision many dismissed as administrative may deserve a second look.

Investment strategies

The currency bet you didn’t know you made

Buying global shares means making two bets: on the companies and on the Australian dollar. Most investors consciously choose only the first. Last financial year, the second bet cost 8.5% in returns for many investors.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.