The market has rewarded investors for owning the companies that grew into today’s index leaders. But the next phase of the AI cycle may test whether owning the winners of the last cycle is enough. The active-passive investing debate is often framed around fees, market efficiency, and recent performance. Those issues matter, especially after a decade in which benchmark exposure has been difficult to beat. But they can obscure a more fundamental point: a stock is a claim on a company’s future cash flows, and its price reflects today’s expectations for those cash flows. Future returns, therefore, depend on the gap between what the market expects today and what ultimately occurs.
Why is this important to bring up now? Because AI is changing the economics of growth: the opportunity is large, but so is the capital required to pursue it.
In our view, today’s AI-driven capex cycle will be more capital intensive for the companies that now dominate market-cap-weighted indices. Demand and earnings remain favorable, but growth now requires heavy investment, straining free cash flow and bringing execution, financing, regulatory, and overcapacity risk. The opportunity for strong returns has not disappeared, but the capital cycle has raised the bar and the margin for error has narrowed.
While stock prices are forward-looking, market-cap-weighted indices allocate the most capital to companies that have already become large, reflecting past earnings growth, share-price appreciation, and investor conviction. Passive investors, therefore, can remain anchored to today’s market leadership through benchmark weights earned by prior success. Put differently, passive captures the consensus efficiently but does not challenge whether that consensus will prove to be right. If AI changes the economics of growth, the question is whether the conditions that produced today’s market leaders can persist, and where the next generation of market leadership will emerge.
Beyond capex, AI is reshaping industries, redirecting profit pools, and challenging business models. Some companies will use AI to improve productivity, deepen customer relationships, and protect margins. Others may be disintermediated as software automates labor, distribution, or expertise. That makes capital discipline, not just technical ambition, central to the next phase of returns.
Why capital cycles matter
Capital cycles are simple but powerful: High returns attract capital; capital creates capacity; capacity changes competition; and competition affects pricing power, margins, and future returns. Successful companies may not necessarily fail, but exceptional returns should also not be assumed to persist. As AI investment accelerates, the key issue is how AI translates into durable value creation: some companies will deepen their advantages, while others will discover that growth is not necessarily value creation.
Active management seeks to distinguish between those outcomes before they are priced in. A market-cap-weighted index owns future winners and future losers in proportion to their current market value. It does not judge which companies, sectors, or assumptions will be rewarded or hindered in the next phase of the cycle.
What happens to passive investing when the opportunity set shifts
The decade following the global financial crisis created unusually supportive conditions for passive investing: falling rates, abundant liquidity, globalization, and the rise of asset-light business models. Earnings growth was rewarded, multiples expanded, and the largest companies became larger. This produced a powerful feedback loop: strong fundamentals lifted prices, prices raised benchmark weights, and higher weights increased passive exposure.
As shown in the chart below, much of today’s concentration has been justified by genuine earnings delivery. Concentration is not a judgement about future leadership; it is an outcome of past success. The question is whether those profit pools will remain durable, and what might cause leadership to broaden or rotate.
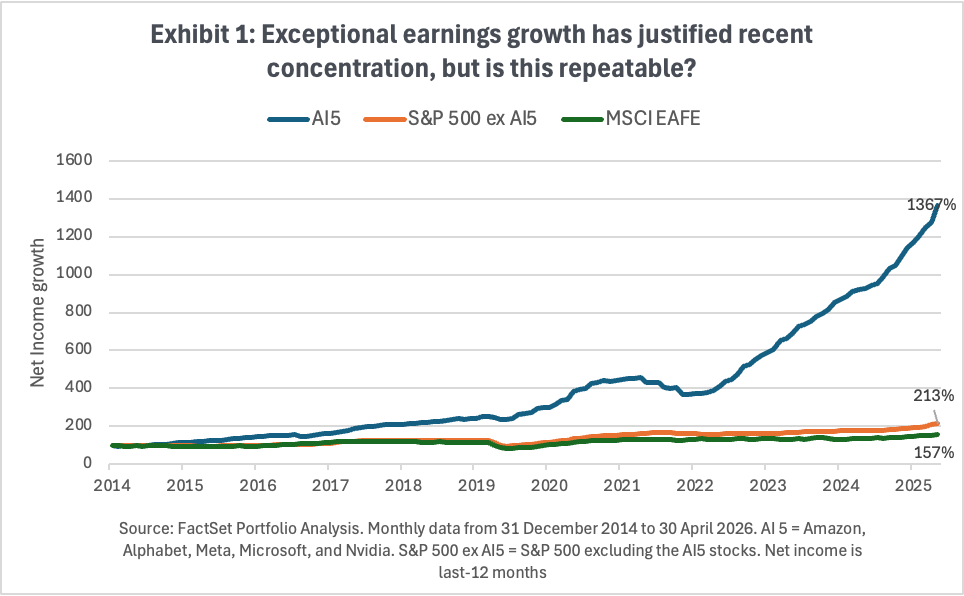
Passive generally works well when the consensus is broadly right and the future resembles the recent past. It is less suited to environments where the opportunity set shifts, the cost of capital changes, and tomorrow’s winners differ from yesterdays.
What changing market conditions mean for active investing
For active managers, rising market concentration and the growing dominance of the largest index constituents have had portfolio construction consequences: Underweighting the largest stocks became not only a valuation or conviction decision, but a portfolio-construction challenge. Not owning or underweighting these companies materially reduced portfolio beta, and investors often found it difficult to replace that exposure through other growth investments. As market returns became increasingly concentrated in a small group of stocks, lower beta portfolios faced a meaningful relative performance headwind.
Any credible argument for active management must acknowledge recent history: Many active managers have not delivered consistent excess returns, and investors have been well served by low-cost benchmark exposure. In some cases, active managers were too cautious toward high-growth companies, too reliant on mean reversion, or insufficiently differentiated after fees.
The lesson is to raise the standard for active management. It must be selective, differentiated, and disciplined and offer real value for the fees charged. The case for active management must therefore rest not on dismissing passive, but on understanding that market prices reflect expectations and expectations are assumptions, not facts.
Alpha requires both a differentiated view and an opportunity set in which that view can be rewarded. For much of the past decade, the opportunity side of that equation was constrained by low dispersion, dominant benchmark leaders, and macro conditions that lifted many businesses together. If dispersion rises, however, as capital cycles turn, the likely winners may be the businesses whose future cash flows can still exceed what the market has priced in. The winners of the last cycle earned their index weight; the next cycle will test whether they can keep it.
Robert M. Almeida is a Global Investment Strategist and Portfolio Manager, and Ross Cartwright is a Lead Strategist in the Strategy and Insights Group, at MFS Investment Management. This article is for general informational purposes only and should not be considered investment advice or a recommendation to invest in any security or to adopt any investment strategy. It has been prepared without taking into account any personal objectives, financial situation or needs of any specific person. Comments, opinions and analysis are rendered as of the date given and may change without notice due to market conditions and other factors. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343).
Unless otherwise indicated, logos and product and service names are trademarks of MFS® and its affiliates and may be registered in certain countries.