Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 70

Australia’s default: the winners and losers from bonds

Part 1 of this storycontained a brief outline of government debt – both domestic and foreign - and various ways in which governments can avoid repaying their debts in full, through default, restructure and/or inflation. We also looked at the level of Australian government debt compared to the current government debt crisis, and how it compares to Australia’s debt level today.

In Part 2,we looked at how Australia’s big default and debt restructure occurred, which bond holders were rescued, and which were forced to take a ‘haircut’ on their interest and principal repayments.

Here, in Part 3, here we look what it meant to bond investors, including the returns achieved by bond investors before, during and after the debt default and restructure. We will focus on returns to local investors on domestic Australian debt since they were the ones directly affected.

We see that money was made for bond holders, and even those who hung on and were hit with the ‘haircut’ restructure.

Returns were good for patient investors

The first chart shows monthly returns (top section) and cumulative returns (lower section) on domestic long term Commonwealth bonds from the start of 1929 to December 1932.
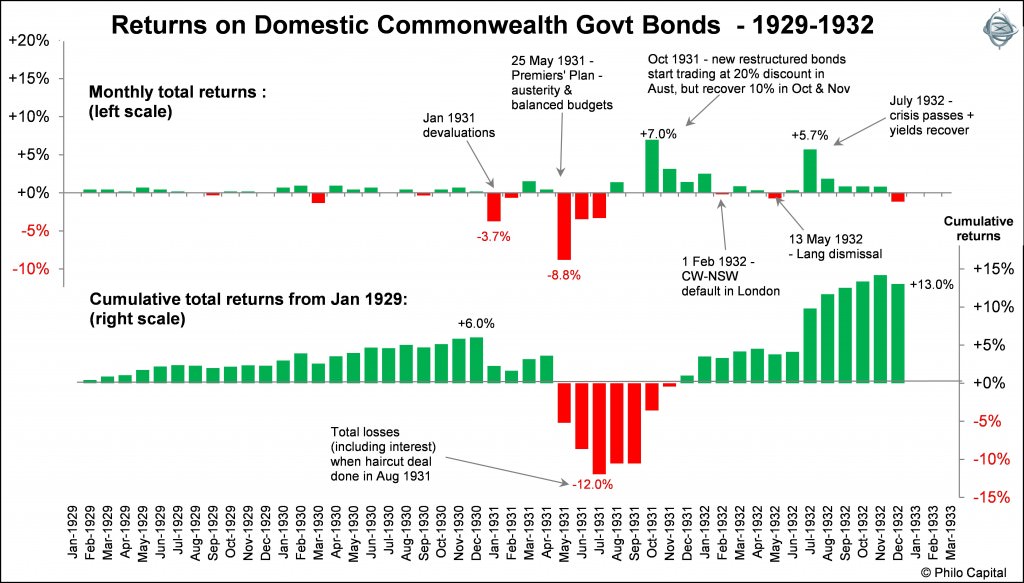
Bonds returned 13% in total over the four years, made up of 19.3% from total interest payments minus a 6.3% capital loss.

The next chart shows prices for long term bonds in both markets: domestic bonds in the Australian market (green line) and foreign bonds in the London market (red line). The lower section shows cumulative returns from interest on domestic bonds (blue bars) and cumulative capital value (red bars).
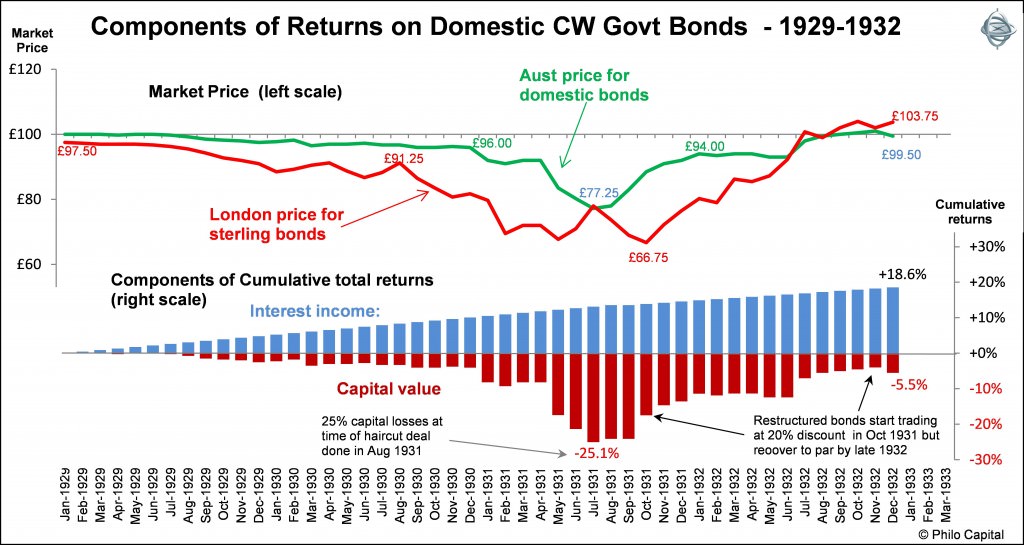
Patient investors who held onto their bonds, took the haircut deal, bought new replacement bonds, and then held them until the end of 1932, would have achieved total returns (i.e. interest plus capital gains/losses) of 13%.

A 13% total return over a 4 year holding period doesn’t sound very good, but after inflation (or deflation actually) it amounted to a healthy 30% real return because consumer prices had fallen by 17% over the period, and wages had fallen by around 10%. In terms of the real spending power of investors’ money after inflation, the 30% return over 4 years equated to 6.8% per year compound return after inflation. Not a bad return for patient investors, even after the default and restructure in 1931-1932.

A major contributor to the good returns was the fact that the new replacement bonds did not sell for par at auctions. They were sold at significant discounts to par because investors were still nervous about the government’s ability to service even the new lower interest payments. These discount purchase prices contributed to good returns as market prices quickly rose back up near par during 1932 as confidence returned and yields declined from crisis levels.

Winners and losers

On the other hand, investors who bought domestic 10 year bonds in December 1930 when yields were an attractive 6.4%, and then sold out in the panic in July 1931 when and the government was talking about default and bond prices had crashed 20% from £96 to £77, with yields soaring to nearly 13%, would have lost 18% on their investment.

Likening this to the current European debt crisis, investors who lend money to Greece at 100 cents in the dollar before the crisis (mainly European banks) and then panic sold in early 2012 at less than 20 cents in the dollar before the restructure was announced, would have lost 80% of their money. These were permanent losses. The big winners in Greek debt were the numerous hedge funds that bought up Greek bonds from the panic sellers at prices as low as 15 cents in the dollar in early 2012, and then doubled their money when the old bonds were exchanged for new bonds an average of around 33 cents.

There are winners and losers in all markets. Even when governments default on their debts there is money to be made by investors who resist the temptation to panic sell in a crisis (and also resist the temptation to panic buy in a boom for that matter).

In Part 4 we will look at the returns from the broad stock market versus the government bond market during the crisis. We see how the impact of the Greece-like default and restructure of government bonds affected bond returns, compared to the impact of the 1929 crash had on share returns.


Ashley Owen is Joint CEO of Philo Capital Advisers and a director and adviser to the Third Link Growth Fund.


  •   11 July 2014
  •      
  •   


Leave a Comment:


RELATED ARTICLES

Less than 1% for 100 years: watch the price risk on long bonds

Australia’s default: shares versus bonds through the crisis

banner

Most viewed in recent weeks

Why have Australian living standards 'fallen' and how do we fix it?

For the last few years there has been much talk of a 'cost-of-living' crisis in Australia and of 'falling living standards'. Lately this has flared up again with the pickup in inflation resulting in a renewed fall in real wages.

Will you run out of money in retirement?

Fear of running out has become a defining retirement anxiety. Why do some retirees die with substantial wealth while others deplete their nest egg? Evidence suggests the answer is more complicated than we think. 

Four options for an income investor’s next dollar

What if Australia’s golden age of dividends is ending? Rather than overhaul your portfolio, it may be worth considering where new capital can work harder. I discuss four income strategies and the trade-offs behind each.

The investment that sidesteps the new tax traps

Tax rules have changed, but many investors are still using yesterday’s strategies. Insurance bonds may offer advantages for those seeking greater control, tax efficiency and certainty about their wealth.

Welcome to Firstlinks Edition 674 with weekend update

What begins as appetite, grows into excess and ultimately ends in spectacle. Millions of investors just discovered this the hard way.

  • 6 August 2026

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Latest Updates

Retirement

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

SMSF strategies

Who really loses from the SMSF borrowing ban?

The ban on borrowing to buy residential property inside a self-managed super fund was framed as closing a loophole for the wealthy. Yet ATO data suggests its effects may be felt more heavily on members with moderate balances.

Investment strategies

The investing rule that explains the next market crash

What if investment success depends less on picking the right assets and more on understanding the decisions of other investors? A principle borrowed from game theory offers a different perspective on markets.

Investment strategies

Gold: should you own the metal or the miners?

Gold is back in the headlines but investors may be asking the wrong question. Before deciding where prices are headed next, it's worth considering whether the investment you choose will deliver the outcome you're actually seeking.

Fixed interest

Global bonds markets are hiccupping

For decades, investors looked the other way as government debt ballooned. But a reckoning may be beginning. Bond markets are stirring and the consequences could reach far beyond markets into everyday life.

Property

Why investors are looking beyond traditional property sectors

A little-known corner of the property market may be quietly benefiting from powerful demographic and healthcare trends. Could this specialised sector offer investors something increasingly difficult to find: enduring demand?

Retirement

Retirement in reality - 6 months in

Is retirement really an identity crisis, or is something else at play? New insights challenge conventional thinking and reveal why some retirees struggle to fully embrace life after work.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.