Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 71

Which countries should be classified as emerging market?

Many retail investors are drawn to invest in emerging market funds, but think little about which countries they are investing in? Emerging market indices are poor representations of the investment opportunities available in that asset class. This arises in part because the index includes countries which are no longer emerging and omits some which manifestly are.

Readers would have no problem naming countries considered ‘core’ emerging markets: China, India, Brazil, Mexico. Others would utilise the ‘BRICs’ misnomer. But how about Vietnam? Or Israel? Or Taiwan?

It’s difficult to compile a definitive list of which countries qualify as ‘emerging markets’ and which do not. The methodology for including countries in the index is far from academic. Investors in emerging markets, and particularly retail investors purchasing exchange traded funds which mirror the index, have a particular conception of what they’re buying: access to markets where, in theory, there is scope for higher returns if investors are willing to tolerate the potential for higher risk.

Investors in the asset class typically seek to benefit from the tailwinds around hundreds of millions of people being lifted out of poverty via globalisation, through the allocation of capital to companies which are contributing to and benefiting from sustainable development.

Yet this is hardly a truthful representation of the constituents of the index. Most prominently, South Korea and Taiwan are not countries characterised by youthful populations, rapid urbanisation, a shift from agriculture to industry and an emerging consumption-driven middle class. They went through those transitions years or even decades ago.

Rather, these are societies where the median age is higher than the US, GDP per capita is higher than Italy and life expectancies match those of Denmark. On the UN’s Human Development Index (HDI) from March 2013, both are very firmly ‘very high human development’ societies. Indeed, both have levels of human development higher than that of the UK.

Yet emerging market indices typically allocate a quarter of their assets to Taiwan and South Korea, countries not yet reclassified as developed markets based purely on the basis of technicalities around market access.
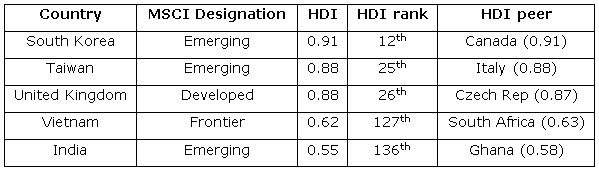
Meanwhile emerging markets investors struggle to access large developing country markets like Vietnam, Nigeria and Bangladesh, which are quickly integrating themselves into the global economy and ‘emerging’ as viable, long-term investment destinations. These ‘frontier’ countries are firmly emerging markets in socioeconomic terms.

This situation results in investors missing out on long-term investment opportunities. Equally, those countries excluded by emerging market indices are overlooked for portfolio flows which can help contribute to long-term socioeconomic development.

This is only one, albeit pertinent, example of the absurdity of investing according to an index, for the simple reason that they are necessarily backwards looking. Both in terms of companies and countries, they are composed of yesterday’s winners, not tomorrow’s. Investing through indices is akin to driving along a road by looking in the rear view mirror.

The concept of exchanges falling into categories such as developed or emerging is a diminishing cogent notion. It is becoming increasingly easy for companies to choose the location in which to list, such as Chinese entities in New York or Russian companies in Hong Kong. More and more businesses are now truly global, and are either listed in developed markets but derive a significant to large portion of earnings from emerging markets, or vice versa.

The index thus bears little resemblance to the opportunities available to investors in emerging markets. This is especially so when the indices include countries which no longer benefit from the strong sustainable development tailwinds that are expected to be the driver of potentially higher returns in emerging markets whilst excluding some which do.

Bottom-up stock-pickers should not be hamstrung in searching for returns for their clients by arbitrary indexes. The fact is businesses do not run themselves in line with indexes so therefore asset managers should not feel the need to allocate capital or define risk on such a basis.


Jack McGinn is an Analyst with First State Stewart, part of Colonial First State Global Asset Management, specialising in Asia Pacific, Global Emerging Markets and Global Equities funds.


  •   17 July 2014
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Burma diary: how millions of people make a living

From building BRICs to building blocs

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Retirement

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

2026 is not 1999

The US market looks eerily similar to the dot-com era with soaring AI spending and tech giants dominating returns. But one difference separates today’s boom from the dot-com bubble and it could determine what happens next.

Planning

Taxing time for trusts

Trusts are facing a shake-up, but an overhaul may not be necessary. Families can explore restructuring strategies that preserve succession and the asset protection benefits that have made these structures valuable.

Economy

Why the US economy is stronger than you might think

War, inflation and higher rates were expected to derail America. But has the market got it wrong? Three forces are driving the economy beyond expectations, revealing implications for stock prices and portfolio positioning.

Gold

How much trust is in your portfolio?

Everyone talks about diversifying assets. Far fewer think about diversifying trust. As inflation, debt and market assumptions collide, the question is whether portfolios need greater protection from unexpected outcomes.

Retirement

Retirement in reality - 7 months in

Seven months into retirement, I'm still uncovering surprises. This month was spent reflecting on the slow pace of health change, the myth of neatly scheduled part-time work and the unexpected persistence of retirement guilt.

The new geography of technology leadership

The next chapter of technology may not belong to the companies or business models many expect. As the landscape shifts, some opportunities are emerging in places that remain surprisingly overlooked by global markets.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.