For those ASX-listed companies with a 30 June balance date, investors will have two or three opportunities over the next few months to perform a deep dive behind the words and phrases within each company’s releases. These include the Preliminary Final Report (Appendix 4E), the Annual Report and the Chairman and CEO addresses at the Annual General Meeting.
Commentary from companies acquiring or divesting businesses or interest in businesses need extra attention in terms of the true ‘like for like’ comparison, often due to the objective of painting a positive outlook. It is only through deep analysis that investors can make more educated investment decisions.
For example, if we backtrack two years to August 2012, many Australian resource service companies were recording record revenue, profits and margins. Large contracts and acquisitions were being announced and the outlook was buoyant.
To illustrate the deep dive approach required, I will use the following ASX announcements from Ausdrill Limited (ASX: ASL) with the objective that investors may learn from this experience.
On 28 August 2012, Ausdrill announced the “strategically important acquisition” of Best Tractor Parts Group (BTP) for $165 million, on a debt-free basis, to be completed on or around 31 October 2012. In the year to June 2012, BTP generated revenue of $176 million and EBITDA of $50 million (unaudited).
“Subject to completion occurring, all profit generated by BTP from 1 July 2012 will remain within BTP (and the Ausdrill group will therefore become entitled to the benefit of such profit from completion).”
On 29 August 2012, Ausdrill released four documents: its Appendix 4E, a Media Release on the 2011/12 Results, the Annual Report to shareholders and a Results Presentation. The electronic version of these reports totalled 191 pages.
The results for the year to 30 June 2012 were at record levels with revenue up 27% to $1.06 billion, EBITDA up 48% to $288 million and Net Profit After Tax up 53% to $112 million.
“Based on current trading conditions, and excluding the effects of the Best Tractor Parts acquisition, the Board is confident that continued growth can be achieved in 2012/13 with a targeted growth rate of 15% in revenues whilst maintaining similar operating margins.” The final sentence of the media release touched on “Targeted areas for expansion over and above growth in core businesses.”
On one hand, things could not have been more positive. In addition to the record earnings and even better outlook for 2012/13, Ausdrill had recently welcomed back a senior executive to take up the newly-made Chief Operating Officer - African Operations position, and had signed a US$540 million five year contract in Mali, West Africa with Resolute Mining Limited.
The consensus immediately added 15% to the just-released 2011/12 revenue and EBITDA numbers and then added at least two-thirds of the historic numbers from the proposed BTP acquisition (given it was to be completed on or around 31 October 2012) to arrive at a FY13 forecast for EBITDA of $364 million on revenue of nearly $1.34 billion.
On the other hand, Ausdrill did cast a warning on page 3 of the 132 page electronic Annual Report for the year ended 30 June 2012:
“As we look ahead there are conflicting signals in terms of the outlook for the mining industry. In Australia, junior exploration companies are having difficulty raising funds. As a consequence the demand for exploration drilling has reduced. However, as a result of our focus on production-related services under medium to long term contracts, combined with our strategy of working for major mining houses, the effect on the company should be minimal.”
During October 2012, Ausdrill had refinanced its debt and signed a new three year dual currency, syndicated facility for a total of $550 million, as well as completing the BTP acquisition.
By late November 2012, investors and potential investors could view two releases to the ASX: a Market Update, dated 22 November 2012 and the Chairman’s address from the Annual General Meeting, dated 23 November 2012.
“Revenue guidance for the 2013 financial year now includes BTP and is revised to a 20% increase from 2012.”
Deep dive: this equates to $1.27 billion ($1.06 billion X 1.2), or around $70 million or 5% below the consensus forecast three months earlier (of $1.34 billion).
“The BTP business will be consolidated into Ausdrill’s financials from 1 November 2012 and is expected to account for 10% of consolidated revenues.”
Deep dive: Assume BTP accounts for $130 million of the lower $1.27 billion revenue forecast for 2012/13. Then the traditional business would contribute $1.14 billion. This is a 7.5% boost to the 2011/12 revenue figure of $1.06 billion, and compares with the targeted growth rate three months earlier of 15%.
From the Market Update, dated 22 November 2012:
“We also anticipate that the 2013 financial year results will include a number of one-off costs, amounting to approximately $15 million before tax”…”The overall results will be skewed to the second half of the financial year as the first half is expected to be impacted by prevailing market conditions.” Three months earlier we had read the phrase: “whilst maintaining similar operating margins.”
Through a more careful analysis, investors could infer that the outlook for the company may not be a rosy as once thought. This is not to say that they should make immediate changes to their invested positions, but a rare signal that required further scrutiny and analysis was now publicly available.
The best part of this process is that the majority of investors will not undertake this higher level of due diligence. Whilst more work may be required, more information will result, and more information tends to create better investment decisions and likewise better portfolio returns.
So without being a Chartered Accountant or a Chartered Financial Analyst, all investors have the ability to deep dive into the words and statements of the companies in their portfolio. It’s a simple trick but it can vastly improve performance over the long term.
Ausdrill (ASL) Share Price from Start of 2012
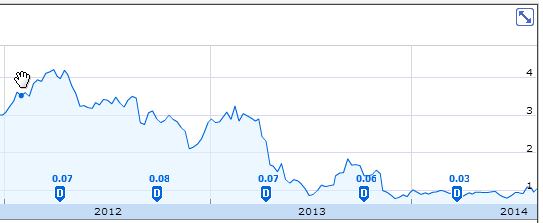
Source: Google Finance. 'D' and an amount signify payment of a dividend.
David Buckland is the Chief Executive Officer of Montgomery Investment Management. Montgomery Investment Management did not own Ausdrill during the periods mentioned within this article, and has not owned it since.