Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 343

The fear of running out of money in retirement

In the middle of yet another review on superannuation, this time looking at the retirement income system, it is important to capture the views of the people the system is meant to help. Challenger has partnered with National Seniors Australia since 2012 to form a better understanding of how Australian retirees (and older Australians not yet retired) feel about life and their finances in retirement.

Lack of confidence in retirement

The latest report, Retirement Income Worry. Who worries and why? indicates that the system has more work to do to provide retirees with more confidence in retirement. The report found that most older Australians (53%) are worried about outliving their savings, with women (59%) more worried than men (47%).

This high level of worry contrasts with global comparisons that rate Australia as one of the best retirement income systems in the world. This isn’t simply a case of Australia being the best of a bad lot. The underlying issue is that despite the many strengths of Australia’s super system, people worry whether they have enough, particularly approaching retirement.
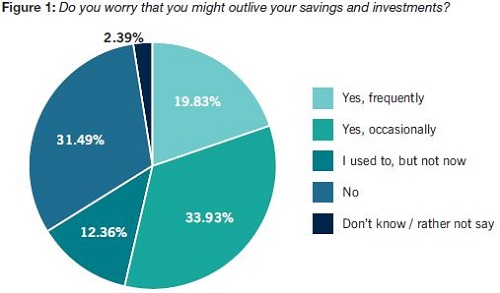
The report delves into the underlying factors leading to worry. Gender differences are significant. Women are more likely to worry about running out of money in retirement than men. And, by 'running out of money', people are talking about their super. While the age pension is a backstop for people who run out of super, respondents were worried that it might happen to them. Living solely on the age pension is viewed differently from having your own money to spend.

People with less than $500,000 were more likely to worry than those with more. There are more women with lower balances as a result of broken lifetime work patterns, part-time arrangements and the gender pay gap. The report also notes that women with higher balances were more likely to worry than men with the same balances.

Longevity differences not addressed

The difference in life expectancy could also impact the level of worry in women. On average, women live 2-3 years longer than men, and half the women who turn 66 in 2020 are likely to live into their nineties. The standard retirement income options in super don’t deal with this longevity and this seems to cause many to worry about their money running out.

It follows that retirees with a guaranteed source of income for life (from either a defined benefit pension or a lifetime annuity) were the least worried.

The evidence points to the need to improve the super system to keep it world-leading. The current government focus on designing better retirement income products will help as would other tweaks that haven’t received the same traction, such as removing the $450 threshold on compulsory super payments.

Better adjustment in retirement

On the positive side, once people retire, they report less worry. People tend to adjust to what they have and to actual retirement. It implies that some people are working only because they are worried about not having enough.

The survey also reinforces the idea that retirees know that super is for spending. Almost two-thirds of the respondents who had been retired for at least five years expect to spend most of their savings over the next 20 years. Super was created as a consumption-smoothing mechanism. Participants defer wages as a sacrifice during their working lives, so they are entitled to spend those unspent wages (compounded many times over) on themselves in retirement.

Summary of major results 

In brief, the degree of worry about retirement income was:

1. 68% higher in those not already retired. Previous work has indicated that people adjust to their actual circumstances in retirement, whether they planned for them or not.

2. 65% higher in those who have less than $500,000 in savings. This is as expected, since they may not have the money to pay for a ‘comfortable’ retirement.

3. 53% higher in those who expect their main source of income in retirement to be the age pension. This is expected because it is a minimum basic income with accompanying worry about ‘making do’.

4. 47% higher in women. This is after taking out the effects one or more of the previous three factors above and may be associated, in part, with expecting greater involvement in caring roles and a real risk of outliving their partners.


Jeremy Cooper is Chairman, Retirement Income, at Challenger. The full report can be downloaded from the National Seniors website.


  •   5 February 2020
  • 5
  •      
  •   
5 Comments
Aussie HIFIRE
February 05, 2020

None of this is particularly surprising news. People with less money worry more about running out of money. People who are reliant on the government are more worried because they're not in control of their main source of income. Women tend to have less super for a variety of reasons, and so they worry more than men. People who don't have much money figure they will spend most/all of it over the next 20 years.

Putting some numbers around all of this is nice, but really it's just confirmation of what you would assume anyway.

john
February 05, 2020

One sector sure has no fears of running out of money in retirement with all their high salaries, multiple perks, high pensions etc. That is the politicians !!

Jeff O
February 05, 2020

The vast majority of retirees should not worry about running out of money or making do - especially those that own residential property. Currently, retirees with residential property - die with 90% of their assets - over save and underspend during retirement and effectively make large bequests on death.

Arguably, the best financial strategy for the majority (the median) of retirees, with residential property that are cash strapped but asset rich is the top up the govt's aged and/or private pension with the govt's pension loan.

Retirees can add up to 1.5 times the aged pension - as a regular income stream (effectively, a private/public annuity - paid by the govt backed by the private savings/equity in your home.). A couple with most of their private savings locked up in residential property can readily lift their income to a 'comfortable' level!

The income stream is capitalised at the administered rate of 4.5% - it's effectively a flexible reverse lifetime mortgage with very little equity or credit risk or longevity risk! The longevity risk can be managed by setting a low nominated loan amount, with the free govt option of regular reviews and even earlier repayment!

Of course, the PLS does not help retirees that do not own a home and/or an investment property. This needs other govt. policy action.

PS - It would also further increase retirement incomes and reduce worry for asset rich, income short retirees - if the pension loan rate was offered by the Govt at a "market" rate - arguably 3.5% currently - backed by efficient funding, effective delivery and disinterested advice!

Indeed, with scale (and scope), the PLS has the potential to be good for jobs and growth - unlocking the voluntary savings in residential property, the biggest component of Pillar 3 - boosting the spending of older Australians and in turn creating jobs and growth for younger Australians.

Jeff O
February 05, 2020

The vast majority of retirees should not worry about running out of money or making do - especially those that own residential property. Currently, most retirees with residential property - die with 90% of their assets - over save and underspend during retirement and effectively make large bequests on death.

Arguably, the best financial strategy for the majority (the median) of retirees, with residential property that want additional income to spend or put aide for an unexpected financial emergency is the top up the govt's aged and/or private pension with the govt's pension loan scheme.

Retirees can add up to 1.5 times the aged pension - as a regular income stream (effectively, a private/public annuity - paid by the govt backed by the private savings/equity in your home). A couple with most of their private savings locked up in residential property can readily lift their income to a 'comfortable' level!

The income stream is capitalised at the administered rate of 4.5% - it's effectively a flexible reverse lifetime mortgage with very little equity or credit risk or longevity risk! The longevity risk can be managed by setting a low nominated loan amount, with the free govt option of regular reviews and even earlier repayment!

Of course, the PLS does not help retirees that do not own a home and/or an investment property. This needs other govt. policy action.

PS - It would also further increase retirement incomes and reduce worry for asset rich, income short retirees - if the Govt's pension loan rate was at a "market" rate - not 4.5% - arguably 3.5% currently - backed by efficient funding, effective delivery and disinterested advice!

Indeed, with scale (and scope), the PLS has the potential to be in the national interest - for jobs and growth - unlocking the voluntary savings in residential property, the biggest component of Pillar 3 - boosting the spending of older Australians and in turn creating jobs and growth for younger Australians.

Dave
February 06, 2020

Hi Jeff,
I agree and have come to the same conclusion regarding the PLS. My only issue relates to the 1.5 times the pension rate. I initially thought that it meant that I could borrow 1.5 times my pension, when in fact I can only borrow half of my current pension. I wish I could borrow more, and hopefully the Govt will increase the borrowing limit in the future,

regards Dave


Leave a Comment:

RELATED ARTICLES

Financial literacy for older Australians has gone nowhere

Schemes designed to deal with longevity risk

Overcoming loss aversion in retirement income

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Latest Updates

Superannuation

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Planning

The great wealth transfer myth

Why do some families preserve wealth for generations while others struggle to? As the great wealth transfer unfolds, the determining factor is often not the structure of the estate, but the preparation of those who will inherit it.

Investment strategies

What comes after bank hybrids?

For years, bank hybrids have been a cornerstone of portfolio income. With tens of billions of dollars now disappearing from the market, investors face a critical question: what comes next, and are the obvious replacements enough?

Investment insights from the US

What happens when knowledge becomes a commodity? The latest themes emerging from the US tech sector suggest AI could reshape company moats, disrupt incumbents and create winners and losers in unexpected places.

Investing

Can Berkshire thrive without Buffett?

Warren Buffett's departure marks the end of an era. But the more important question for investors is whether Berkshire's culture, discipline and capital allocation framework can survive without the man who built them.

Retirement

The Bengen 4% Rule: Lost in translation

For years, retirees have been told to focus on withdrawal rates. But the real question is far simpler: how many dollars can you safely spend? The answer may be very different from what conventional retirement wisdom suggests.

Interest rates

Super low interest rates came with side effects

For more than a decade, investors lived through an era of near-zero interest rates. With bond yields now surging, it's worth asking whether cheap money solved economic problems, or introduced a much larger set of risks.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.