Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 157

Investment objectives: are you max return or min risk?

If superannuation funds and other large investors decided to hold all their wealth in bank deposits, they wouldn’t need investment objectives. In practice, they want to achieve the best outcome to meet their needs. How do these investors choose between the myriad of investment alternatives such as different asset classes (e.g. equities versus fixed income), styles (e.g. value versus growth), structures (e.g. listed versus unlisted) and regions (e.g. Australia versus global)? By anchoring these choices in well-defined and articulated investment objectives.

How to set investment objectives

Setting investment objectives is not as simple as it seems. A menu of key considerations might look like this:
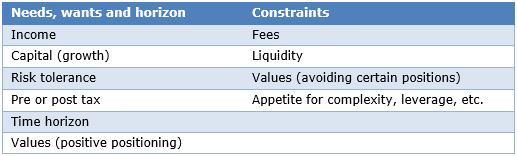
Values-based investing is a topical investment theme at present. Many large superannuation funds offer specific ‘Responsible Investing’ (or similarly named) investment options which allow members to express certain preferences regarding values such as exposure to fossil fuels, tobacco, gambling and cluster munitions. For some, values are a core, driving influence over how their capital is invested (a need or want); for others, it is an important second-order issue (a constraint).

One key challenge with setting objectives is the competitive tension between the multiple needs and wants an investor may have. An example of this is the ‘Comprehensive Income Product for Retirement’ (CIPR) triangle of needs and wants of a retiree investor as recommended to the Federal Government last year in the Financial Systems Inquiry: Final Report:
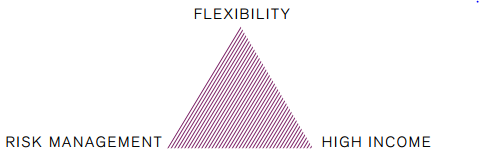
Source: “Number One With A Bullet: Adding Defence to a ‘CIPR’ Retirement Solution for Super Members”, Parametric Research, December 2015.

Conflicting objectives and revealed preferences

Each of these investment objectives is much easier to deliver in isolation than in combination. For example, an options strategy providing downside protection can be bought by a superannuation fund as part of a CIPR portfolio to help protect a pension member from loss of capital, providing a ‘tick’ on risk management. However, pricing on such strategies is typically quite expensive and could erode much of the income generated, jeopardising the high-income objective. The exercise of investment objective-setting therefore needs to include not just a list of the things important to the investor but also some sense of the weight of importance of each of the objectives. This then becomes an optimisation problem for the fund or investor to solve; that is, to find the optimal combination of those aims with those weights as specified by the investor. Optimisation is a good way to solve problems like this also because it is relatively easy to add the investor’s constraints.

The other key challenge in setting investment objectives is the possibility of revealed preferences. An investor may say they care about one thing when, in fact, their behavior reveals something different. The onset of the GFC showed a clear example of this. Though most superannuation members articulated a long-term investment horizon in which short-term results would matter little, superannuation funds saw high levels of switching from growth options like equities into ‘safe’ options like cash. There is a challenge here for investors to examine their beliefs in the course of setting investment objectives. If I ask for a fossil-free portfolio, will I really be happy if my portfolio underperforms a market-cap index with no fossil fuel screens? If I ask my manager to beat the ASX 200 and the ASX 200 returns -4%, will I really be happy if my manager delivers -2%?

Max return v min risk

If institutional investors do just one thing as they set investment objectives, my recommendation is to use a distinction set out by JANA’s former Chair and Head of Investment Outcomes, Ken Marshman, in its January 2013 Capital Market Insights brief: determine whether the investor is a return maximiser for a given unit of risk or a risk minimiser for a given unit of return.

‘Max return for risk’ investors – typically including accumulating superannuation funds and other diversified portfolio investors – will craft investment objectives by defining a risk budget and then exploring what is possible in terms of returns and other outcomes. On the other hand, ‘min risk for return’ investors – typically including charities, defined benefit funds and many family offices – will more likely start with required capital and yield objectives and then look to mitigate the undesirable consequences of targeting these return objectives.


Raewyn Williams is Director of Research & After-Tax Solutions at Parametric, a US-based investment advisor. Parametric is exempt from the requirement to hold an Australian Financial Services Licence under the Corporations Act 2001 (Cth) in respect of the provision of financial services to wholesale clients as defined in the Act and is regulated by the SEC under US laws, which may differ from Australian laws. This information is not intended for retail clients, as defined in the Act. Parametric is not a licensed tax agent or advisor in Australia and this does not represent tax advice. Additional information is available at www.parametricportfolio.com/au.


  •   26 May 2016
  • 7
  •      
  •   
7 Comments
David
May 27, 2016

How do trustees of an institutional fund know what the objectives of their clients are? For example, I think this whole ESG issue is overdone, and I would not want my fund compromising returns based on someone else's view on 'the right thing to do'. My ethics are not your ethics.

Warren Bird
May 28, 2016

David, I sort of agree with you - in a fund that has many investors like a super fund, the ethics of members are likely to be different and thus ethics is difficult to bring into the decision- making. Ethical funds struggle in the public offer space for that reason. I manage a very large ethical fund, but it's for one client (the Uniting Church) who defines the ethical principles that are to be implemented and is very happy with what's being excluded and what's being emphasised.

However, The ESG that most funds are looking at is not "ethical". Rather, it is an explicit recognition that environmental, social and governance factors create potential risks that it is prudent and appropriate to take into account. You don't have to believe, for example, that cheating on emissions tests for the sake of marketing your vehicles is wrong behaviour, but fund managers who saw governance risk at VW were ahead of the game in being out of or underweight that stock when the proverbial hit the fan. Why would you not want a fund to be thinking about such risks?

I wrote more about this in an article for cuffelinks last October, so won't go into more detail here on the different approaches to ESG, but would ask one question. Why do you think that ethical investment approaches have to underperform? Do you think that companies that cheat, or deceive or engage in activities that are harmful to people or the environment are going to be the best performers and that you'll miss out on great returns by not owning them? sure there are, for example, gambling companies that make money. But why do you think they will outperform the rest of the market? The evidence is fairly clear that they don't, except perhaps for brief periods. Well run unethical companies tend to return in line with the market over time at best.

At a more macro level, the ethical benchmark that we at Uniting Financial Services use has outperformed the ASX 200 and 300 over the past five years. That's not a sufficient bit of analysis to prove that ethical returns are better or worse, but it is supportive of the hypothesis that our exclusions don't underperform the rest of the market.

Some people point to poorly performed ethical funds, but the reality there is that it wasn't the ethics of their decisions that caused underperformance but poor stock picks within their universe - exactly the same as with funds that don't have ethical screens.

Therefore, institutional fund trustees who decide that it is appropriate to invest using ESG principles are not automatically creating an underperforming situation as you assert. They are seeking, rather, to invest with their eyes open and their prejudices locked away.

Peter Lang
May 31, 2016

Ethical investing is all about irrational personal and ideological beliefs. It's mostly irrational and much of it is just plain wrong. For example, it is irrational and unethical to not support coal and uranium. Nuclear power is the safest way to generate electricity. Those who do not know this are misinformed. If not for 50 years of anti-nuke scaremongering, 4.5 million fatalities would have been avoided globally in the past 30 years. If not for fossil fuels, billions of lives would have been lost. If not for coal exports now and in the future, people will remain in poverty longer and tens of million more fatalities will occur as a result. This is what the irrational, unethical, immoral "ethical investors" are achieving.

Peter Lang
May 31, 2016

Raewyn Williams and Cuffelinks,

Thank you for this very relevant and important article.

I have a problem with this and other articles on portfolio risk management for SMSFs. My problem is with how the term "Risk" is used. I interpret 'risk' is being used here as a measure of volatility. However, I think that is a misleading and incorrect use for SMSF portfolio risk management. Risk is consequences multiplied by probability the consequence will occur. I suggest the consequence is that the SMSF will run out of money before the members die or the annual pension amounts will be insufficent to maintain the standard of living the members expected.

I like to view probability distribution charts of the the portfolio balance and of the annual pension amounts through to age 100 years with different mixes of portfolio asset classes. These use long ther historical returns data, such as from the well known Andex data (e.g. the Vanguard Charts), Bralisford's data for Australia since 1983, etc. Data specific to the SMSF members is input.

Volatility is not my primary conccern. My primary concern is that the SMSF will be able to pay the real value of our current pensions until we die. Since we don't know when we will die, I wan to plan for the SMSF to continue topay the current real value of our penstion to age 100. Are there free or low cost products available that can do this?

Ramani
June 01, 2016

Peter,

Surely you exaggerate (or jest) when you describe ethical beliefs as irrational personal ideological and ultimately immoral.

All human beliefs are personal, and in a given framework, rational. Thus, minimising animal cruelty while eating them, not supporting oppressive child labour, eschewing bonded or slave workers, dominating the vulnerable because one can - might be irrational nonsense for those who perpetrate them, but not if you are the at the receiving end.

As we have evolved, our framework has too, thus making past practices no longer acceptable.

Where people are free to think, this includes the freedom to think what others consider irrational (e.g., religions). In investments, just go with what closely aligns with your own (irrational) beliefs. If no such vehicle is available, create one.

Peter Lang
June 04, 2016

Ramani,

Do you believe it is ethical to support policies and investment decisions that cause large numbers of premature fatalities per year?

Policies that inhibit cheap electricity generation are doing just that. Anti-nuclear activists and policies have caused 5 million or more premature fatalities globally in the past 30 years. Anti-coal policies are retarding the rate people are lifted out of poverty. Most rational people would consider such policies to be unethical if they understood the consequences of them. The people who advocate for such policies are mostly either ignorant the real effects, gullible and/or ideologues.

Ramani
June 04, 2016

Peter, I do not believe in selectively attributing incidental outcomes to well-meaning people driven by conviction, any more than I would sheet home electrocution deaths (accidental as well as US style justice) to those who advocate its day to day merits. We do not hold coal lobbyists for coal-related lung diseases, however causative.

In the extreme, you could hold parents bringing kids to the world responsible for their eventual death on the 'but for' argumentation. Normal society does not work this way.

If the Amish avoid modern contraptions, or monks live by self-inflicted poverty, that is their fringe choice. Not immoral nor unethical, in my book.


Leave a Comment:

RELATED ARTICLES

How family offices differ from institutions

How risky are bank hybrids and are they misrepresented?

What do fund managers mean by Quality Investing?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.