Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 508

Market turbulence shows strength of Australian bank T2 bonds

Hybrid securities have gained popularity among Australian retail investors over many years, though that was shaken when the AT1 hybrids of Credit Suisse were wiped out in March 2023. What's been overlooked though is that the Credit Suisse tier 2 (T2) bonds were not written down. And that strengthens the investment case for the superior quality of Australian bank T2 (subordinated) securities.

Since the forced merger of Credit Suisse and UBS, and the subsequent full write downs of Credit Suisse’s AT1 hybrid securities, market volatility has settled. However, while $A major bank AT1 spreads have pushed out by about 0.5% (50bps), they still appear expensive compared to their USD and EUR denominated equivalents.

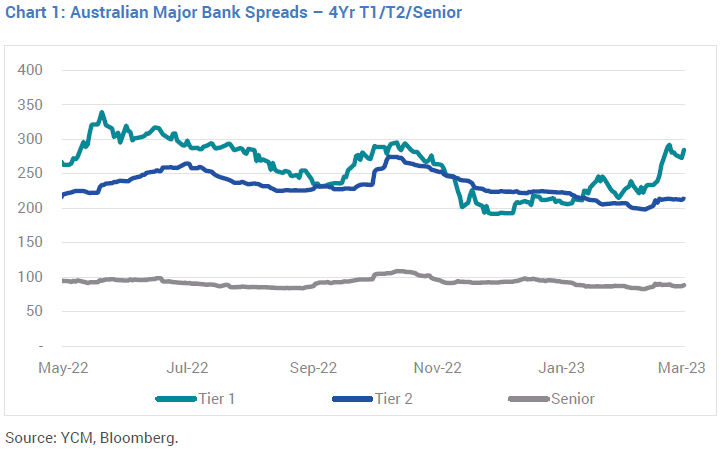
Moreover, $A, AT1 hybrids are also expensive compared to their T2 subordinated debt counterparts, with only about 0.5% (50bps) in additional margin (refer Chart 1), offering poor compensation for inferior credit quality and, no matter how implausible in Australia, the higher probability of impairment in a non-viability scenario.

Recall that AT1 is lower in the repayment waterfall than T2 and investors should be compensated for the higher risk. The more appropriate AT1 spread for the additional risk remains roughly twice that of T2, akin to where offshore AT1s currently trade.
It’s worth providing a reminder of exactly what happened to Credit Suisse debtholders. While the Credit Suisse AT1s were zeroed, their T2 securities were protected and rolled into the newly merged Credit Suisse/UBS entity at par. This distinction is incredibly important, since Australian major bank T2 securities sit at the top of a large regulatory capital structure, protected from impairment by Common equity tier 1 (CET1 ~11-12%) capital and AT1 (~1.5-2%) capital (refer Chart 2).
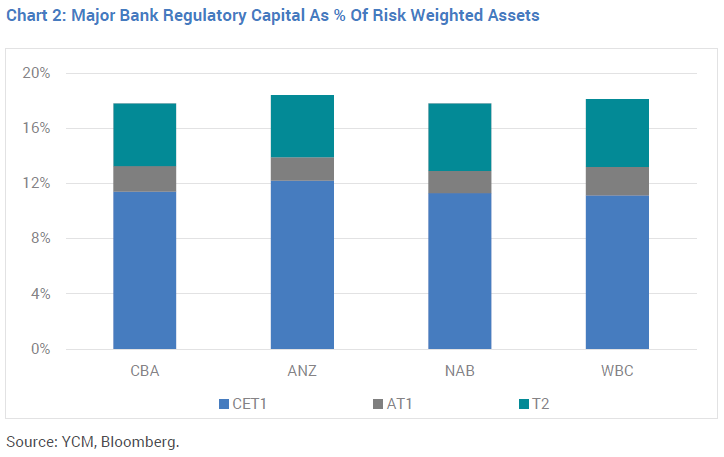
From a capital perspective, T2s have been de-risked in recent years, with total Tier 1 capital (CET1 + AT1) increasing by ~4% since the GFC. When we include the ~1-2% of earnings buffers which can be redirected to capital replenishment, T2 securities look safe today from impairment, given they are protected by ~14.5-15.5% in subordinated capital and earnings.

With their current ~6.0% yields, Australian major bank T2 securities remain important overweights across all our diversified Australian credit portfolios. Not only are they contributing significantly to income levels, but they are also well placed to provide capital growth opportunities when spreads eventually contract from current high levels.

Call risk has diminished for bank T2

Finally, we see the latest volatility as having positive implications for T2s, with call risk now significantly diminished from what the market speculated a mere six months ago.

Investors may recall APRA stating its desire for financial institutions to consider not calling T2 securities due to credit spreads being wider than historical levels. Not calling T2 securities would generally extend their life for a further five years and lower valuations.

After the recent bank failures in the US and the Credit Suisse/UBS merger, the argument of whether APRA will or won’t permit T2 calls now seems somewhat redundant. This was further reinforced recently with APRA approving yet another supposed ‘non-economic’ call for BOQ’s T2 securities which is likely to be replaced by a new T2, likely to be ~100bps more expensive.

Not enabling T2 calls on mere higher spreads would risk far greater economic damage in the current environment and appears to be off the table even though, as we noted at the time, APRA’s initial argument held little merit.


Phil Strano is a Senior Portfolio Manager at Yarra Capital Management. This article contains general financial information only. It has been prepared without taking into account your personal objectives, financial situation or particular needs.

Yarra’s overweight positions in T2 underpin the running yields on offer in the Yarra Enhanced Income Fund (5.9%) and Yarra Higher Income Fund (6.8%) portfolios.


  •   10 May 2023
  • 1
  •      
  •   

RELATED ARTICLES

What's next for bank hybrids?

Is the best value for Australian credit not in Australia?

Replacing bank hybrids with something similar

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.