Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 30

Not all lifecycle funds are created equal

As the dust begins to settle on the MySuper product landscape (albeit with more rolled out until the end of the year), many have adopted a lifecycle strategy. And while retail groups seem to have dominated the push down this path they are not alone, with both corporate and industry funds using a lifecycle approach. However, not all lifecycle funds have been created equal. There are a number of key features which distinguish the different lifecycle offerings and they can have a significant impact on member outcomes.

Previously I have been a well-informed fence sitter on lifecycle funds (see “Are lifecycle funds appropriate for MySuper products?”). If pushed harder and given only a strict choice of whether or not to take a member’s age into account when designing their underlying investment exposure, I would side on doing so. My greatest reservation remains that there are so many other personal factors to consider that lifecycle funds could be the intermediate technology before we develop a superior approach (some groups are already well down this approach which I call ‘mass personalisation’, particularly overseas). Undoubtedly, good advice based on someone’s detailed personal situation usurps all systematic approaches, but is not a realistic proposition for the entire working population.

Here is a guide to the ‘Big 4’ differences and their impact. These issues are not isolated to Australia – these differences also occur in the US where lifecycle funds have greater prevalence:

1. The shape of the glidepath

The ‘glidepath’ is a simplified summary of the asset allocation through time. A glidepath is generally presented in terms of exposure to growth assets given age and typically steps down as retirement approaches, as shown in Diagram 1 below. The timing and size of the reductions vary, and as a result, these products will produce different lifecycle outcomes for their members. There is no exact answer on what is the optimal glidepath. All we can do is assess the research and reasoning that has gone into the design of specific products. One specific issue is whether the product is designed with an accumulation objective in mind or whether it is designed to roll into a specific allocated pension product with a complementary asset allocation – this is known as the ‘to versus through’ debate.
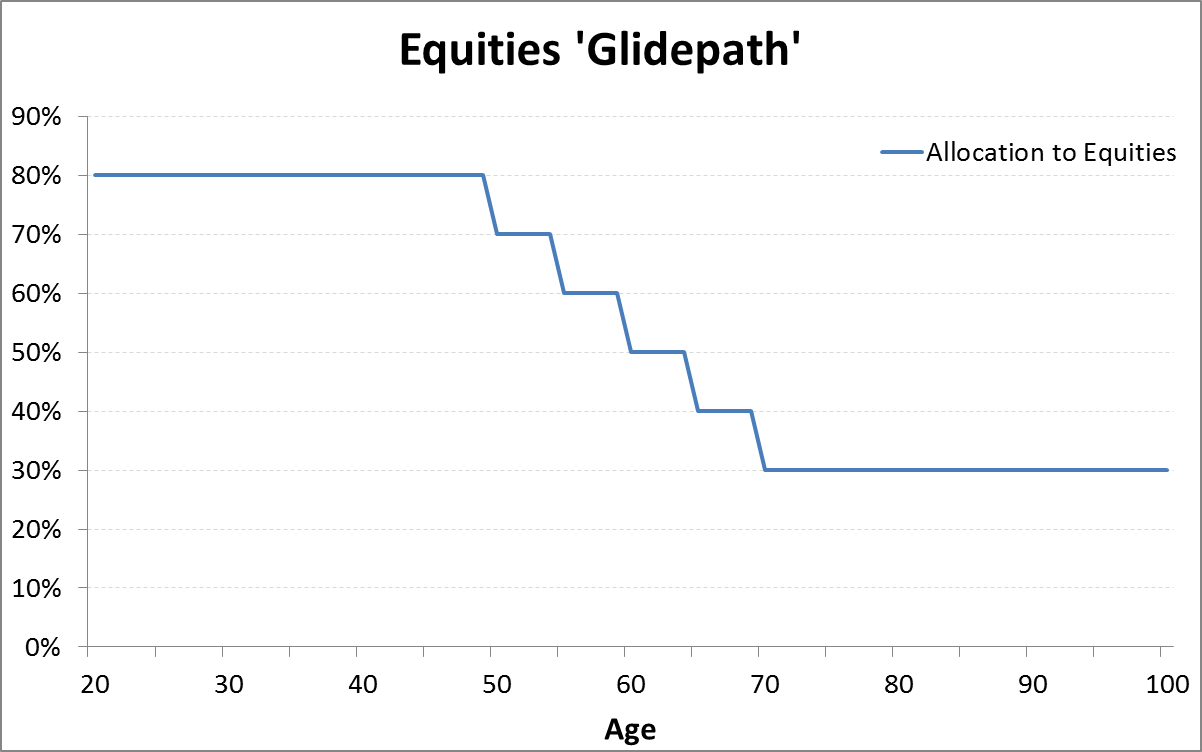
Diagram 1: Example of a glidepath.

2. Age cohorts (buckets) or personal administration

There are two options to administer the glidepath asset allocation. One is to group people into age buckets; each member of that cohort will have identical asset allocation. This is the most common approach, for example those born in the 1970’s, 1980’s, 1990’s, 2000’s etc. An alternative is to administer the lifecycle approach to each member individually. The latter approach has benefits – specifically, it avoids giving people at the extremes of a cohort group the same asset allocation. For example, in some products you may have a scenario where someone aged 51 and 60 have the same asset allocation. There is a risk that cohort or bucket administrative approaches dilute much of the complex calculations that have gone into the glidepath design.

3. Glidepath smoothness

Some glidepaths will make many small re-allocations over time while others may take a smaller number of large steps. This latter approach makes a sizable asset allocation switch regardless of the market fundamentals. Imagine a scenario where shares have fallen heavily and now look attractive but concurrently a lifecycle fund glidepath may reduce exposure to growth assets, locking in losses and removing the ability to participate fully in a recovery. This issue interacts somewhat with (2). A cohort approach with large steps can have a greater impact on lifecycle outcomes than a personally-administered approach with small increments.

4. Active asset allocation

Active asset allocation has become more prominent among super funds, particularly post-GFC where it became obvious that active management within underlying funds provided only a small buffer in difficult market environments. We can see the merit of active allocations in a lifecycle strategy where, as described in (3), transitions may occur at inappropriate times. Of course there is no guarantee that such an approach will work – not all active asset allocation capabilities are created equally either!

These are the Big 4 issues, but there other differences are emerging. Some groups are already considering how best to structure exposure to underlying asset classes through the lifecycle. Again the US provides good guidance to latest market trends. The design of lifecycle funds could be based on administrative capabilities (personally administered approaches likely cost more than a cohort approach), cost, research resources, and even a desire to keep it simple so that underlying members understand what is going on.

Difficult to compare and rate funds

The design of a MySuper fund, where we have balanced funds and a range of different lifecycle fund designs, is a difficult area for an individual to assess. In front of each product there will be smart marketing messages. It is important that those groups who rate super funds are well-equipped to assess different super fund designs. They face a big challenge. Previously they compared funds, the large majority of which adopted a balanced fund approach, and this made for relatively easy performance comparisons. Now there is an extra dimension – fund design and member outcomes. Will these groups perform a deep assessment of the fund design, perhaps using proprietary tools to enable an objective comparison (and cut through the marketing materials), or will they just assess the high level issues considered in the design?

With MySuper we move into an age where the lifecycle approach is more prominent. Be aware that not all lifecycle funds have been created equal. It will be fascinating to watch advancements in this space, and how the groups which rate super funds adapt to the new environment.


  •   6 September 2013
  • 4
  •      
  •   
4 Comments
Alun Stevens
September 08, 2013

The lifecycle approach has indeed been adopted by a number of, mainly, commercial funds. Before discussing the various methods for operating them, it is worth reflecting on the benefits and problems of lifecycle funds as a class. The only benefit promoted for these funds is that they de-risk members in the run up to a nominal retirement date and the promotions generally reflect on the impact of the GFC for people retiring at that time. The lifecycle funds supposedly reduce or remove the sequencing risk.

The biggest problem with the composite (ie asset allocation is managed within a composite investment option) is that they don't actually de-risk the investment exposures of these people and do very little if anything for the sequencing risk for those people to whom it is important. They can be plausibly promoted as doing so, but they don't actually do so in practice. Two simple examples at opposite ends of the spectrum of potential client needs demonstrate this. Firstly, someone with a relatively small balance. The comprehensive data I have from most of the largest funds in the country show that this person will almost certainly cash the benefit in - either to take the cash or to move the cash somewhere else like an SMSF or other fund where their main benefit is.

A glide path investment portfolio will reduce the risk of a significant loss by a marginal amount because the assets will still be held in a composite portfolio with quite marked volatility risk. If someone wanting to take their benefit in cash had been invested in one of these portfolios at the time of the GFC, they would have still suffered a material loss because of the need to sell down depressed underlying assets which will still comprise a material proportion of the assets. The lifecycle fund will have failed spectacularly in its primary objective.

As a second case let us consider someone with a much bigger account balance who will be relying on their assets to deliver a retirement income for the rest of their life. They will have short term cash flow needs and a significant long term need to grow their asset base to keep up with inflation. The lifecycle approaches significantly increase the long term growth risk (and thereby also the longevity risk) while (as discussed above) doing virtually nothing for the short term liquidity risk. The long term risk is increased specifically because these funds depress the long term earnings potential too early and too much all in the name of nominally managing short term volatility risk.

Lifecycle funds either increase or do nothing for the risk at both ends of the spectrum for members - and therefore do nothing in between either. They are not a risk reducing tool for members.

The only risk they actually reduce is the risk to trustees from disgruntled members. Trustees have virtually no risk of being sued for under performing over the long term because potential claimants will be very old and their supposed loss will be impossible to quantify. The only real risk they have is being sued inn circumstances like the GFC and would then be able to stand up and show that they had recognised the issue and had done something to remedy it - ie not negligent.

The fact of life is that members near and in retirement generally have two risks - short term asset value risk against their short term cash flow liabilities and long term growth risk against inflation. These two risks simply cannot be managed by a background funds management solution. It is essentially impossible. One can naturally do the maths and match assets and liabilities of the total membership group via a composite portfolio optimised to a particular volatility requirement. Unfortunately this portfolio is guaranteed to be suboptimal for every member (unless of course they all have exactly the same liability profiles). Or to put it another way, lifecycle funds are wrong for everyone.

David O'Donnell
September 10, 2013

Well put Alun. I particularly like the line that sums up the deficiency that the lifecycle fund concept fails to address, 'The fact of life is that members near and in retirement generally have two risks - short term asset value risk against their short term cash flow liabilities and long term growth risk against inflation.'.The 'lifecycle fund' concept has simplistic logic, but my opinion is that that it trivialises a task that is not that simple. I wonder if it even reduces potential causes of action by members against trustees, with your examples illustrating clear deficiencies that again in my opinion could be seen to be clearly negligent on the part of an advisor/trustee.

Alun Stevens
September 10, 2013

The only claims that are likely to be lodged against trustees are in respect of falls in asset values near to retirement. Those who under perform against inflation for 20 years will find it very difficult to argue that it was the asset allocation decisions 20 years earlier that caused them a loss. They will in fact find it very difficult to quantify a loss. No real causal link + no quantification of loss = no claim.

Against the first type of claim lifecycle funds give trustees a defence in that they can show that they considered the problem and took action and that action was endorsed by professional advisers. Very difficult to prove negligence or liability against this type of defence.

John Hewison
September 12, 2013

Alun, you can't see me but I am standing in my office applauding your thoroughly rational and accurate appraisal of the new fad of lifecycle investing.
So as an industry, we have decided to abandon the traditional "risk profiling" compliance protective model (which never worked) and we'll try the "one size fits all" age based lifecycle model instead.
When do we wake we up to the fact that we all have a responsibillity to design strategies to achieve defined outcomes for individual clients, work hard at re-balancing to the model and keeping close to our clients? Whoops sorry, that can't be commoditised can it!
Whilst I am at it, what about the issues of multi generational asset transfer and active cash flow management? What about the recognition that so called "growth" assets can also be extremely effective inflation hedged cash flow assets? I guess this gets lost somewhere in the lifecycle model.
When advisers are looking for ways to demonstrate value-add to their clients, surely these are the factors that make the difference.


Leave a Comment:

RELATED ARTICLES

Rob Prugue’s spiritual super journey

The state of play in the funds management industry

Why we overlook lifetime annuities

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.