Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 160

Online broking: same game, different players, lower cost

Online stockbrokers are in a new phase of disruption not seen in over a decade and they’ll have to move quickly to stay ahead of the game or risk losing their customer relationships.

A wave of new ‘fintech’ is the catalyst for this change but it’s not the robots and cryptocurrencies that are causing the disruption. It’s the resulting changes in consumer behavior and expectations that are forcing online brokers to redefine their business. Online brokers have always been more consumer-focused than their institutional counterparts but they still struggle to innovate beyond the technical aspects of their craft. This is where fintechs are starting to redefine the game for the industry, particularly regarding information, research and advice. These entrants have paved a new path for equities that is changing the way that consumers want to trade, leaving online brokers in a strategic minefield.

Investors are doing it differently

Products such as Simply Wall St, Livewire, StockLight and Cuffelinks are all redefining the way that investors find and research investment opportunities and strategies and make trading decisions. Twitter and HotCopper are in the tool box of many investors, and StockTwits will no doubt make its way to Australia in the near future.

Furthermore, as Google has improved its quality measures of content, online publications have been forced to produce high quality original content, making them a great source of insight. The significance of this shift is that investors are less likely to be using their online broker as the primary source of information for trades.

A sample of over 10,000 users of Canstar’s online share trading comparison table showed that only one in four were refining their results based on broker recommendations, access to company reports or daily market updates. This could mean one of two things: either investors are automatically expecting those services as part of the platform or investors aren’t looking to their online broker for recommendations and market information. In either case it suggests that broker-generated content may not have the same impact that it once did on investor behavior.

In contrast, according to Andy Rogers, Head of Stockbroking at CMC, their most popular online resources are the Morningstar quantitative reports and theScreener equity reports:

“Having multiple sources of information for clients to review and cross reference means they feel more confident about validating their investment and trading decisions”.

My hypothesis is that investors will eventually complete most of their primary research off-platform and use the on-platform data as a sanity check or to fill in the gaps. Perhaps what was once a competitive differentiator is now a hygiene factor in this ever-evolving investment information landscape.

Brett Grant, Head of Self Directed Investing at nabtrade, agrees that investor needs are constantly changing and becoming more demanding:

“Innovative and relevant products, underpinned by a rich information experience, ease of use, smart device-accessibility and cost-effectiveness, will be the key determinants in consumers’ minds going forward when it comes to selecting a broker. Players in this industry will need to disrupt themselves and think big and yet be nimble to stay ahead.”

Mobile is crucial

Looking at the investing context alone will only tell half the story. Consumers have a life outside their bank accounts and this life is a major driver of the expectations they apply to financial services. Consumers want:

  • A simple mobile experience
  • Everything for nothing (or very little)
  • Immediacy

Right now you can decide to listen, on our smartphone or laptop, to almost any song ever recorded. You can either do this for free or pay a small monthly sum to bypass the advertising via a premium model. You can order a car to pick you up from your destination right now within three clicks (including opening the app), or four clicks if you want a quote for the trip. Just over a decade ago having a GPS in your car cost several hundred dollars, was on a 2D map and was out-of-date very quickly. Now you can street view Moscow’s Red Square from your mobile phone and navigate anywhere in the world for free. You can pay for your lunch by tapping your phone.

Anecdotally, mobile logins to trading platforms have taken off significantly in the past two years and 20-30% of total executions are now done via a mobile app (for those with a dedicated app). All providers in Canstar’s recent online share trading platform research had a mobile responsive website but not necessarily a dedicated mobile app. I would suggest that this should be a key focus for all providers in the coming years.

More for less

Conventional wisdom would suggest that with better features, new technology should come at a higher cost for consumers but in fact the reverse is true.

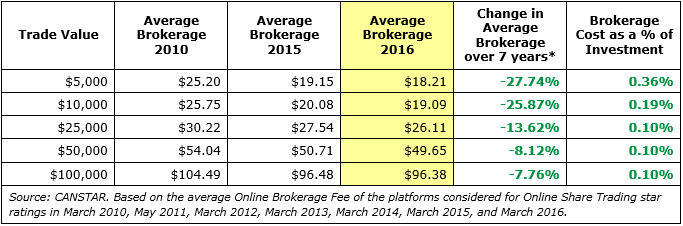
Canstar’s most recent research shows that the average cost of trading at all dollar amounts has fallen – in some instances quite significantly, over the past five years.
Lack of innovation will mean lack of customers. Failing to gauge both changing investor preferences and the level of fintech disruption will be a death knell for complacent companies. The next few years will be fascinating.


Josh Callaghan is General Manager, Wealth, with CANSTAR and Wealthbricks


  •   14 June 2016
  •      
  •   


Leave a Comment:

RELATED ARTICLES

To speculate or not to speculate

Technology and investing: this time may be different

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.