Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 558

The outlook for Nvidia, from a long-time investor

Nvidia is now the third largest company in the world. It is larger than Tesla, Meta, Alphabet, Amazon and Saudi oil giant Aramco. Despite this scale, the company grew quarterly revenue at +265% year on year as reported in its latest earnings call. The data-centre segment grew an astonishing +409% year on year. Even as we become strangely accustomed to Nvidia’s beats and raises, this kind of growth should in no way be perceived as anything even remotely resembling normal in the stock market.

Its size and speed, for a company this large, has not been seen in recent history.

Our history with Nvidia

Nvidia has featured in portfolios managed by Loftus Peak since the beginning of 2016. Back then, the share price was around US$8 (after adjusting for the company’s stock splits).

At the end of 2016, Nvidia’s data centre business had grown just +145% (!) year on year and accounted for 12% of total revenue (gaming was 60%). Nvidia was the graphics processing unit (GPU) specialist and it disrupted, in a way, the incumbent central processing unit (the CPU). By processing independent calculations in parallel, Nvidia offered a far more efficient hardware solution for dealing with large calculations.

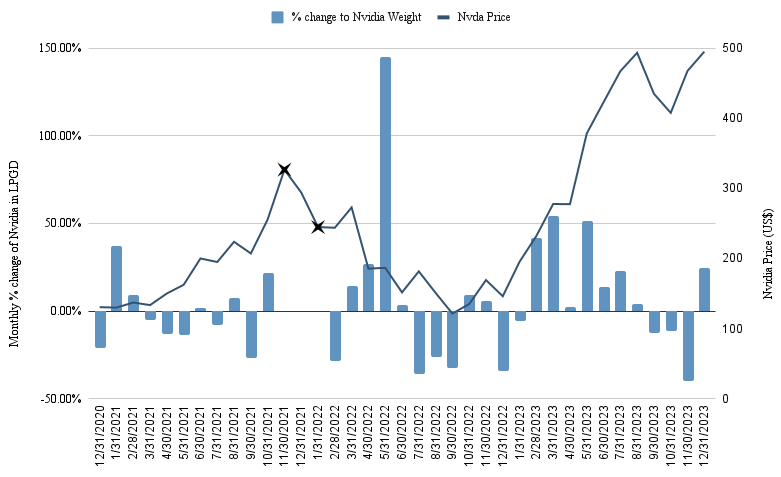
We held Nvidia as the company grew, powered by the cyclical gaming business and the secular data-centre business, of which Artificial Intelligence (AI) was a driver. We believed the company could grow revenues a little bit faster than 20% p.a. across the next five years. This was the basis of our investment between 2016 to 2022.

Figure 1: Using these assumptions, Nvidia featured in the portfolios we manage
Source: Loftus Peak

Nvidia went through our price target in late 2021 and we exited all together, up around 10x on initial entry price. The 2022 sell-off brought the company back into an investable range.

Then AI came along…

The nature of Nvidia’s disruptive edge has not changed since 2016. However, the demand for its cloud compute has exploded due to AI and Large Language Model workloads. This is the fundamental driver of the company’s incredible growth.

Figure 2: We understood the potential, but we did not expect the pace of growth
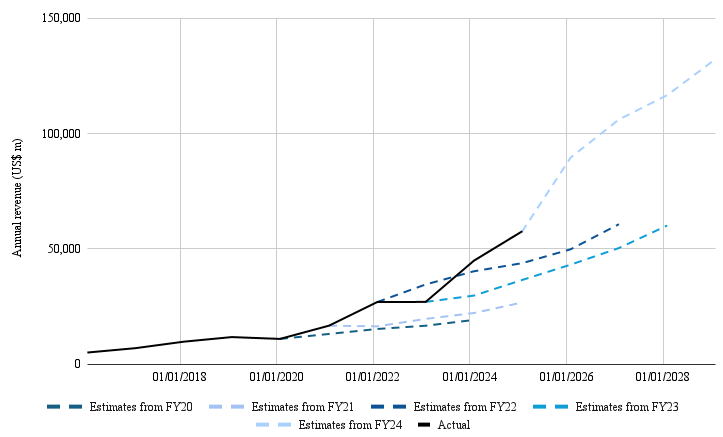
Source: BBG, note that the Nvidia financial year is eleven months ahead of the calendar year.

The translation of AI demand into Nvidia revenue became clear to us from February 2023. We increased our growth assumptions, our price target climbed and we lifted the company’s weight in the portfolios managed by Loftus Peak. After falling -50% in 2022, the stock grew +239% in 2023, and has approximately doubled in the 2024 year to date.

What comes next?

Commentators flit between euphoria and scepticism. To confuse matters further, projected earnings upgrades make the company appear as one of the cheaper semiconductor names on a forward P/E basis. Some cynics have acquiesced. This capitulation combined with the capex numbers from customers like Meta and Microsoft have fuelled Nvidia’s share price.

But for the Fund, investing in AI, in a risk-controlled way, requires some level of diversification.

This is because within Nvidia’s enormous growth numbers are the seeds of a downward move in the valuation. Nvidia is forecast to generate sales of around US$105 billion by the end of 2024 and US$127 billion by the end of 2025 – but this last figure implies a reduction in the growth rate from 100% to just 20%! Investing in AI therefore is very different to using AI.

This is the reason that the Fund holding in Nvidia has been cut by around half over the past 6 months. It is not because of scepticism on the AI roll-out, but because the share price as it stands better reflects the shape of that roll-out to come, and so is now less attractive.

Just to be clear, there is more value to be had from investing in AI. The hardware build we have seen should be viewed as a prelude to a usage and device boom which has yet to be captured, in a return sense, from other major players including Qualcomm, AMD, Apple and Alphabet among others.

But reducing the exposure to companies such as Nvidia provides more room to invest in other companies that we believe are more prospective and not so richly valued, and on which future returns will be earned.


Alex Pollak is Chief Investment Officer and Co-Founder of Loftus Peak. This article is for general information only and does not consider the circumstances of any individual. Loftus Peak Global Disruption Fund (ASX:LPGD) is available to investors on the ASX as an active Exchange Traded Managed Fund.


  •   1 May 2024
  • 5
  •      
  •   
5 Comments
Dean
May 02, 2024

There's certainly a lot to be said about Nvidia, just look at how the mag 7 are spending on AI infrastructure and how they are gearing up for the AI revolution. At the moment, there is only one game in town, with all roads leading to NVIDIA. It's an incredible time to be alive with accelerating computing and AI; who would have thought only one company would hold the keys to both revolutions? The Blackwell GPUs will be another gamechange and we haven't even mentioned software :)

Bobby H
May 03, 2024

It is mind boggling growth. It's interesting how many investors say that it's difficult to pick winners from the AI revolution and that we won't know for some time - well, Nvidia is already a winner, so congrats for riding that wave.

Ces
May 03, 2024

NVIDIA is the best of best. I purchased 5000 shares of NVIDIA back in 2015 and still keep on buying now at $850 plus). This company is going to be a 4 trillion company in the next 5 years. First mover advantage and the moat Jensen has created over the past 20 years makes NVIDIA unstoppable. Wait and see, Apple (they are so far behind in the AI race, stock has gone sideways for years) will be incorporating NVIDIA GPUs and Tim Cook will shaking hands with Jensen (as did Sam Altman). Cheers Ces

Tim
May 03, 2024

5,000 shares pre the 2021 stock split is now 20,000 shares. That's over A$26M worth of NVDA. Well played!!
Most say AI isn't even factored in to AAPL's price yet.

Ces
May 04, 2024

NVIDIA and AAPL had a bit of a fall out many years ago blaming each other for some faulty software, it played out in the courts. Moving forward.... Jensen (DaVinci) would love to incorporate Blackwell into the Vision Pro however AAPL does not do B to B and Cook wants to stick to being a consumer product (cut of your nose despite ya face LOL)... The developers conference is coming up, lets see if AAPL pull a rabbit of of the hat... They did do a billion dollar buyback...perhaps they will, who knows what they announce with AI at the conference, they certainly have not mentioned AI until yesterday when they announced their earnings.. I know one thing is for certain I'll keep on buying NVIDIA on the dips, to date have not sold one NVIDA share to date :-)


Leave a Comment:

RELATED ARTICLES

Opening Gates: AI is as revolutionary as the internet

High quality businesses are on sale

Have AI’s four horsemen arrived?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.