Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 208

Who pays if your apartment building catches fire?

The Grenfell Tower fire in London in mid-June was very tragic and resulted in 79 deaths. This terrible occurrence has highlighted the extremely negative impact that the choice of building materials can have. There have not been many significant advances in construction materials recently. The Colosseum in Rome was largely built with concrete, terracotta roof tiles were used on the temple of Apollo in Corinth in 700 BC, and plasterboard was invented in 1894. We see that due to the lack of advances in construction materials, a perception has developed that all building materials and construction techniques are safe and have been tested over centuries.

As a former building products analyst at a large US investment bank, I have more than a passing interest in construction materials. This article looks at the impact that plastic-based aluminium composite cladding may have on Australian direct property investors, and who is likely to pay the remediation costs when building materials go wrong. Past examples have shown that the home owner invariably has borne most of the costs for decisions that were not made by them.

What is aluminium cladding?

Cladding is added to a building to prevent rain from entering the building’s structure, to improve sound and thermal insulation, and in many cases to improve the exterior aesthetics of a building. Aluminium cladding consists of two thin aluminium outer layers bonded to a mineral fibre core such as polyethylene or polyurethane. The issue is that not all of the polymers used in the honeycomb core are fire resistant, and indeed some of the cheaper polymers used are very flammable.

If the polyethylene core catches alight, the aluminium skin acts as a chimney to accelerate the fire up the outside of the building. The composite cladding used on the building in London was responsible for the 2014 apartment fire at Melbourne’s Lacrosse building and a number of fires in Dubai. In the Melbourne fire, a cigarette left on a balcony table caused a fire to spread up the 13-storey tower in less than 15 minutes.

The prospects of Australian buildings catching fire

In the wake of the Grenfell fire, the Australian Society of Building Consultants estimated last week that there are 2700 buildings in Sydney utilising aluminium composite cladding, and 50% of the high-rise buildings built in Melbourne over the past decade also use it. The aluminium cladding commonly used in Australia and installed in Melbourne’s Lacrosse building is Alucobest, which is imported from China and is cheaper than fire-resistant aluminium cladding such as Alucobond.

While not all of the aluminium cladding used in these buildings is the flammable variety, investors owning apartments with non-compliant cladding may face significant remediation costs, dramatically reducing returns. In February 2016, the Victorian Building Authority (VBA) found that 51% of the 170 high-rise residential and public buildings around the Melbourne CBD had non-compliant external aluminium cladding. Paradoxically the VBA audit concluded that this did not pose a safety risk.

We would suggest that owners of apartments constructed over the past decade investigate whether the cladding used in the construction of their asset is of the fire-resistant variety. In the case of Melbourne’s Lacrosse building, owners of the apartments are still battling through the courts over who is responsible for the $15 million repair bill. Based on our crude calculations, this represents a bill of $100,000 per apartment, a significant sum for investors in an apartment building where two-bedroom apartments are being sold for between $400,000 and $500,000. Research indicates that apartments were sold off the plan for ~ $300,000 in 2010, so the remediation costs may eat up most of the capital gains.

Contaminated Chinese drywall (plasterboard) no longer used

Similar to the abovementioned Chinese-made aluminium cladding was the contaminated plasterboard used in residential construction in 100,000 homes in the US between 2001 and 2009. During the home building boom in the US last decade, there was insufficient local production of plasterboard, which caused builders to source Chinese-made plasterboard that also happened to be cheaper. The high levels of pyrite in the cheaper Chinese-made plasterboard resulted in the release of sulphur gas into the home, which is bad for respiration of residents and also causes corrosion of copper pipes in the walls. The remediation costs are quite significant at around US$200,000 to remove and replace the plasterboard on a four-bedroom home.

Despite major importers of the plasterboard being companies like the giant German building materials company Knauf, affected homeowners were eventually limited to claiming only a tax deduction after replacing the plasterboard.

Who pays? Leaky homes in rainy places

In New Zealand and British Columbia, changes to the building codes in the 1990s resulted in the uptake of building materials and construction methods more suited to the sunny Mediterranean, rather than the rainy South Island of New Zealand or Vancouver where it rains on average 160 days per year. The change resulted in buildings with minimal eaves to disperse rain and wrapped in a fashionable textured cladding such as stucco or fibre cement. As water gained entry into cracks in the building structure, the timber frames began to rot and mould developed.
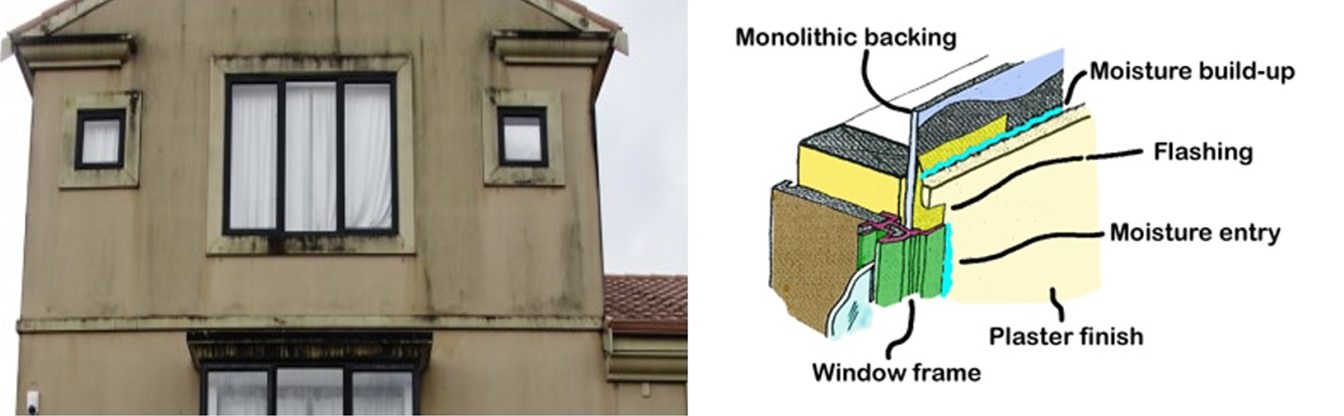
Despite the cause of these building calamities being changes to government construction policies, the owners of the buildings ended up bearing most of the costs of remediation. In New Zealand after many years of litigation and builders going into administration, a bailout package was put together. The costs were split with 64% covered by the property owner, 26% local council and 10% Federal Government. In Canada, the situation was even grimmer for property owners, with the best offer being an interest free loan and tax relief.

Owners are responsible

While many would assume that builders or developers would be responsible for replacing aluminium panels that are susceptible to fire, the above examples strongly suggest that owners of property with problem building materials installed are likely to bear the costs of replacement.


Hugh Dive is Founder and Chief Investment Officer, Atlas Funds Management. The Atlas High Income Property Fund has just been added to the ASX's mFund service.


  •   29 June 2017
  • 5
  •      
  •   
5 Comments
Ashley
June 29, 2017

So if 50%+ of new/refurbed buildings are non-complaint, what is the point of getting a DA/CC?

Stan
June 29, 2017

Very timely and a bit scary for any apartment owner.(Note,polyethylene and polyurethane are correctly identified as polymers after being incorrectly termed minerals)

DougC
June 29, 2017

The Australian Standards and adopted International Standards that specify the performance of building materials would, in printed form, take up many metres of shelf space and countless hours of reading. The Building Code of Australia applies to all of the several classes of buildings and are mandatory regulations. The process of reviewing and approving building design and construction is the responsibility of the relevant local authority (which is fairly routinely devolved to Private Certifiers).

The various regulations are particularly strict on matters relating to fire safety, including the combustibility and surface spread of flame of building materials and products. Fire egress and active fire alarm and protection systems are equally well defined according to building type. Buildings that comply with these requirements are fire-safe.

The recent fire disaster in London and prospective pending disasters there and elsewhere are due to non-compliance with those specified requirements which implies that the hazardous materials are not declared prior to building approval, or are not checked and disapproved, or are not inspected in the course of construction when, for example, they are substituted for approved materials. This is basically a problem of negligence for the sake of profit.

The recovery of costs should only lastly rest with the occupants and owners and should be borne by the one or more parties to the non-conformance.

Shawn Jewell
June 29, 2017

This Cladding problem could well be the Black Swan event for Apartment owners to attempt to sell and cause a massive drop in prices. I wonder how many Chinese Specufestors may be affected. Can't imagine thye are too keen to pay $100k on their "Saferty Deposit" dogboxes?

BB
July 03, 2017

And this is just one building defect! Never mind the countless others your building is likely to develop. talk about buyer beware, yet as a country of property obsessed investors we have a strange (and completely unsubstantiated) belief that somehow, someone, somewhere has 'checked' its all a-ok?

A real lesson here for Australian property owners! Just remember that local, state and federal governments of all persuasions are fiscally dependant on the revenues associated with property development and construction, in some cases it's not only the primary source of public funds, but the source of significant private wealth generation for those in public office as well. Bottom line, developers and builders will be protected at all costs (they have been to date and no empirical evidence suggests this is about to change)

Owners will ultimately bear the brunt of remediation costs followed by tax payers should a sufficiently dramatic and scandalous event force open the public purse.

Ah well, surely none of us actually believed all that 'jobs and growth' would be free?


Leave a Comment:

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.