Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 225

Quality ingredients improve both cooking and investing

The patient preparation of a home-cooked meal with carefully selected ingredients is a rewarding endeavor. Knowing what’s in the meal should make it healthier and well-balanced. Pre-packaged takeaway is convenient but usually less satisfying beyond the immediate need to relieve hunger.

Trends in investing are similar. Indices are essentially investment shopping lists prepared by someone else that save passive investors time and effort in deciding what to buy, or they give benchmark-aware fund managers a starting point to decide what to put in their trolleys.

Changes in investing habits

Yet in 2017, the number of stock market indices exceeded the number of stocks in the US, expanding the proverbial supermarket of investment ‘takeaway’ offerings.
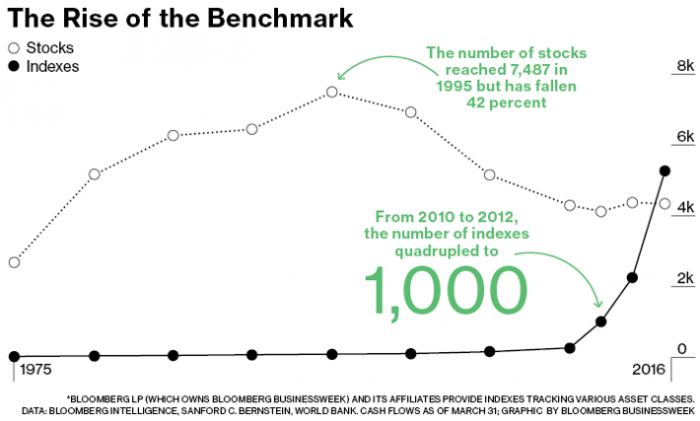
Source: https://www.bloomberg.com/news/articles/2017-05-12/there-are-now-more-indexes-than-stocks

What does it say about our investment eating habits when the number of shopping lists exceeds the number ingredients? In our rush to embrace convenience, are we losing sight of selecting quality underlying ingredients and carefully preparing healthy, well balanced portfolios?

Many products in the new financial supermarket are built on the assumptions and ‘theories’ of markets, including that humans make rational economic decisions and that price should always reflect the intrinsic value of the investment. Yet humans, and therefore markets, are not perfectly rational, particularly in the short term.

The 2017 Nobel Prize for Economic Sciences, awarded to Richard Thaler, recognised this as much, acknowledging his research which demonstrated,

“…that, unlike members of homo economicus, members of the species homo sapiens make predictable mistakes because of their use of heuristics, fallacies, and because of the way they are influenced by their social interactions.”

Holding period returns

Value investing, like cooking, should be an exercise in careful selection, patience and conscious avoidance of biases. To this end, compelling research released last year from active management academics Martijn Kremers and Ankur Pareek looked at the relationship between holding period (duration), degree of ‘activeness’ and returns for thousands of US retail and institutional funds over nearly three decades. This sample set included US equity retail mutual funds from the largest database of returns, the Centre for Research in Security Prices (CRSP), and a sample of all aggregated institutional investor US equity portfolios as inferred from their quarterly 13F statements. It covered a 24-year period from 1990 to 2013 for retail and 1984 to 2012 for institutions.

Among high ‘active share’ mutual funds, those with patient investment strategies (average holding periods of more than two years) were able to generate average alpha of 2.05% per year in the study.

At the other end of the spectrum, irrespective of how dissimilar their portfolios were relative to their benchmarks, highly-traded mutual funds with short stock holding periods underperform, with average annual net alpha of negative 1.44%.

The lesson is that active investors must have conviction and be patient. What is good takes time to prepare and is best savoured, not quickly devoured. And the key to the success of high conviction, patient value investors is, funnily enough, … valuations.

Valuations at time of entry remain key

According to Bank of America Merrill Lynch analysis from 1971 to today, valuations at the time of purchase have explained 80-90% of returns from the S&P 500 over a 10-year horizon. The research, ironically, comes from a major investment bank which is part of an industry that prospers by encouraging short-term trading.

True value investors should focus on valuation as it maximises the chance of outperforming the market on a long-term basis. This can be hard to justify to investment oversight committees where peer comparison and human bias demand immediate action and results. It is understandable why so much of the retail and institutional funds management industry trends towards career-risk driven mediocrity and hugs the benchmark. Good investing, like good cooking, doesn’t benefit from having too many chefs in the kitchen. Too many investors trade too frequently, do not properly anchor assessments in fundamental, long-term reasoning, or fire their fund managers too quickly.

Cooking at home is more challenging as we become time poor, yet it is increasingly satisfying for the same reason. We believe patience and high conviction as sources of excess return and they are likely to persist due to the unchanging nature of human psychology.


Sam Morris is an Investment Specialist at Fidante Partners and Adrian Warner is CEO/CIO of Avenir Capital. Fidante is a sponsor of Cuffelinks. This article is for general information only and does not consider the circumstances of any individual.


  •   2 November 2017
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Index funds invest in the bad and the good

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.