Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 410

Rising real yields likely to undermine equity values

In the United States, the economy has recouped nearly all the ground lost during the pandemic, and corporate earnings aren’t far behind. As I wrote in Firstlinks in April, 'A year like few others but what's next?', risk assets have discounted this V-shape recovery but as economic and earnings data evolves from forecast into fact, markets are looking ahead to see what’s next.

I believe what’s next will be a day of reckoning as investors grapple with higher yields. Here’s why.

Every investment opportunity is ultimately weighed against competing possibilities for use of funds. The decision to allocate capital happens only if the investment will clear its hurdle rate. While the height of every investment hurdle is determined by its idiosyncratic risk, real, inflation-adjusted interest rates are the first input into that calculus.

Anchors aweigh

During the 2020 recession, central bankers were determined not to allow lockdowns to morph into a credit crisis. In order to buoy animal spirits, policymakers drove real US Treasury yields deeply into negative territory, as illustrated in Exhibit 1 below.
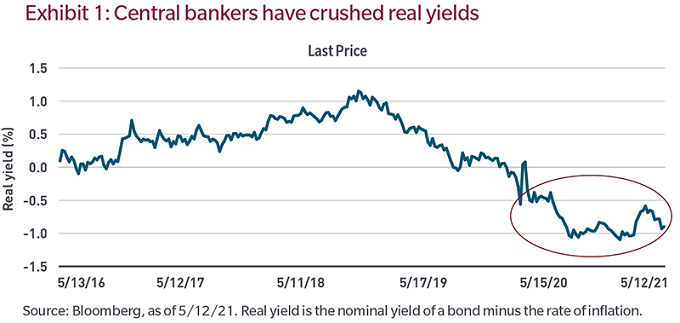
In the years leading up to the pandemic, the real yield on the 10-year US Treasury Note lived in a meagre range below 1%, but at least it was positive and provided investors with some sort of measuring stick.

However, financial theory holds that asset prices can’t go negative. Since capitalism requires a hurdle rate, business school courses don’t teach students how to value a company or a project with negative nominal or real interest rates.

Without an anchor, it’s apparent why risk assets have risen as they have. Exhibit 2 overlays the advances made by the S&P 500 and MSCI World indices from their pandemic lows against the path of U.S. 10-year Treasury real yields into negative territory.
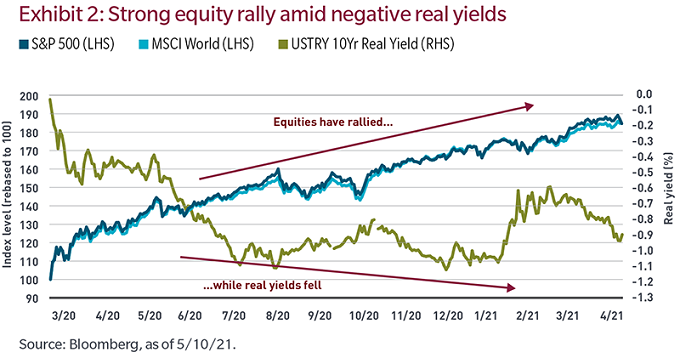
(The Standard & Poor’s 500 Stock Index measures the broad US stock market. The MSCI World Index measures stock markets in the developed world).

While there’s much sell-side research contending that risk assets can absorb inflation and higher rates, there’s an observable inverse correlation in the chart above that I think is causal and not coincidental. Since rates are the first hurdle in the valuation of any asset, higher rates, whether real or nominal, lower the value of that asset.

Negative real yields are unsustainable

As economies continue to reopen and excess savings are spent, inflationary pressures will continue to mount. We’re seeing it in goods such as lumber, semiconductors and automobiles; in services such as airfares, rental cars and vacation rentals; and in hard assets such as commodities and real estate.

Ultimately, we believe these pressures will prove transitory as the secular disinflationary forces of the past decade-plus — elevated debt levels, aging demographics and continued digitalisation, to name three — reassert themselves.

However, we’re confident that negative real rates are unsustainable and will eventually normalise. What we’re less confident about is the timing or the rate at which real yields will rise.

Regime shifts are always clear in hindsight but rarely at the point of inflection, yet markets have a way of sniffing them out. And when they do, we suspect that the relationship displayed in Exhibit 2 will reverse as rising real yields undermine equity valuations. As we go from forecast to fact, we believe market performance and leadership will look materially different than they have in the past several quarters.


Robert M. Almeida is a Global Investment Strategist and Portfolio Manager at MFS Investment Management. This article is for general informational purposes only and should not be considered investment advice or a recommendation to invest in any security or to adopt any investment strategy. Comments, opinions and analysis are rendered as of the date given and may change without notice due to market conditions and other factors. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343), a sponsor of Firstlinks.

For more articles and papers from MFS, please click here.

Unless otherwise indicated, logos and product and service names are trademarks of MFS® and its affiliates and may be registered in certain countries.


  •   2 June 2021
  • 2
  •      
  •   

RELATED ARTICLES

Is there any point in holding cash?

The bank is still a terrible place to put your money

Dividends strong as some things change, some stay the same

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Higher yields are creating opportunities in global bonds

Bond markets are adjusting to a new reality, but not in the ways investors expect. With markets repricing and capital competing for attention, investors may need to rethink where resilience and opportunity lie. 

Latest Updates

Retirement

The retirement account that Australia should have

Our retirement system asks one account to do two very different jobs. A dedicated "rainy day" account separating income from emergency savings could deliver better outcomes and greater peace of mind for retirees.

Investing

What the US midterm results mean for investors

Democrats have regained control of Congress, changing the equation in Washington. Whether that proves positive for investors will depend less on the result itself and more on what happens next for growth and markets.

Taxation

Should the capital gains tax reward risk?

A reader query on the recent CGT reforms has revealed a bigger issue. One overlooked feature of the old system may have done more than compensate for inflation. As we move to indexation, are we forgetting to reward risk?

Investment strategies

Bonds: The income and diversification trade-off

Rising yields have made bonds attractive again, but that does not mean they will behave as expected. As inflation, fiscal pressures and geopolitical risks reshape markets, the role of bonds may be more complicated than it appears.

Investment strategies

Why high-dividend investing deserves another look

Income investors have endured several lean years, but signs of a recovery are emerging. As opportunities improve, investors face an important choice between chasing headline yields and building a reliable source of income.

Investment strategies

Why 'overvalued' has been such an expensive word

Investors love simple rules, especially when markets appear stretched. Yet some of the strongest returns have arrived when the outlook seemed least attractive. This leaves an important question that history struggles to answer.

Investment strategies

AI – A good kind of bubble or just a bubble?

Investor obsession with AI is attracting unprecedented amounts of capital and confidence. But beneath the excitement lies uncertainties about returns, funding and risks that enthusiasts may not be paying enough attention to.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.