Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 394

Should equity investors fear higher bond yields?

Investors have focused on the bond market in recent weeks because they have seen something unfamiliar – rising bond yields. In January, the US government 10-year bond yield (the rate of interest the US government borrows at) surpassed the psychological barrier of 1% for the first time since the COVID shock began.
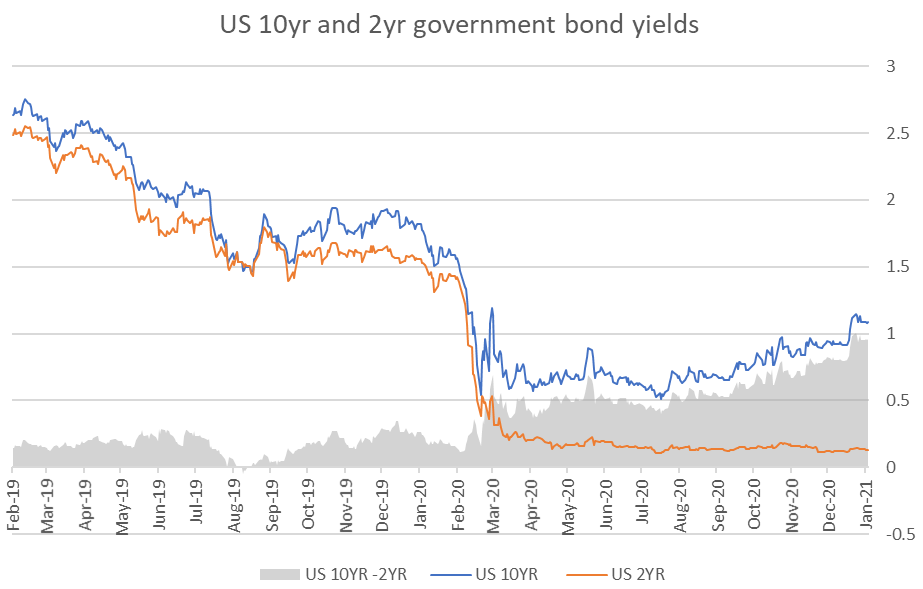
Given lower bond yields have been used to justify higher share market valuations for much of the last decade, rising yields could pose a threat to equities.

Seasoned investors have been arguing for years that equity valuations have become dangerously dependent on the persistence of historically low bond yields.

While we don’t believe the rise in bond yields is dangerous yet or reflects the threat of a sharp acceleration in inflation, rising yields will likely be a headwind in gains for equities. And that means that if investors want to generate strong returns from equities in coming years, they will need to focus on stock-picking skills.

Why bond yields have been heading higher

Expectations around economic growth and inflation have driven bond yields higher. The emergence of effective coronavirus vaccines has triggered optimism that the global economy will rebound powerfully in 2021. The Democrat control, of the US Senate has also increased their ability to drive through a reflationary economic agenda.

Yet even as the pandemic recedes, it appears central banks are set to maintain policy rates at or near zero, further allowing inflation pressures to build. This comes as the US Fed, as well as the Australian RBA, want to now wait longer to see actual inflation (rather than expected inflation) heading sustainably higher before they start lifting interest rates.

How bond yields affect equity valuations

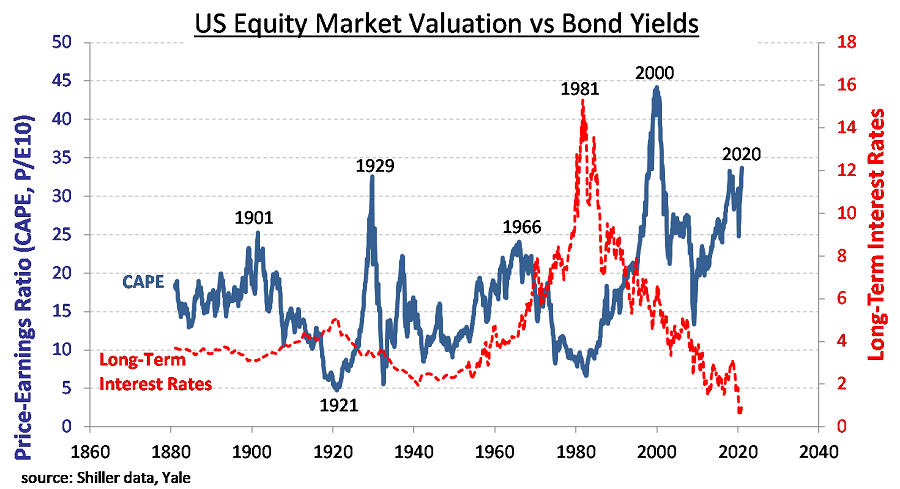
Bond yields are an important determinant of equity valuations. When bond yields go down, share market valuations tend to rise … and as bond yields go up, share markets tend to falter.

The relationship may not exactly hold in the very short-run but it becomes more clearly visible over longer time periods as can be seen in the figure below (cyclically-adjusted price-to-earnings ratio used a share market valuation measure).
There are three key and interrelated factors that link bond yields with equity valuations:

  • Firstly, bond yields drive the opportunity cost of equities. If, for example, the 10-year bond is yielding 5% per annum, then equities only become attractive if they can earn well above 5%. In fact, because equities are riskier than bonds, investors demand a ‘risk premium’ to justify owning them. The long-term average risk premium on equities is 5%. So a 10% return - the 5% investors could get from bonds + the 5% risk premium - will act as the opportunity cost for equity. Below a 10% return, it makes less sense for investors to hold equities because they are not being compensated for the additional risk. As bond yields go up, the opportunity cost of investing in equities also goes up, and equities become less attractive.

  • Secondly, bond yields also impact the cost of capital in valuing equities. The yield on bonds is typically used as the risk-free rate when calculating this cost of capital. When bond yields go up, the cost of capital goes up. That means that future cash flows get discounted at a higher rate, meaning a $1 of cash flow received in the future from a company is worth less today. This compresses the valuations of these stocks.

  • Thirdly, bond yields impact financial costs for companies. When bond yields go up, it is a signal that corporates will have to pay a higher interest cost on debt. As debt servicing costs go higher, the risk of bankruptcy and default also increases, typically making highly leveraged companies vulnerable.

Good and bad market volatility

Although bond yields do impact share valuations, investors should be more worried about losses that result from a downward revision of a company's earnings potential than losses caused by an increase in interest rates (all else equal).

The former suggests a market assessment that there is now a greater chance that the business will fail to deliver its expected earnings growth. While losses from increasing rates indicates the adjustment of the rate of discount, without a revision of market views on the company itself.

Indeed, to achieve long-term success, investors should distinguish between good and bad volatility. Private investors often regard any loss as bad news, but it may be an opportunity to lock in access to higher future income.

For example, a move up in bond yields allows investors to buy and lock in future income at a lower cost. That’s good news for anyone saving for a pension or an education endowment. For superannuation savings plans, it means that more future pension income can be bought with each new dollar of saving.

Should investors be worried?

The critical question is whether the current move up in bond yields goes beyond a healthy reflation that reflects the post-pandemic economy, and surges into inflation.

At the moment, markets are positioned for the former: that is, the economy will recover, inflation will stay under control and interest rates will remain low.

Even under this scenario, investors should still factor in that equity valuations are likely to be pressured over coming years as interest rates trend higher. This means that strong equity returns will have to rely more on actively selecting the stocks that can generate sustainable earnings growth, and less on free kicks from falling bond yields and central banks cutting interest rates.

Or in other words, a greater proportion of returns are likely to come from stock picking skill rather than a rising tide lifting all boats (read: companies) in the market.


Andrew Mitchell is Director and Senior Portfolio Manager at Ophir Asset Management. This article is general information and does not consider the circumstances of any investor.

Read more articles and papers from Ophir here.


  •   10 February 2021
  • 4
  •      
  •   
4 Comments
Jack
February 10, 2021

Why do the official inflation rates report negligible price increases while my costs - meat, utilities, fruit and now property prices - all seem to be increasing. A farmer told me a breeder sheep used to fetch $200 and now it's $500.

Eric
February 10, 2021

That's to do with the basket of goods used for calculation of CPI, generally speaking, prices that changes too much and/or not inline with the overall economic condition is excluded from this basket. So meat price gone up due to drought or bushfire is excluded, fruits ,vegies and fuel are excluded by default(because they are volatile items).

You can find the information on the RBA website.

I agreed with you that meat and fish price has gone up a huge amount over the last 10 years or so.

Former ABS employee and economist who uses the CPI
February 10, 2021

Eric, that's not quite right.

The CPI does not exclude prices that are not in line with average. The CPI is a full basket of goods and services acquired regularly by all Australians, weighted according to how much is spent on them. If prices go up a long way, or down, then that gets weighted into the overall CPI.

The ABS does publish some indices that are the CPI excluding certain items - and their website even guides you through the process of coming up with your own CPI-excluding measure using their comprehensive data set.

I think you're confusing the CPI with some of the analytical approaches that economists like the RBA take to trying to smooth out volatile items so that they know what impact monetary policy is having. They don't select things to exclude based upon external events like a bushfire or drought - they just trim the highest increase items and the lowest fall items to create a 'core' series. The automatic exclusion of veges and fuel is no longer used - actually, it never has been in Australia, that's a US thing to measure the 'ex food and energy' CPI. The RBA's measures are more sophisticated attempts to smooth out the quarterly changes than just leaving stuff out.

As for meat and fish, here are some facts:
CPI inflation overall has been 1.9% per annum over the last 10 years
Meat and seafoods in total has gone up almost the same, 2.2% per annum
Beef and veal has gone up by more, at 3.9% per annum as has lamb (2.7%), but pork (1.8%) and poultry (almost unchanged at 0.2% pa) have been much lower.
Fish and seafood has inflated by 1.6% per annum, so less than the total by a little bit as well.

I wouldn't say that justifies the subjective feeling that 'meat and fish has gone up a huge amount' over the 2010-2020 period.

For Jack, well, the price of a sheep might have changed by $300, but over what period? And also, there are a lot more elements to the price we pay in the shops for lamb than just the price of the sheep. Let's say the move from 200 to 500 is over 5 years. That's a rise of 20% per annum. Over the last 5 years the price of lamb in the shops is up by nearly 5% per annum - so the cost of transporting and storage at the abattoirs and in butchers shops has clearly not gone up as much.

Also, Jack surely even you buy more things than on that list! What about eggs? 1% per year over 10 years and less than that over the last 5. What about a bottle of wine every so often? Hardly changed over 5 or 10 years. Neither has petrol, actually. How about new shoes and clothes? Prices on average are lower than 5 or 10 years ago! What about your phone bill? That's down about 3% per year for the last 10 years.

My final comment is that to say that the CPI is hardly changed isn't true. Up 1.9% per year for 10 years and 1.6% per year over 5 years is stubbornly below the RBA's target range, but not 'negligible' as you said.

I do wish people would understand that the ABS has an enormous amount of actual data from shops, websites, etc that it uses to compile the inflation numbers and doesn't just make them up. And that the CPI is measuring all the things the average Australian spends their money on, not just a subjectively chosen portion of the items that you purchase to live on. The CPI numbers are one of the most reliable pieces of data we have.

Suzanne
February 15, 2021

Former ABS Employee - Thanks for taking the time to write such a comprehensive response. It is appreciated.


Leave a Comment:

RELATED ARTICLES

Rising bond yields complicate the COVID recovery

Beware of burning down the barn to bury the debt

Are debt and its servicing cost serious worries?

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Latest Updates

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Latest from Morningstar

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Shares

Glencore lands on the ASX. Should BHP and Rio shareholders switch?

A coal-heavy miner with governance concerns isn't the obvious choice for investors. Yet, Glencore's ASX listing may offer something BHP and Rio can't. The challenge is working out whether the opportunity outweighs the risks.

Why does the system treat capital gains and losses differently?

Investors are often told not to let tax policy drive their investment decisions. Yet, under the new CGT rules, portfolio construction, volatility and even how assets are owned may have an outsized impact on their final outcome.

Economy

Three common sense reforms that Australia needs

What do frozen bank accounts, mortgage traps and pension penalties have in common? They're all symptoms of a system that makes life much harder. Yet the obvious solutions seem to have escaped the attention of Canberra.

Shares

The hidden cost of government debt for investors

Some of the important effects of rising public debt never make the headlines. Research shows the immediate effects may already be unfolding, influencing corporate behaviour in ways that many investors would never suspect.

Investment strategies

When do fundamentals matter?

Is fundamental investing losing its grip on markets? Investors continue to search for valuation-based explanations for every price move, but the dominant force behind short-term returns may be something else altogether.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.