Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 272

SMSF investment trends show rising diversity

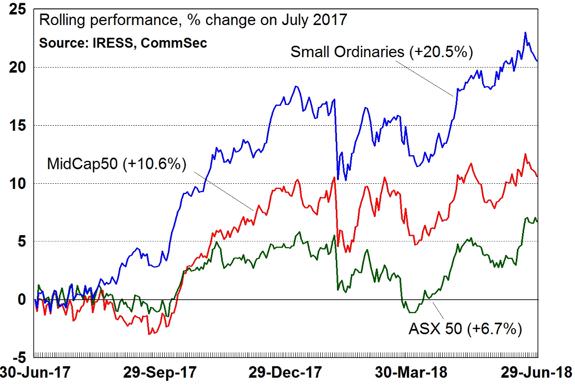
Frustrated by the underperformance of many Australian blue-chips, SMSF trustees have increasingly turned to a more diversified group of mid and small cap companies that have shown strong gains over the past 12 months. As shown below, in 2017/2018, small caps significantly outperformed stocks in the ASX50.
The trend away from the ASX20

ASX20 shares now account for just 33% of the total value of shares traded by SMSFs, down from 40% a year ago. However, SMSFs are still more likely than other investors to trade ASX20 shares. ASX20 stocks account for only 29% of trades by value undertaken by non-SMSF investors.

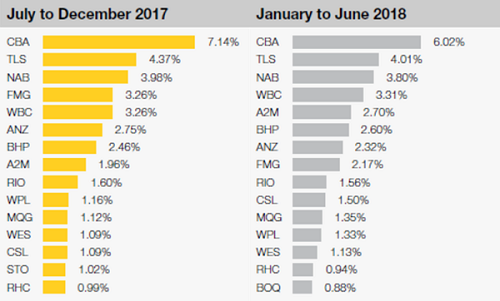
The top three most-traded stocks by value remain Commonwealth Bank (CBA), Telstra (TLS) and National Australia Bank (NAB), although they now account for a smaller proportion of trades overall. The key changes were CSL (CSL) into the top 10, while A2 Milk (A2M) moved up from eighth to fifth. On the flip side, Woodside (WPL) fell out of the top 10, and Fortescue Metals (FMG) fell from fourth to eighth.

 Top 15 shares traded by SMSFs (by value, as a proportion of total trades)
Some of the biggest increases in traded values included Mirvac (MGR), with trading by value up 937%, Wisetech Global (WTC), up 161%, AMP, up 154%, and Afterpay Touch (APT), up 126%.

There was a clear overlap with seven of the top 10 performing stocks in the ASX200 over the 12 months to 30 June 2018 appearing in the top 50 stocks traded by SMSFs, as the winners attracted the buyers. Many of these are in the ASX MidCap 50, comprising the companies in positions 51–100 of the ASX200, and the technology sector.

Traditional blue-chips continue to have a strong attraction and we have seen SMSFs taking advantage of share price weakness to buy into companies like AMP, Ramsay Health Care and Telstra, in a blue-chip bargain hunt that reflects an underlying belief in the long-term prospects for these ASX stalwarts.

Offshore diversification

SMSFs increasingly use ETFs to diversify offshore. Over the last six months, we’ve seen this trend intensify, with internationally-focused funds now comprising nearly 47% of all ETF trades, up from 44%. As a result, Australian share ETFs now account for only 42% of ETF trades, down from 43%.

ETF trades by value and category
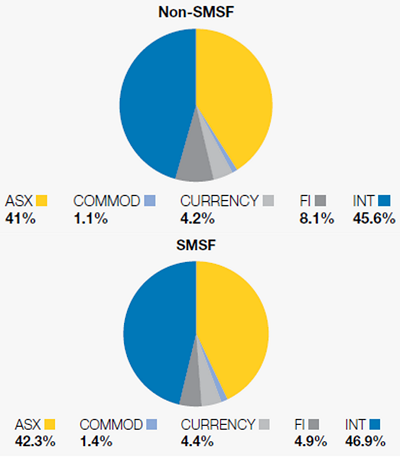
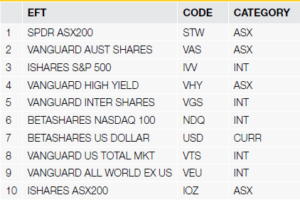
While the top four ETFs have remained unchanged over the last six months, an analysis of the top 12 ETFs traded by value shows SMSFs increasing their exposure to currency and property, as well as international equities. The strength of this shift suggests it is being driven by a desire for greater diversification, rather than simply the relative performance of different markets.

The Top 10 ETFs by trade value 1 January to 30 June 2018
Like ETFs, SMSFs are increasingly using Listed Investment Companies (LICs) and Listed Investment Trusts (LITs) to gain exposure to new asset markets, particularly offshore. During the last six months, the value of international LIC and LIT trades by SMSFs has risen from 23% to 26% of total LIC and LIT trades.

The Top 10 LICs/LITs by trade value 1 January to 30 June 2018
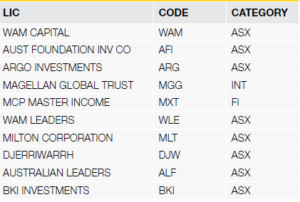
While the top four most-traded funds by value have remained the same over the last six months, the MCP Master Income Trust has moved into fifth place, with trades increasing 60% by value. This trust is a fixed income LIC, and its newfound prominence is further evidence of a growing tendency by SMSFs to use listed investment vehicles for greater diversification.

Overall, recent trading data confirms that the new, internationally focused LICs and LITs have carved out a significant niche, despite the considerable head start enjoyed by long-established domestic LICs.

Direct investment into international shares

As international trading becomes easier, adding Apple or Facebook to an SMSF portfolio has become increasingly attractive.
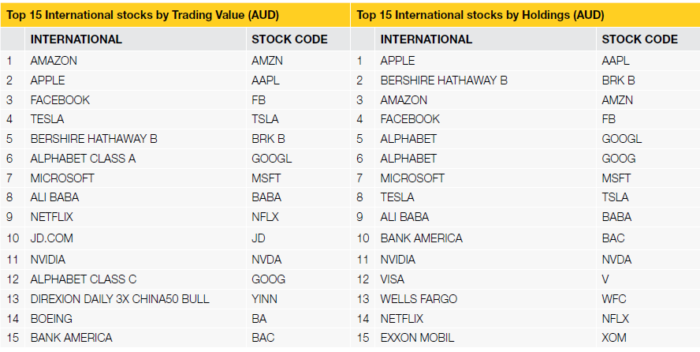
Over the last six months, the value of direct international shares traded by SMSFs has grown by 30%, building on a 27% rise in the prior period, a growth rate significantly higher than that of non-SMSF investors. International share portfolios have become increasingly diversified, with the average number of international stocks held by SMSFs rising from 5.7 to 6.4, compared to just 3.4 among other investors.

Looking at the top 15 stocks held by SMSFs (refer Top 15 table above) reveals a list of well-known names and strong share price performers, especially the FAANG stocks – Facebook, Amazon, Apple, Netflix and Google (or Alphabet). They also include trusted names such as Berkshire Hathaway and Microsoft, with a strong overall US focus.

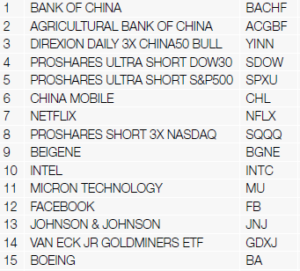
However, Chinese-based stocks, particularly technology stocks Ali Baba and JD.com are also represented, and over the last six months, some of the largest increases in trading value have been Chinese-based bank stocks, as shown in the trading values table. This interest in international diversification among SMSF investors extends beyond individual companies to ETFs available only on overseas exchanges. As a result, the value of offshore ETF holdings has increased 49% over the last six months, albeit from a low base.
Increasing SMSF diversity and sophistication

Looking back at the last six months, SMSF investors are increasingly diverse and sophisticated in their investment choices. While their portfolios are still heavily weighted towards larger domestic stocks, SMSFs are looking beyond the ASX20, as well as taking advantage of market dips to buy into blue-chip shares at a bargain price.


Marcus Evans is the Head of SMSF Customers for Commonwealth Bank. This article is based on a report, the CommSec SMSF Trading Trends Report, an exploration of the online trading behaviour of SMSF investors, released every six months, prepared by Commonwealth Securities Limited (CommSec). This article is general information and it is not intended to replace professional advice.

  •   18 September 2018
  • 5
  •      
  •   
5 Comments
Keenan
September 18, 2018

Thank you for an informative and interesting article.

It would be intersting to find out how SMSFs manage their FX risk when investing in international shares.

SMSF Trustee
September 20, 2018

OK Keenan, I'm not sure exactly what you have in mind in asking that question, but I'll tell you how I manage currency in my SMSF.

I make my allocation to international shares taking full account of how much FX risk I want to have. When I'm positioned at my 'neutral' allocation I'll be unhedged, fully accepting the contribution to volatility that the currency brings. When I want more global shares than this, I'll usually go into a hedged global share fund. I make sure to include in the portfolio a manager that offers an unhedged and a hedged version of their product (eg Realindex).

I have some allocations to global active macro managers that may include some short or medium term exchange rate position-taking based on a view about short to medium term movements, but other than that I don't really believe that exchange rates can or even need to be actively managed.

In my international fixed income allocations, I use hedged funds or funds that have a limited scope to do what the global macro managers mentioned above do.

I'm sure that lots of other SMSF folk do it differently than that, but I'm sure I'm not Robinson Crusoe either.

Duncan
September 20, 2018

I'd love to know how they manage their taxes on international shares and on ETFs. The tax accounting for these is really hard!

Dane
September 20, 2018

Pleasing to see some assets being moved offshore. I was talking to a someone recently who made the point that given Australia is like a small cap sector given it only represents less than 3% of total global sharemarket. There is obviously currency risk with offshore equities and no franking credits on offer but the former can be hedged and the latter may disappear as of May next year.

- Looking at the composition of top 15 shares traded by SMSF's, it's interesting that investors have a propensity to buy more of things as they get more expensive (Afterpay, Wisetech A2M). This is the exact opposite of what we normally do as consumers when buying any other goods/services that are not called shares. Can't take credit for that as it was Howard Marks who made that observation.

- If Trustees are holding both ASX200 ETF's and individual bank and resource stocks on top, you should be mindful of the level of exposure to these two sectors, which will represent almost 50% of the ETF's exposure.

- LIC's seem to be all the rage and if you can buy one at a discount (i.e. for less than the assets are worth) then it can work out nicely if the gap closes over time. But there is no guarantee it will and you are also adding an additional element of uncertainty to an already difficult game as there is no knowing where the LIC will trade relative to its NTA. If you buy LIC's at a premium...I'll just leave it there. lol

Keenan
September 23, 2018

Dear SMSF Trustee,

Thank you for the comprehensive answer.


Leave a Comment:

RELATED ARTICLES

Headwinds and tailwinds, a decade in review

Why August company reporting season was poor

It’s the large stocks driving fund misery

banner

Most viewed in recent weeks

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Latest Updates

SMSF strategies

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

Planning

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Exchange traded products

The hidden trade-off in fixed income ETFs

Some investment trade-offs are immediately visible. Others are embedded in the way a portfolio is constructed. Understanding the difference may explain why similar-looking investments can produce surprisingly different results.

Retirement

The mortgage free retirement is fading

What happens when a generation reaches retirement carrying obligations previous generations largely avoided? New research suggests we may need to rethink both how much we need in retirement and what life could look like.

Retirement

The key question to inspire a confident and purposeful retirement

Most people spend decades planning for retirement. Far fewer plan for what happens when they get there. The difference may explain why so many find the transition harder and less fulfilling than expected, despite careful preparation.

Latest from Morningstar

Making the case for a 'good enough' portfolio

Some investors spend years chasing the perfect strategy. Others choose a path that’s simply good enough and move on. Which approach is more likely to deliver both better outcomes and a happier financial life over the long run?

Investment strategies

Is the US market as expensive as CAPE says?

Many investing ideas survive for decades. But that does not make them right. A famous valuation measure implies that US shares are dangerously expensive, but the evidence may point to a very different conclusion.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.