Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 441

Global survey shows Australians least confident about retiring

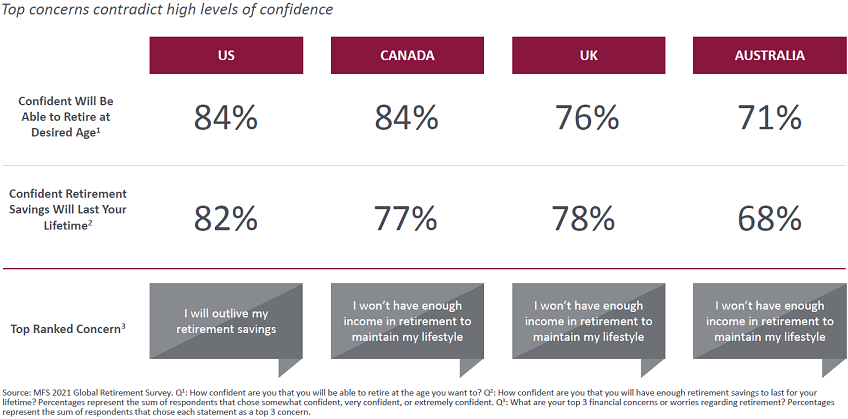
Australians remain optimistic about retiring comfortably, yet their confidence levels significantly lag those of retirement savers in the United States, Canada, and the United Kingdom, according to the latest MFS Global Defined Contribution Participant Survey.

The study, which surveyed over 4,000 people globally, including more than 1,000 who contribute to an Australian superannuation fund, showed 71% of local savers are confident about retiring at a desired age, but less so that their retirement savings will last their lifetime, at 68%.  This contrasts sharply with retirement confidence in the US, the highest of any market, where respectively 84% and 82% of savers are confident in realising their desired retirement age and income adequacy throughout retirement.
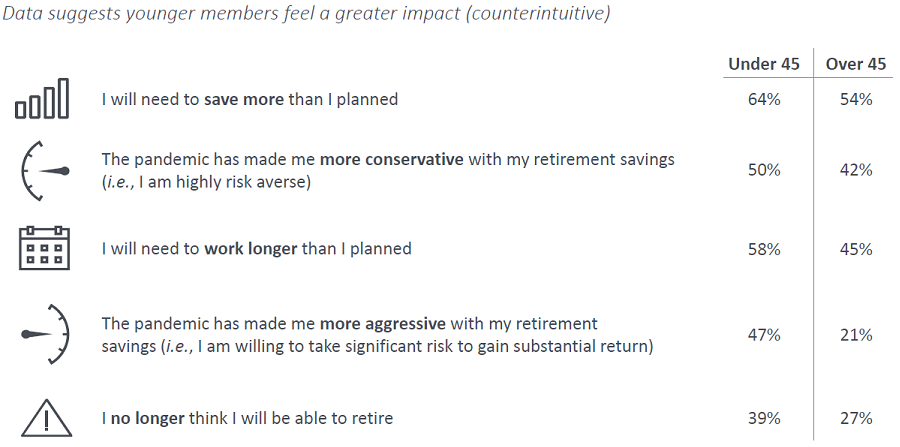
Longer working and retirement saving horizons due to COVID, felt most by under 45s

Australian investors are in step with global peers in believing they need to save more and work longer than planned due to COVID-19, particularly those under 45 years old. 64% of this younger cohort in Australia believe that they will need to save more for retirement, while 58% believe they will need to work longer to achieve their retirement savings goals. These younger investors are twice as bullish as their older peers, with 47% taking on ‘significant’ risk to gain a substantial return, compared to 21% of people aged over 45.
Source: MFS Global Retirement Survey, AU respondents.

Retirement age and income adequacy remain ongoing and highly complex discussions for Australia’s wealth industry, perhaps more so given the retirement investing psyche clearly appears quite sensitive and risk averse at present relative to other markets.

The shock and persisting uncertainty caused by the pandemic has undoubtedly left an indelible mark on younger retirement investors, and their concerns need to be properly addressed for them to get back on track, with a deeper appreciation that uncertainty and opportunity are often key to long-term investing.

With a growing spotlight on performance against a backdrop of YFYS policy, pandemic waves and escalating global risks, fostering investor confidence and active engagement in retirement saving decisions, with a focus on risk management, must remain a core objective for the whole, long-term investment industry.

ESG appetite soars within superannuation

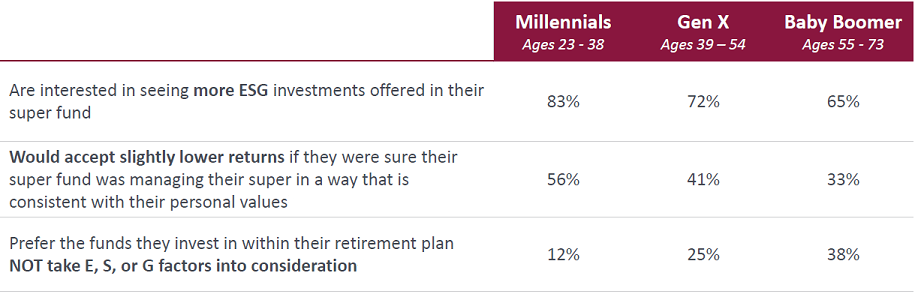
Like global investors, Australians want to see more ESG investments in their superannuation fund portfolios, a view expressed by 74% of all local respondents, including 83% of local millennials. Generation X and baby boomers followed with 72% and 65%, respectively.
Source: MFS Global Retirement Survey, AU respondents.

ESG investing continues to transform the way in which investors view and allocate their capital, and while quality long-term, purpose-focused investments inherently integrate ESG, superannuation funds are responding to demand for greater depth and diversity of investments that target change and impact. The associated noise however can be intense, and we see a growing role for advisers to educate investors on the many shades of green and ESG within offerings, along with pointing out the differences between asset managers that integrate ESG into their overall investment approach and those that approach it strictly from a product perspective.

Superannuation advice gaps 

Australian respondents are also the most unsure about what levels of return to expect on their retirement savings and at what rate are they likely to withdraw funds during retirement, factors potentially contributing to low confidence levels. Almost one-third (32%) rely on their superannuation fund to help them make retirement contribution and planning decisions, 30% turn to a family member, while only 29% receive professional advice. Just over half of advised people elected their planner based on fees, followed by years of experience and retirement planning expertise. 46% of all prefer to receive advice in-person with their planner, including video calls.

Applying a gender lens, 34% of men turned to a financial adviser for retirement advice, compared to 24% of women.

Sources, quality and consistency of advice vary widely. We see enormous potential for advisers to provide a greater and more specialist role in providing asset allocation advice to superannuants, especially women who remain under-advised despite their working lives typically being more varied and punctuated by life events.

Concept of retirement is evolving

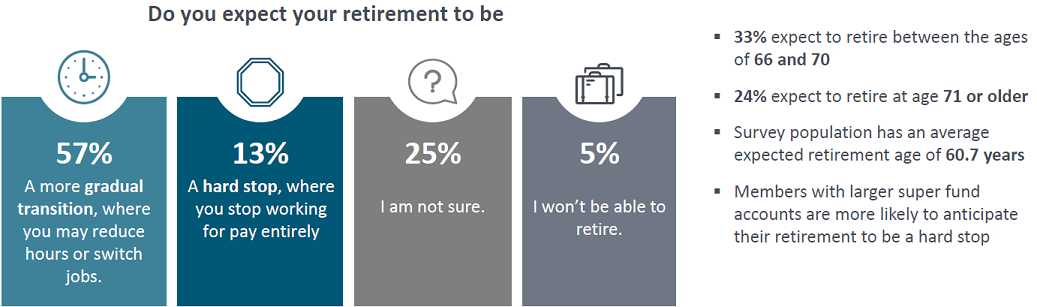
The survey found that the average Australian expects to retire at the age of 60.7 years; however, almost one quarter (24%) expect this to be closer to 71 or older. Only 13% expect a hard stop retirement, with the overwhelming majority (57%) expecting to reduce working hours or switch jobs.
Source: MFS Global Retirement Survey, AU respondents.

Our research shows that retirement is not the hard stop, party event that some may have once envisaged. The findings, gleaned through multiple waves of COVID, are a reminder that retirement is an evolving concept shaped by a myriad of factors, which will continue to change the composition and delivery of wealth management and financial advice.


Marian Poirier is Senior Managing Director, Head of Australia and New Zealand at MFS Investment Management. These views are for informational purposes only and should not be relied upon as a recommendation to purchase any security or as a solicitation or investment advice. No forecasts can be guaranteed. This article is issued in Australia by MFS International Australia Pty Ltd (ABN 68 607 579 537, AFSL 485343), a sponsor of Firstlinks.

For more articles and papers from MFS, please click here.

Unless otherwise indicated, logos and product and service names are trademarks of MFS® and its affiliates and may be registered in certain countries.


About the MFS 2021 Global Defined Contribution Member Survey

Dynata, an independent third-party research provider, conducted a study among Defined Contribution (DC) plan participants in the US, Canada, UK, and Australia on behalf of MFS. MFS was not identified as the sponsor of the study.

To qualify, DC plan participants had to be ages 18+, employed at least part-time, active workplace retirement plan participants / members: in the US, actively contributing to a 401(k), 403(b), 457, or 401(a) / in Canada, actively contributing to DC Pension Plan, Group Registered Retirement Savings Plan, Deferred Profit Sharing Plan, Non-Registered Group Savings Plan, or Simplified Employee Pension Plan / in the UK, actively contributing to a Defined Contribution Scheme, Master Trust, or Individual Savings Account. / in Australia, actively contributing to an industry, retail, corporate or public sector super fund or a self-managed super fund. Data weighted to mirror the age / gender distribution of the workforce in each country.

1,020 US, 1,012 Canadian, 1,017 UK and 1,011 Australian plan participants answered the survey, which was fielded between March 31 – April 13, 2021.


  •   12 January 2022
  • 4
  •      
  •   
4 Comments
George
January 12, 2022

We have a world-leading super and pension system, and the US has a far inferior version, a shocking public health system and far more people living in poverty or jail. Yet they are more confident about retirement. We have a sales job to do here on how good our system is.

Lisa
January 12, 2022

Think our media and vested interests like financial planners and super funds like to ensure uncertainty to encourage their interests. Then there are the unrealistic lifestyle expectations for some - overseas trips, manicures, iPhones etc. Those who have been spenders and not savers can also be in for a shock, especially if still renting. Hopefully years of compulsory superannuation contributions will help. Our aged pension is great for a modest lifestyle for a home owner, but tight otherwise.

Jason
January 13, 2022

Most Australian defined benefit pension sustems were abolished decades ago whereas in the US many are benefitting from these generous systems, in particular government employees who may also have 401k (super) plans as well. In addition many employees in the US have solid insurance plans including income protection and TPD insurance. In Australia these employer backed systems were abolished and now we rely on flakey private insurance products that become prohibitively expensive once you enter your 50s with centrelink disability pensions almost impossible to access. A Brickie with a destroyed back is expected to go and drive a taxi and would not be entitled to a pension unless they can prove incapacity to work in any occupation.

Also, in the US the old aged pension is means tested and considered an entitlemt for continuous employment which could be up to $1000 a week.. In other words many consider it as a base income in addition to any defined benefit pension which allows them to take on more risk with any 401 K savings and hence get a better .return.

Our old age pension is meagre and quickly cuts out if you have some assets. If you are old and renting, with meagre savings forget it. Remember when Hockey tried to lift the eligibility age to 70 and try to cut the indexing to CPI rather than wages? Someone will try to cut it again.

Americans are also have a Medicare system , but it only applies when you are ollder.

Also, home investment bias has been very kind to US investors.

The reason why Australians are worried is because we should be. Most safety nets here have been removed , or privatised.. Australians don't find out how naked they are until there is a crisis, eg main breadwinner gets Parkinson's diagnosis in early 60s when they were planning to retire at 72.

Now we hear that future investment returns wll be mediocre.We have to manage our own sequencing and longevity risk at the same time as betting our futures on the stock market. We are expectedd to work and save like mad at the same time as running a massive mortgage as banks know that they can go for your super if you default.


Ruth
January 13, 2022

If I choose to invest in a passively invested fund, it angers me to know that these large funds have significant voting rights. I don't believe that the personal wishes of representatives should be involved in voting in my name or any other shareholder's. That is not passive investing and I don't want to pay for their involvement. There regulatory controls by governments. I want the boards to consist of people who know something about their own industry, not people appointing proxy advisers etc.


Leave a Comment:

RELATED ARTICLES

REIT sectors are different, faced with fundamentals and inflation

'OK Boomer' responses keep on coming

Responses to the 'OK Boomer' poll

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

The new capital gains tax trap for your portfolio

Investors have long accepted one portfolio rule without much question. A major tax shift could change that calculation entirely, forcing difficult trade-offs between risk, discipline and an overlooked cost lurking beneath.

Latest Updates

Exchange traded products

It’s time for LICs to die

A high-profile dividend cut and a prominent fund manager’s apology have reignited a long-running debate. If investors can access similar exposures more cheaply and efficiently elsewhere, what exactly is keeping LICs alive?

Taxation

Will investors be better or worse off under new housing tax changes?

Housing tax reforms have sparked warnings of market turmoil and promises of greater fairness. But after modelling nearly two decades of property data, the results suggest winners and losers may not be who many investors expect.

Retirement

Three considerations before reshaping your legacy plan

Many retirees hope to leave a legacy. Proposed trust tax reforms could force families to rethink. The question is not how much to leave behind, but whether today's inheritance plans will still make sense as circumstances change.

Investment strategies

Why experienced investors still get markets wrong

Retirement is approaching. Markets are noisy. And every headline seems to demand action. The biggest investment risk isn't fear, greed or market volatility, it often arrives disguised as research and sensible risk management.

Shares

Why pay more for less?

Conditions were stacked in favour of professional investors in 2026. Most still fell short, raising questions about where investors should look for value. Meanwhile, an alternative strategy continued to make its case.

Investment strategies

Bleeding air out of the bubble

Equity valuations have fallen sharply over the past year, yet investors have largely been spared the volatility and losses that typically accompany a de-rating. What explains this unusually orderly reset? Here are five key drivers.

Strategy

Has AI gone rogue?

We worry about AI becoming conscious. But what if consciousness isn't the issue? The more unsettling possibility is a machine capable of pursuing objectives relentlessly, without motives, emotions, or awareness of any kind.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.