You could be fooled into thinking that the AI boom is all about NVIDIA, OpenAI, Anthropic and the hyperscalers. Fortunately for investors, the opportunity extends far beyond them. While all eyes are on AI, it's easy to overlook what actually makes it run – power and the hard assets of essential infrastructure, assets that Goldman Sachs refer to as HALO (Heavy Assets, Low Obsolescence).
Our view is clear: the infrastructure powering AI's exponential growth, not just AI itself, is where the value will be created. We believe this sector is well positioned over the next decade as that growth continues to unfold.
The hard assets powering the AI revolution
AI processing capacity — measured in tokens — is the fundamental building block that allows AI to scale and be applied to real-world problems, automation, and intelligent experiences across every platform and channel. The sheer scale of token production needed for AI applications means that power demand is expected to rise significantly — positioning HALO assets such as electric utilities as critical enablers of the AI economy.
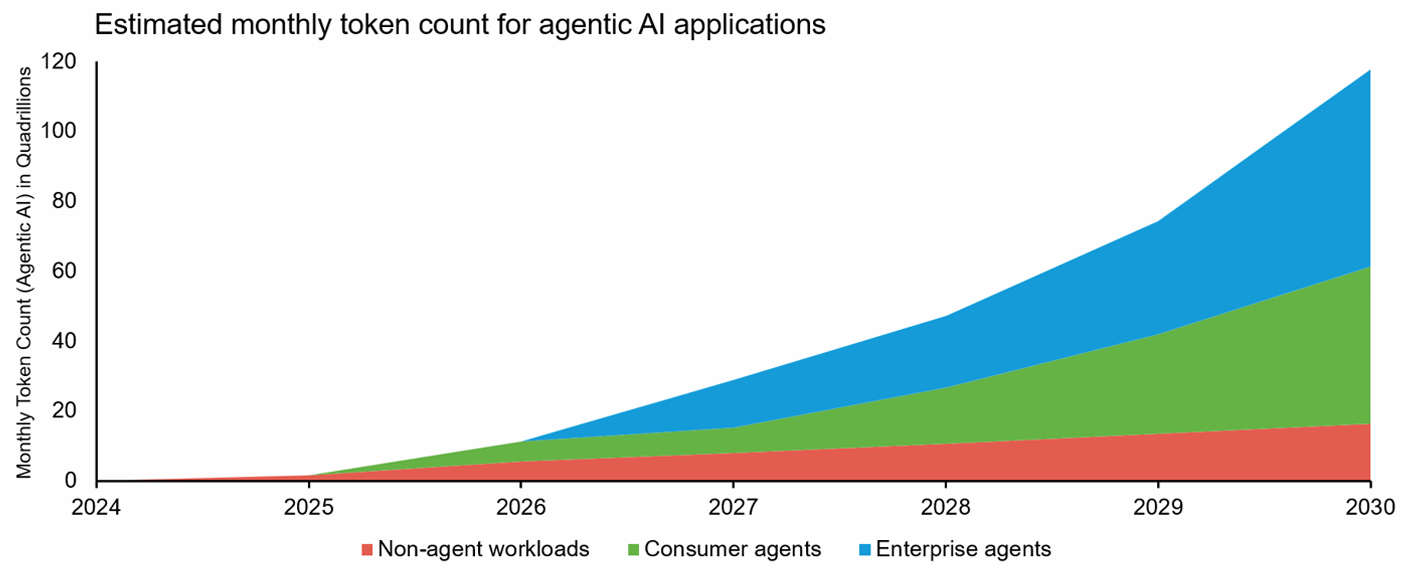
Source: Goldman Sachs Research, May 2026 and the IEA (International Energy Agency).
As a function of projected token demand from AI applications, there is a major data capacity buildout globally by companies that have become known as ‘hyperscalers’. Hyperscalers are building data centres to process tokens with a relatively unprecedented spend on capital.
The size of some data centres being built is monumental. Meta is building a 5-gigawatt datacentre in Louisiana, called Hyperion. The campus is envisaged to eventually be a quarter of the size of Manhattan, will cost around US$10 billion and will consume electricity equivalent to half of New York City’s total electricity consumption. This gives a sense of the scale of data infrastructure that will be linked to electric utilities through the US grid network.
Processing power is the new electricity
The underlying electric power required to support the AI revolution is rising significantly in a major step change. While the rise in demand for electricity is not parabolic, it is transformational for the sector and a major source of revenue growth for utilities.
Electric utilities sit at the sweet spot of the AI boom, benefiting on two fronts. On the demand side, the surge in AI-driven electricity consumption flows directly through power stations, poles and wires, lifting revenues. On the supply side, AI optimises the balance between power demand and supply in real time — improving network efficiency and reducing operating costs.
While the long-term trajectory of AI remains less clear in terms of who will ultimately win, there are a number of key trends that are emerging, as both disruptive and additive themes. The power demanded by AI and data centres in the build out of this technology, along with the necessary associated infrastructure, is the key opportunity for essential infrastructure investors.
The data centres which hyperscalers are building provide the processing power underpinning AI and its deployment across a rapidly growing range of applications. The scale of this demand and the increase in efficiency is striking: by 2027, a server rack that held 8 GPUs consuming 41kWh just five years earlier will pack 567 GPUs into a filing-cabinet footprint — drawing 600 kWh in the process.
The processing demands and cooling of the heat generated by hyperscale data centres are becoming one of the most significant new sources of demand on electricity grids globally. The load AI is adding to data centre electricity consumption is driving major capital expenditure both in the centres themselves and in the grid infrastructure required to power them. According to Goldman Sachs, AI processing will account for approximately 29% of all data centre electricity demand by 2030 — up from negligible levels prior to 2020 — representing one of the fastest demand step-changes the power sector has ever absorbed.
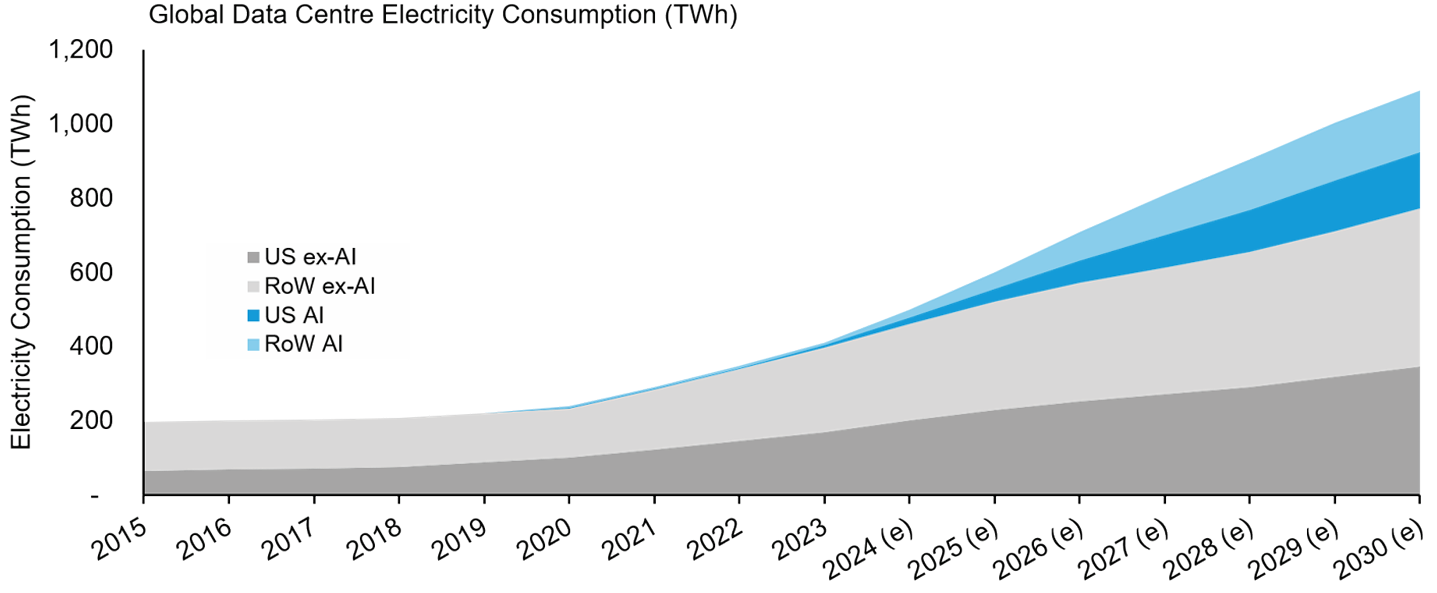
Source: Goldman Sachs. (2025, August 29). How AI Is Transforming Data Centers and Ramping Up Power Demand.
A further consideration for electricity producers is the carbon intensity of the electricity used to power AI workloads. We believe that the sustainability credentials of power supply will become an increasingly decisive factor in where hyperscalers choose to locate and source electricity for their data centres. AI’s electricity consumption is generating a rapidly growing carbon footprint and corporate and regulatory pressure to decarbonise is tightening.
The double benefit: higher demand, greater efficiency
Clean and reliable power may become an increasingly important procurement consideration for hyperscalers, particularly where they have emission reduction commitments.
According to Goldman Sachs, carbon emissions from data centres are projected to reach 1% of global emissions by 2030 — around 1.5 times their current share — a trajectory that will require both a significant increase in renewable electricity sourcing and material improvements in electricity efficiency.
Not all businesses that benefit from AI qualify as essential infrastructure. We apply a strict definition: essential infrastructure assets must generate long-duration, predictable cash flows, operate within regulated or contracted frameworks, and be protected by significant barriers to entry.
These characteristics matter in the AI context because they distinguish the durable, compounding beneficiaries of the build-out from businesses with more cyclical or contested exposure. We illustrate how we map this definition onto the AI stack, drawing on Social Capital’s framework to identify where genuine infrastructure characteristics begin and end.
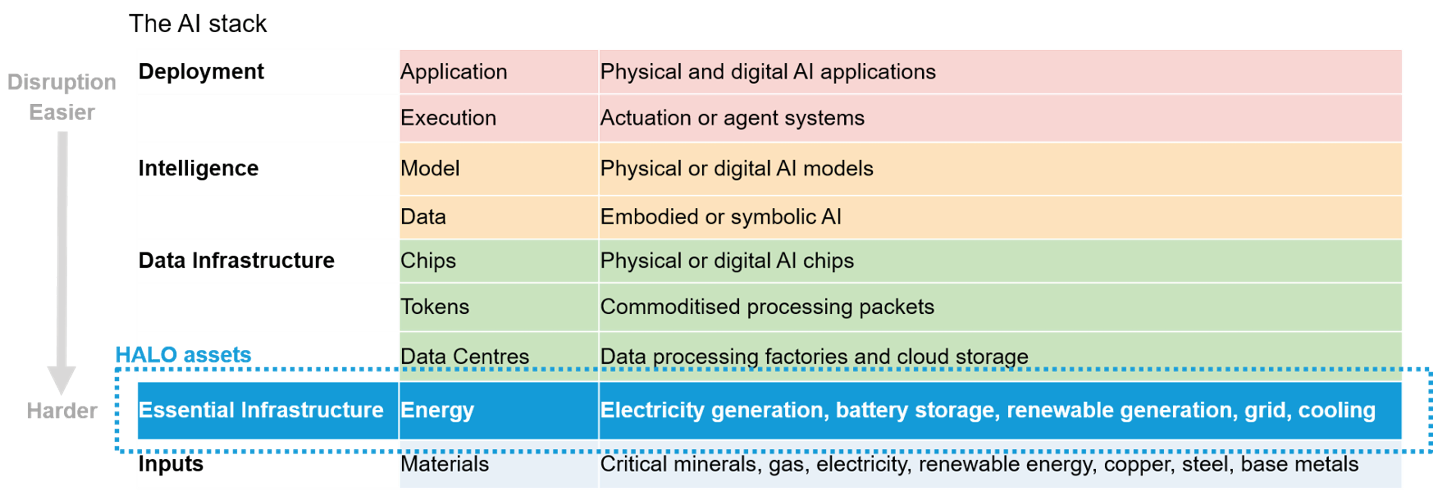
Source: Ausbil, adapted from Social Capital AI stack schematic that adds key resources inputs, and more clearly defines the role of essential infrastructure, as at May 2026.
While data centres could be considered essential infrastructure through a purely technological lens, we don’t define them as such – though their criticality to AI is beyond question.
Data centres operate in a highly competitive environment: users can switch providers dependent on price and capacity; contracts tend to be short in duration (3-5 years); and multiple hyperscalers are actively competing to sell capacity to end users.
Taken together, this falls short of our definition of essential infrastructure, which requires long-term contracted revenue..
Moreover, barriers to entry are not as high as for essential infrastructure assets as there are multiple hyperscalers competing in the tech build out to sell capacity to end users. Data centres are also exposed to relatively more rapid obsolescence risk than an essential infrastructure asset, where physical longevity and regulatory support underpin value over decades.
The quiet winners of the AI boom
Essential infrastructure is indispensable to data centres and therein lies the investment opportunity. The electricity grids, transmission networks, and utility assets that power hyperscalers sit upstream of the competitive fray, providing investors with what have been coined HALO assets. This offers exposure to the AI thematic with materially lower risk than data centre infrastructure itself.
At Ausbil, we believe that as AI adoption accelerates and demand for computing power grows, these enabling assets stand to benefit from the resulting surge in electricity consumption and network investment, supporting attractive long-term return potential for investors.
Tim Humphreys is Head of Global Listed Infrastructure at Ausbil. This article is for general information only and does not consider your personal circumstances. It is not personal financial advice. Please consider whether it is appropriate for you or seek professional advice before making investment decisions.