Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 363

How much bigger can the virus bubble get?

Stock markets are almost as expensive as they have ever been on a range of different measures. The economy is almost as bad as it has ever been on a range of different measures. Take note of the analysts who are contorting themselves trying to reconcile the two and telling you to keep buying. These are probably the same analysts who cheer-led the stock market at the peak of the Dot-Com bubble or just before the GFC.

Last week I wrote that we are being given a rare second chance to sell stocks. This week I’m interested in how much further the virus bubble can run before collapsing.

Will it run for years like the tech boom, or is it more like the 2015 China stock market boom and over in a matter of months?

Defining bubbles

It is important to know what type of bubble we are dealing with as this is not typical. I’ll look at it through the lens of James Montier’s four flavours for context:

  1. Fad or mania. These are the 'this time it is different' bubbles. The tech-boom, the Japanese bubble, the railroad boom of the 1800s, the South Sea bubble. These are the booms where the excitement over a new paradigm turns irrational. The virus bubble is not one of these.
  2. Intrinsic. These are bubbles which assume earnings will grow at an unsustainable rate forever. Financial stocks during the US housing bubble, resource stocks during commodity booms are examples. The virus bubble has elements of this as the assumption for many companies that earnings will recover quickly (and in some cases at all) is unrealistic.
  3. Near rational or greater fool. These are the bubbles where investors don’t believe the intrinsic value but figure there will be a greater fool prepared to bid the asset price higher. The Dutch tulip bubble is the best example. The virus bubble is not one of these.
  4. Informational. These bubbles see investors not act based on their own information. Instead, they are working on information revealed by others. i.e. stock markets are expensive, but if everyone else is buying, then they must know something I don’t. The virus bubble has elements of this.

What will pop the bubble?

Given the virus bubble is a mix of an intrinsic and an informational bubble, it gives us clues as to what the demise will be.

Informational bubbles end when other investors start selling and everyone stampedes for the exit. So, that is no help on timing.

Intrinsic bubbles end once the irrationality of the earnings is acknowledged. My best guess is a mix of bankruptcies and continued weak earnings will eventually do it. It might take six months. It might take six minutes.

A Biden win in the US election, or even the increased threat of one, has the potential to shock the market into a dose of reality with the spectre of higher taxes and wages eating into profits.

How much bigger can this bubble get?

As long as new money is flowing, the stock market bubble can keep growing.

This bubble does have a higher hurdle. Many bubbles come with increased profits which are reinvested and help to sustain the bubble. The virus bubble is the opposite, it needs new money just to fill the hole that reduced earnings and increased debt are leaving behind. Only after that can it grow.

There are four primary sources bubbles rely on for new money:

1. New investors

Globally there has been a rush of new, generally younger investors into the market. The numbers sound impressive. Robinhood, a popular new US trading platform, has added three million accounts this year. If you take the top four US online brokers, we can find another 3 million accounts in the first quarter alone. Australia, at less than a tenth of the size of the US, in a six week period 280,000 new and reactivated accounts, while UK firms reported up to 300% more new accounts in the first three months. It is a global phenomenon.

But these numbers need context. The tech boom in 2000 was also (in part) driven by new retail accounts, peaking at around 19 million US households with at least one trading account (noting a different definition of accounts) in 2001. That fell to 17 million a few years later where it has remained since.

If we assume 9 million new US accounts this year, and 65% already had a household account, that gives 3 million new households with accounts. That would put household accounts above the Dot-Com boom peak.

Two conclusions: (a) the numbers are significant (b) we have probably seen most of the increase in accounts already.

But has the increase been due to bored workers stuck at home? If so, with sport resuming, we may see retail stock market trading drop away.

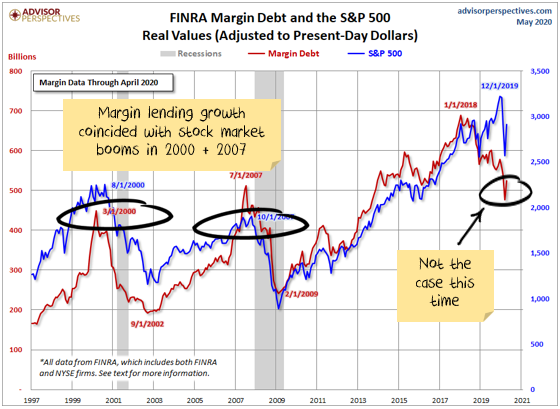
2. Increased gearing

Many booms involve a significant increase in debt to fuel asset price growth. This time around, however, it seems unlikely increased gearing has played a meaningful role in the boom.
3. Derivatives

The other way to obtain leverage is through derivatives which can increase the return and risk by many multiples of the investment. While the investor themselves might not be buying the stock, the market makers who are selling the derivatives need to purchase the shares to hedge against losses.

There has been a lot of additional derivative trading, with total option volumes close to double the five-year average and retail investors heavily involved.

4. Switching asset classes

The final way to get more money into a stock market bubble is to transfer money from other asset classes. This comes in two parts:

a) Central banks

Central banks are encouraging stock investment. By buying government debt, they are hoping to force investors to shuffle up the risk spectrum. Having said that, governments are also issuing massive amounts of debt.

So, to get investors to switch into equities, central banks need to buy more debt than what governments are issuing, otherwise the opposite will happen.

US government debt has increased from about US$23 trillion at the start of the year to about US$25 trillion at the beginning of May.

Over the same timeframe, the US Federal Reserve assets rose from US$4 trillion to US$7 trillion. US government debt will probably increase by about another US$4 trillion in 2020. So, if the US Federal Reserve does not also increase its balance sheet by $4 trillion, then money will flow into government bonds from other assets. The Fed will also need to increase its balance sheet to cover new corporate debt.

Then, repeat this problem in just about every country globally. Otherwise, money won’t continue to flow into the stock market.

b) Investors

According to the latest Bank of America survey, fund managers agree that the stock market is overvalued:
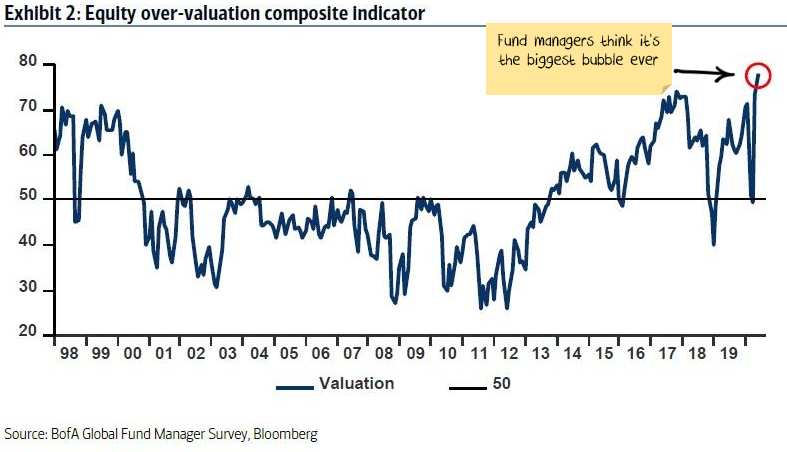
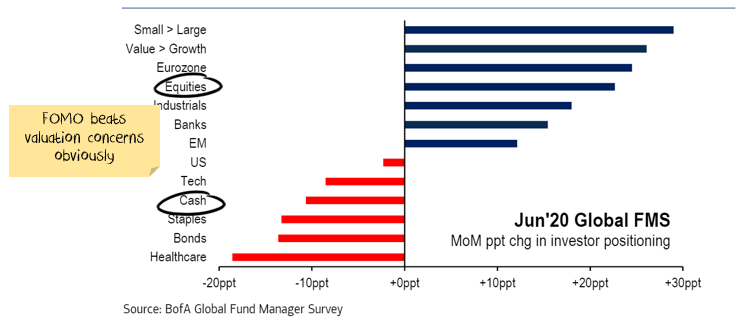
And in April (reported in May), they acted that way, with net sales of equities. But in May, Fear Of Missing Out (FOMO) took over, and they were buying stocks:
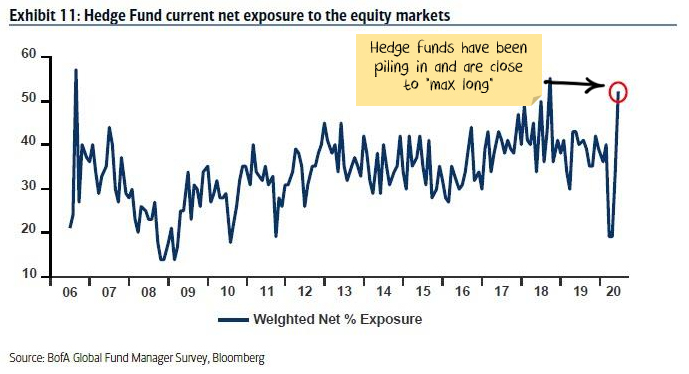
And hedge funds now have one of their highest ever weightings to the stock market, which suggests they are unlikely to buy much more.
Keep in mind that all bubbles are built on a grain of truth. That truth here is that central banks and governments ‘have your back’ and will buy anything and everything to keep the stock market high.

I think central banks will continue to bail out corporate debt markets where they can, but already we are seeing cracks with Hertz and several airlines filing for bankruptcy.

The more significant issue is small and medium businesses which (a) make up 50-70% of most economies (b) don’t have traded debt that central banks can buy.

Where does that leave us?

  • There are probably not that many new retail investors to add to the stock market.
  • There is scope to increase margin lending but no signs of that occurring.
  • Derivative use is already very high, probably can’t grow too much more.
  • Hedge funds (in aggregate) are a lot closer to their maximum equity exposure than their minimum. So not much more buying to come there.
  • Fund managers (in aggregate) talk a good game about overvaluation but are actually relatively fully invested and so don’t have a lot of scope to buy more equities.
  • Central banks are running hard just to keep up with government and corporate bond issuance. It is possible for central banks to do more. They are the bull’s best hope for an extended bubble.

The US tech Dot-Com boom took about two years to play out but was a different type of bubble. The China 2015 Bubble took four months before economic reality sunk in.

I expect the virus bubble will be closer in timeframe to the China bubble than to the Dot-Com bubble. But bubbles often last longer than seems reasonable.

It has been a surprisingly raucous party in share markets, but the hour is late, and the party seems to be dying down. Some partygoers are trying to find more alcohol to keep the party going. They may be successful. Regardless of their success in extending the party, given the amount of alcohol already consumed, investors will feel a lot better in the morning if you leave the party now.


Damien Klassen is Head of Investments at Nucleus Wealth. This article is general information and does not consider the circumstances of any investor.


  •   24 June 2020
  • 12
  •      
  •   
12 Comments
Chris
June 23, 2020

Better tell that to the people over at the Reddit group "ASX_bets"

Regina Davern
June 24, 2020

I agree completely. The rises are irrational! I have been waiting for investors to wake up to the massive loss of jobs, including Qantas sacking 6000 people today. Investors have been given a second chance to get out but I doubt this will happen until something is big enough to burst the bubble!

Ajay
June 24, 2020

The last metaphor about party-goers and the alcohol already consumed sums it up in a way most will understand.

matthew smith
June 26, 2020

I am not sure I understand. Let the good times roll I say.

Jeff Oughton
June 25, 2020

5 drivers for the pessimists to ponder
1. Real rates are down ...and expected to stay down
2. UMP is lowering risk premia.
3. Precautionary household savings are available for spending - once confidence returns about the virus...especially about a vaccine
4.Confidence is recovering
5. Positive signalling about fiscal stimulus - we'll do what ever it takes

Economic activity bottomed in late April/early May

Notwithstanding the risks...and "true ambiguity" , markets have bounced and "waiting & seeing" ...with forward earnings and valuations reflecting bifrufication - go growth/go tech/ go the winners, leaving losers behind!

Moray
June 25, 2020

I think the likely trigger could be infection rates (followed by death rates) rising in the US such that states need to shut down their economies to contain it. There are many who think the US states will not shut down, but we are already seeing this in a small way with intra US state travel bans and regardless citizens will make their own risk assessments of what they need to do to protect themselves - "shelter at home" for those who can afford it as those who can't continue to potentially spread the virus and a potentially overwhelm the healthcare system (for those that can afford it). I think we'll know in 3 months at the outside

D Heath
June 27, 2020

Nope, We are much better off now in late June compared to March. Back then we did not know whether or not lock-downs would stop the spread. With say an 80% contamination rate and 2% mortality rate there would be around 8m deaths in the US alone. This is not going to happen so the worst case scenario has been avoided so far and we are close to treatments/vaccines now. I have more faith in the Fed compared to your ideological arguments. And the Fed did the right thing in the GFC - I wish we had more wisdom here in Australia. The NASDAQ is up more than 20 times over 30 years - compare this to the all Ords. Good luck with your pessimistic outlook.

Tony
June 29, 2020

Sound like you are placing your faith in central banks and MMT. Not sure this final round of can kicking can keep asset prices inflating, but will be fascinating to watch how this plays out.

AlanB
June 30, 2020

You are right for all the reasons given and wrong for all the reasons not given. Bubbles are short term phenomenon. We've always had them and always will. Long term investors just ride out the peaks and troughs of the market. Think of it not as a bull or bear market, but a kangaroo market. When one party ends, sleep it off and await the next one.

Gilbert
July 01, 2020

Market performance is by definition determined by active market players. Market price is no fair value and by its nature gives an illusion of one's financial wealth. Asset price inflation is merely paper wealth unless and until it's converted into cash flow into one's pocket

Peter Jacobsen
July 01, 2020

As many sensible analysts have said, "the only casino open in the USA is the stock market" and with so many "educated" millennials confined to quarters they are gambling on the market. Australia's market almost slavishly follows the US market so when it hits the fan there we will surely follow, I am sitting on cash till the bubble bursts!

SMSF Trustee
July 02, 2020

I really hate that terminology.

The stock market is NOT a casino. When was the last time that, owning the market (ie a broad portfolio of stocks) that you lost all your money? It hasn't happened, has it?

People who either by leverage or by short term punting (or both) gamble using the stock market is an entirely different thing. But the stock market itself is just the value of the listed entities on that market. It trades with some volatility, but it's not like casino where you put your money down and either win big or lose it all. That's total nonsense.


Leave a Comment:

RELATED ARTICLES

Is the speculative fever in 'hot stocks’ over?

The coiled spring: markets are primed for the year ahead

The whirlwind is upon us

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.