Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 349

Your super fund will pay you to leave - UPDATED

Since the first publication of this article on 22 March 2020, both UniSuper and AustralianSuper have announced they will revalue their unlisted assets.

CEO Ian Silk said on 24 March 2020:

"The values of all investment portfolios have been adjusted to reflect the economic and financial market impacts of Covid-19. Unlisted assets have been reduced by 7.5% on average, which has resulted in a 2.2% reduction of the balanced option effective yesterday." 

This means that members can no longer switch to cash and avoid the fall in price.

-----

Most large superannuation funds have significant investments in unlisted assets. Many are telling you that these assets have not lost value despite sharemarkets falling 30%+ across the world. This gives rise to perverse incentives for superannuants:

  • If you leave one of these funds now, you will get paid at the high prices for unlisted assets
  • Anyone left behind bears the brunt of the losses when the revulation hits values.

Rough numbers? I suspect right now that the median superannuation fund will pay you about 7% to leave.

Disclosure: Some of this is probably sour grapes! I run a superannuation fund that only buys liquid assets in separately managed accounts. So, an investor's return is their return with all assets revaued at market prices. We can't rely on tax mingling, unlisted asset revaluations or accounting tricks that master trusts use.

Chant West gave us a preview of superannuation fund returns for March 2020:

"Growth funds, which is where most Australians have their superannuation invested, hold diversified portfolios that are spread across a wide range of growth and defensive asset sectors. This diversification works to cushion the blow during periods of share market weakness. So while Australian and international shares are down at least 27% since the end of January, the median growth fund's loss has been limited to about 13%."

Here's some quick maths on the likely impact

Chant West's definition of a growth fund is one that has 60-80% of its portfolio in 'growth' assets. Let's call it 70% exposure to shares, 5% cash and 25% to a composite bond fund.

If shares are down ‘at least’ 27%, cash is unchanged, and a composite bond fund is down about 5%, then the implied return is a loss of -20%.

Chant West says the loss is only 13%. There is 7% missing.

My calculation assumes that the 25% is in composite bonds, but it is more likely in higher-risk unlisted assets.

So where is the missing money?

Now, each super funds will obviously have different assets and performance. For example, own growth fund is only down 0.8% over the same time frame but we took aggressive derisking measures at the end of January.

The superannuation market is about $3 trillion. It is the market. If, somehow, almost every superannuation fund worked out the same thing we did and sold equities in January, the market would have fallen in January.

The answer is superannuation funds have unlisted assets that they are not writing down. In the February 2020 ASFA statitics on large fund assets, the average allocations to unlisted assets were property 5%, infrastructure 6% and equity 4%, a total of 15%, but some individual funds would be much higher. 

For example, many retail funds hold assets with greater liquidity to meet redemptions, whereas industry funds rely more on continuous inflows of contributions for liquidity, allowing holdings of more illiquid assets.

They are pretending that the prices are mostly unchanged from January, but the world has changed since then.

Financial crisis comparison

A great example is unlisted property funds during the GFC. Unlisted property funds invest in effectively the same assets as listed property funds, the underlying properties are worth the same, the performance differs because of how it is reported and the revluation method.
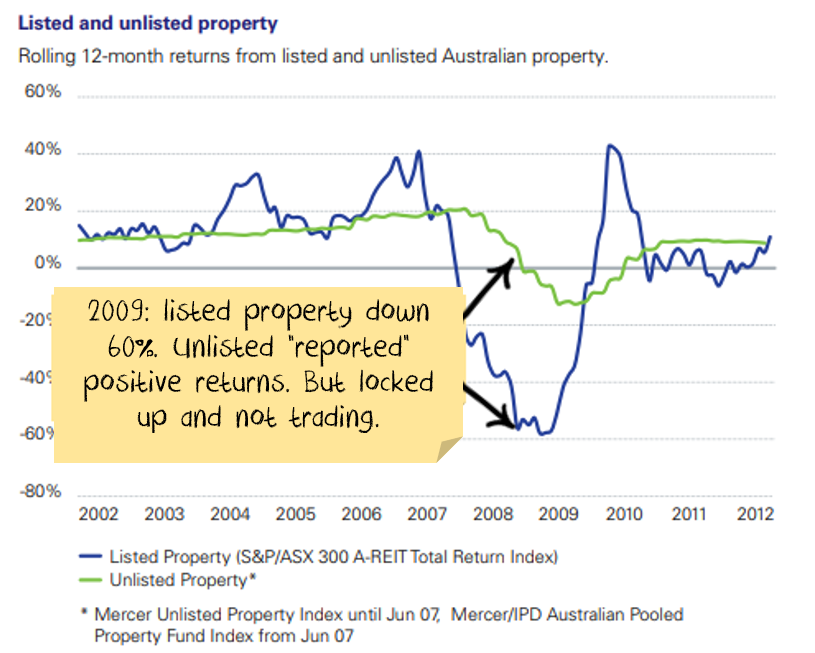
The perverse superannuation incentive

The problem is that if you invest in a fund that reports like this, you can be diluted if other investors leave. They receive the higher assumed price, and any new contributions you make now are at inflated prices.

To illustrate with an extreme example, let's say:

  • You and I are the only investors in a super fund with $100 each invested
  • The fund owns 50% in an unlisted asset and 50% in cash. So, the total value of the fund is $200 made up of $100 in the asset and $100 in cash
  • The asset falls 60% ($60) in price, so our fund is now only worth $140 ($70 each), but the fund doesn't revalue the asset and so reports the fund still being worth $200
  • I decide to redeem my holding in the fund
  • The unlisted asset can't be easily sold, and so the fund pays me $100 cash being half of the $200 that the fund is still being officially valued at.
  • This leaves you with $40 of unlisted assets – double the loss that you should have taken.

Adding insult to injury

The other problem with a typical superannuation fund (but not some of the newer ones that use a separately managed account structure) is your tax is mixed with other investors. Rodney Lay from IIR recently wrote:

" ... unit trust investors face another risk – being subject to the taxation implications of the trading activities of other investors. Net redemption requests may require the manager to sell underlying portfolio holdings which, in turn, may crystallise a capital gain ... During the GFC some investors had both (substantial) negative returns plus a tax bill on the fund’s crystallised gains. Good times!!!"

Net effect for loyalty

Not all super funds hold the same proportion of unlisted assets, but if you are a loyal soldier sticking with a superannuation fund that continues valuing unlisted assets at last year's prices then:

  1. You will probably absorb the losses of anyone that leaves
  2. You might even get an additional tax bill because the people that leave trigger a CGT event for you.

But at least your superannuation fund will be able to ‘report’ higher returns.


Damien Klassen is Head of Investments at the Macrobusiness Fund, which is powered by Nucleus Wealth. This article is general information and does not consider the circumstances of any investor.


  •   18 March 2020
  • 2
  •      
  •   
2 Comments
Gary M
March 21, 2020

This is a big issue. In the past, it would be argued that infrastructure like airports and toll roads have long-term income streams and can be revalued infrequently. This time is different. Traffic in both has fallen off a cliff and will remain that way for at least a year. The market has spoken in revaluing them downwards (Transurban from $15 to $10). How can managers and trustees pretend the unlisted is worth the same?

George
March 24, 2020

Rainmaker says funds with more unlisted assets have performed better ... why ... because they are unlisted. Does that make them worth more?

"Big Super players like AustralianSuper and UniSuper have experienced losses of around 10 per cent and 13 per cent respectively on their balanced funds…

Mercer data estimated that diversified growth or balanced funds experienced losses of between 11 and 12 per cent, giving an overall damage count broadly on par with Rainmaker’s $290 billion. The figures are over the period from late February to close of trade on Monday.

Craig Hughes, director of investment consulting at Mercer Australia, said the key differentiator was asset allocation by funds to unlisted investments such as property and infrastructure…

“Portfolios that are heavily or wholly weighted to listed assets like listed equities and bonds have performed a lot more poorly than the average, as high as minus 16 per cent or minus 18 per cent,” Mr Hughes told the Financial Review. “Those with more unlisted assets have performed better, closer to the minus 10 range.”


Leave a Comment:

RELATED ARTICLES

Take my money and lie to me… again

The million-dollar banana and the power of story

Darryl and Sal Kerrigan are now private equity investors

banner

Most viewed in recent weeks

Division 296: the initial moves to make before the windows close

What if the best superannuation strategy isn't about earning more, but acting before your options disappear? Several overlooked planning windows are narrowing, with consequences that can last for decades.

The retirement scorecard: how many of these questions can you answer?

From the maths of retirement, estimating spending and picking the right asset allocation to survive a poor decade, here are the questions every retiree – current or future – should be able to answer for themselves.

Testamentary trusts: Treasury has picked the wrong reading

A decades-old estate planning tool has survived one tax crackdown only to be caught by another. The surprise isn't who the reform is targeting, but who could end up paying the price for drafting choices made years ago.

Superannuation’s structural failings

Politicians are fighting over access to super, but they may be arguing about the wrong thing. The system’s three fundamental flaws have been hiding in plain sight for decades, costing Australians far more than they realise.

Avoid unnecessary CGT with this estate planning clause

A simple estate plan can create a ticking time bomb. One overlooked clause can pit spouses against children, delay inheritances, and potentially leave a family facing an unexpected tax bill worth hundreds of thousands of dollars.

Does an American retirement rule work for Australians?

The 4% rule has survived decades of scrutiny, but Australia's retirement system changes the equation in ways most overlook. Before accepting or rejecting this rule of thumb, it pays to understand what really drives retirement outcomes.

Latest Updates

Superannuation

Bill Kelty: Super can't solve everyone's problems

One of the key figures behind Australia’s superannuation system reflects on how it began, what has changed, and why some of today’s biggest debates may be asking too much of a retirement savings system.

Investment strategies

Rising yields have put bonds back in business

For the past decade, investors were forced to chase income wherever they could find it. With yields now offering competition to dividends, the new challenge is deciding whether they're still being adequately rewarded for risk.

Strategy

Do you want a bucket with that?

Retirees, advisers and super funds all talk about the bucket strategy as if it's one thing. It's not. The differences can be significant, and some may matter far more than investors realise when markets become volatile.

Investment strategies

What The Odyssey can teach us about valuation discipline

Investment temptations are hard to resist in the moment, but successful investing is not about ignoring compelling opportunities or ideas. For value investors, the smart move is to prepare before momentum clouds judgement.

Shares

Does market concentration really mean more risk for investors?

One of the most closely watched trends in global markets has become a growing source of investor concern in recent years. Whether that concern is justified, however, turns out to be a far more complicated question.

Retirement

Retirement in reality - 8 months in

Health goals, new friendships and lingering questions about identity have dominated this month. The experience has challenged widely held beliefs about purpose, belonging and what it really means to leave work behind.

Shares

Stagnation might be OK at this point

Australia's economic problems are hardly a secret. The more interesting question for investors is whether the stock market is as exposed to those problems as commonly assumed, or whether the picture is more nuanced.

Sponsors

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.