The US market is extremely concentrated, and the bears say 2026 could be 1999 all over again. As in the dot-com boom, a new technology promises to change everything and capital spending is enormous. The Magnificent 7 plus Broadcom, AMD and Micron, the ‘AI Big 10’, now account for 42% of US stock market value. At the height of the dot-com bubble in 2000, the technology, media and telecom (TMT) sector peaked at 41%. Most past bubbles peaked at around 40%.
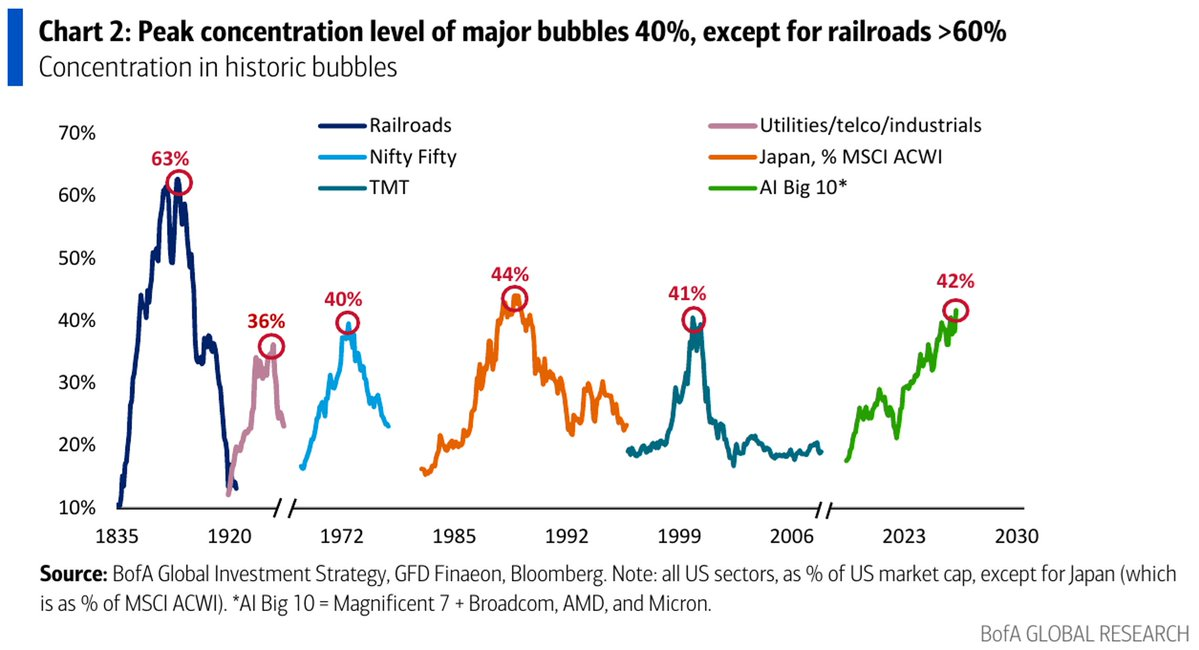
But concentration alone does not make a bubble. The better test is how the market leaders are priced.
1999: a boom that lifted everything
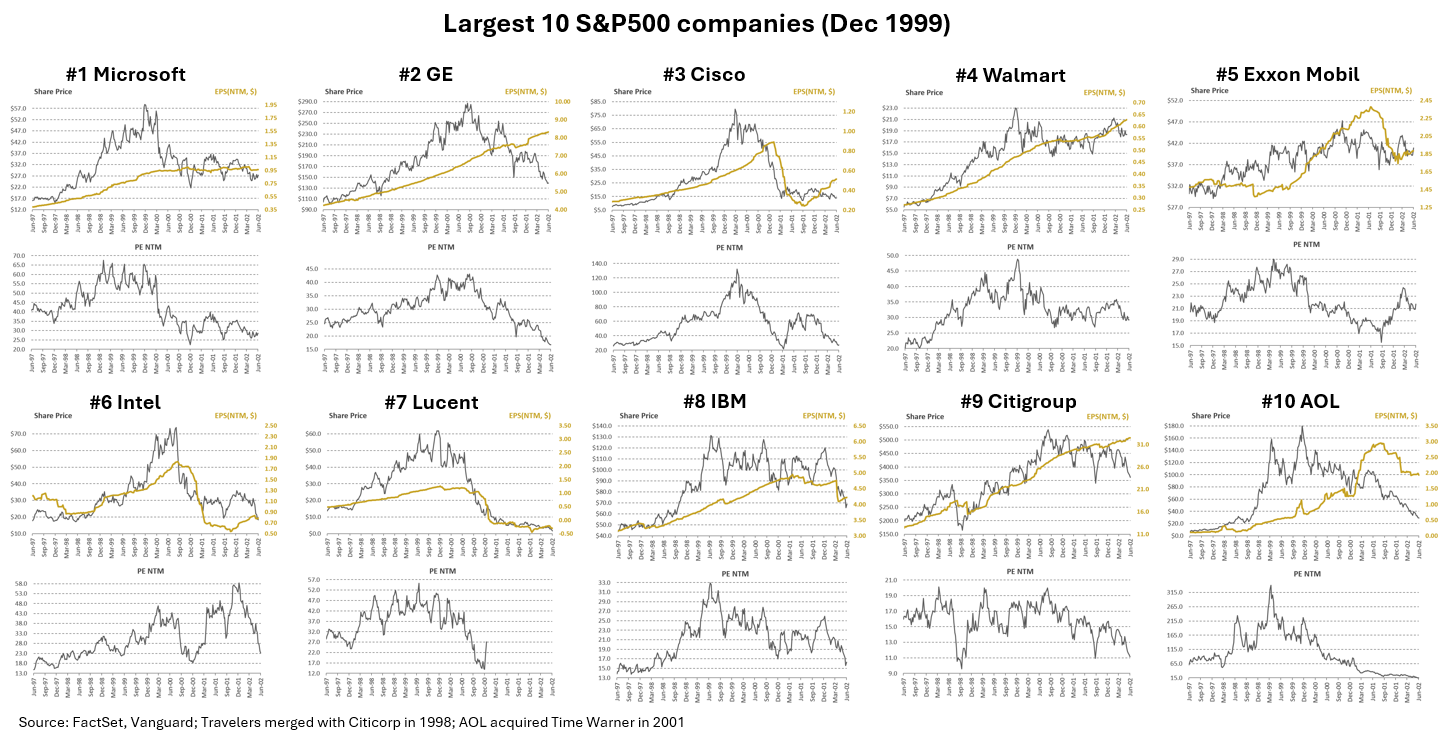
The 1999 earnings boom reached most of the economy. Nine of the ten largest companies in December 1999 saw their forward PE expand sharply. The biggest re-ratings came from the purest internet plays, Cisco and AOL. Only Citigroup's PE was relatively stable. The charts show each stock's share price, next-twelve-month (NTM) earnings and NTM PE from mid-1997 to mid-2002.
Why it boomed, and why it burst
Four forces drove the TMT boom. Each later reversed and caused the bust.
The first was Y2K. Fear that two-digit dates would crash systems on 1 January 2000 drove an estimated $300 billion to $600 billion of IT spending worldwide, pulling forward years of upgrades. Microsoft gained from the surge in PC demand, and most of those PCs ran on Intel chips. IBM's windfall came as companies upgraded their servers. When the date passed, orders dried up and left excess inventory across the technology supply chain.
The second was a debt-fuelled telecom build-out. Hundreds of unproven new carriers raised tens of billions in junk bonds to lay fibre, and equipment makers such as Lucent and Cisco lent them money to buy their gear. As orders boomed, Cisco's forward PE more than quadrupled. Lucent's rose less, because much of its revenue came from slower-growing voice equipment. When credit froze in 2000, the carriers defaulted and hit the lenders hard. Telecoms made up more than half of the roughly $160 billion of North American high-yield bond defaults in 2001 and 2002. The fibre outlived the companies that laid it. Most of it sat unused for years, and it took over a decade for broadband, streaming and cloud computing to fill it.
The third was the equity-fuelled dot-coms. Soaring valuations made equity cheap to raise, and a wave of loss-making IPOs followed. AOL was the largest and most profitable pure internet company in the index and its forward PE tripled from an already high base. In January 2000 it agreed to pay about $165 billion in its inflated stock for Time Warner. When the equity window shut, Pets.com, eToys and Webvan ran out of cash and folded. AOL Time Warner survived but wrote down about $99 billion in 2002.
The fourth was cheap money. After Russia defaulted and the hedge fund LTCM nearly collapsed, the Fed cut rates three times in late 1998, to 4.75%, into an already strong economy. Asset prices took off, and even non-technology stocks such as GE, Walmart and Exxon Mobil re-rated. By June 1999 the Fed concluded the economy was overheating and raised rates six times, to 6.50% by May 2000.
The turn came in March 2000, when news that Japan had slipped back into recession sparked a global sell-off. The S&P 500 fell 49% by October 2002 and the Nasdaq 78%. For strong companies, the rout was driven largely by collapsing multiples. The S&P 500’s forward PE fell from a peak of 26.7x to 14.4x. The highest multiples fell furthest. Cisco's forward PE fell from about 132x to about 30x, and AOL's from about 315x to about 15x. Weaker companies saw their businesses break. Lucent’s shares fell 99%. WorldCom, the second-largest US long-distance carrier, filed for bankruptcy in July 2002 after an accounting fraud later put at $11 billion. It was the largest bankruptcy in US history at the time.
Australia had its own version of the TMT boom and bust. Sausage Software’s shares reached A$40, valuing it at close to $1 billion. Davnet floated at about 4 cents and traded above $4 before the crash. One.Tel, backed by the Packer and Murdoch families, was worth $5.3 billion in November 1999 and collapsed into administration in May 2001. Retail investors bought Telstra’s second float at A$7.40 in October 1999. A month later the shares reached A$9.16, about 30 times forward earnings. By late 2001 they had fallen to about A$4.80, and the multiple had halved to about 15 times, with earnings little changed.
2026: a narrow AI boom
The 2026 earnings boom can be traced back to November 2022, when OpenAI launched ChatGPT. It reached an estimated 100 million monthly users within two months, at the time the fastest ramp of any consumer app. Six months later, NVIDIA's GPU sales gave the first hard evidence of the spending under way behind the scenes. On 24 May 2023 it reported record data centre revenue and guided to $11 billion of sales, roughly 50% above market expectations.
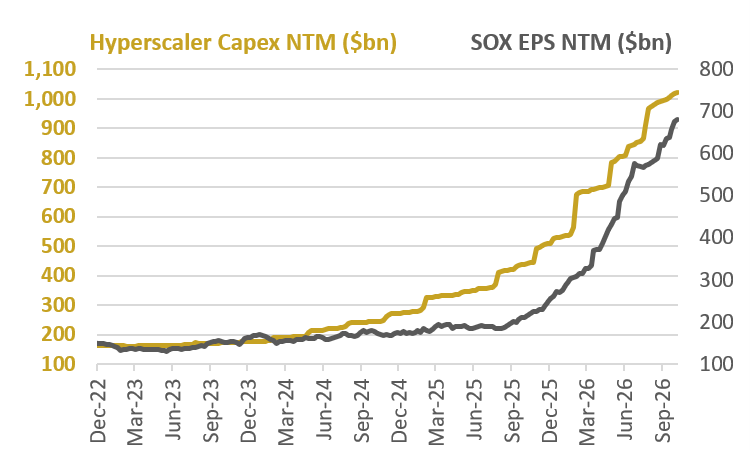
The result revealed an AI arms race among the hyperscalers: Microsoft, Alphabet, Amazon, Meta and Oracle. Each feared that falling behind would cost more than overspending. Their combined capital spending over the next 12 months is forecast at a little over $1 trillion, more than six times the $162 billion forecast when ChatGPT launched. That spending has flowed through the semiconductor supply chain, from equipment makers such as ASML to TSMC, NVIDIA and the memory makers. Forward 12-month earnings for the PHLX Semiconductor Index (SOX) rose 216% in the year to September 2026.
Source: FactSet
Those gains have made the 2026 S&P 500 earnings boom narrower than 1999’s. Profits are concentrated in the chipmakers and the hyperscalers. As a result, semiconductor stocks now make up a record 20% of the S&P 500, more than double their weight at the peak of the dot-com bubble.
Four differences from 1999
The boom rests on a large infrastructure build-out, as the TMT boom did. But the four forces that drove 1999 are absent or much weaker.
First, there is no pull-forward of demand. Y2K pulled forward years of upgrades against a fixed deadline. AI demand has no such cliff. Nor is there an overbuild. In the late 1990s, new telecom carriers laid fibre on speculation, with no customers signed. By 2002, only 2% to 5% of US fibre was lit. Today’s build is mostly to order. The hyperscalers build for their own cloud services, which are growing fast. In the June 2026 quarter, Google Cloud grew 82% year on year, Azure 43% and AWS 37%. More than 80% of North American data centre capacity under construction is leased before completion, up from 74.3% a year earlier. Overcapacity remains a risk, but nothing like the fibre glut.
Second, funding. The fibre build-out ran on junk debt. The AI build-out is led by the hyperscalers, among the most profitable companies in the world. They have low gearing and have funded most of it from operating cash flow. The exceptions are neoclouds such as CoreWeave and Nebius, which are forecast to carry about $100 billion of net debt between them, around five times forecast EBITDA.
NVIDIA's vendor financing is the closest parallel to Lucent's and Cisco's. NVIDIA has agreed to buy $29 billion of unsold cloud capacity and to guarantee up to $105 billion of OpenAI's data centre leases. It has also taken stakes in builders such as Australia's Firmus. Its guarantees and capacity commitments come to 22% of forecast revenue, against 13% of reported revenue at Cisco and 21% at Lucent in 2000. The difference is the borrower. Lucent and Cisco lent to start-ups with little revenue. OpenAI has large revenue but still loses money. This is the part of the boom that most resembles 1999.
Third, the speculative fringe is far smaller. In 1999, nearly 80% of the 476 US IPOs were technology companies, and three in four were loss-making. In 2026, fewer than 100 companies have listed so far, and the leading AI developers have real revenue. OpenAI's grew 3.5-fold in 2025 to $13.1 billion, and Anthropic's June-quarter revenue was reportedly $11.5 billion, 14.6 times a year earlier.
Fourth, money. In 1998, cheap money lifted multiples, and the market shrugged off three rate rises in 1999. In 2026, one rise was enough to rattle the market. After the Fed raised rates to 3.75% to 4.00% in September, the S&P 500 equal-weight index’s forward PE fell 8%, from 16.6 to 15.3 times, even as forward earnings kept rising.
How the 2026 leaders are priced
Both periods had an earnings boom. The difference is what investors paid for it. In 1999, nine of the ten largest companies re-rated. In 2026, only two have: Apple and Tesla. The charts show each stock over the five years to October 2026.
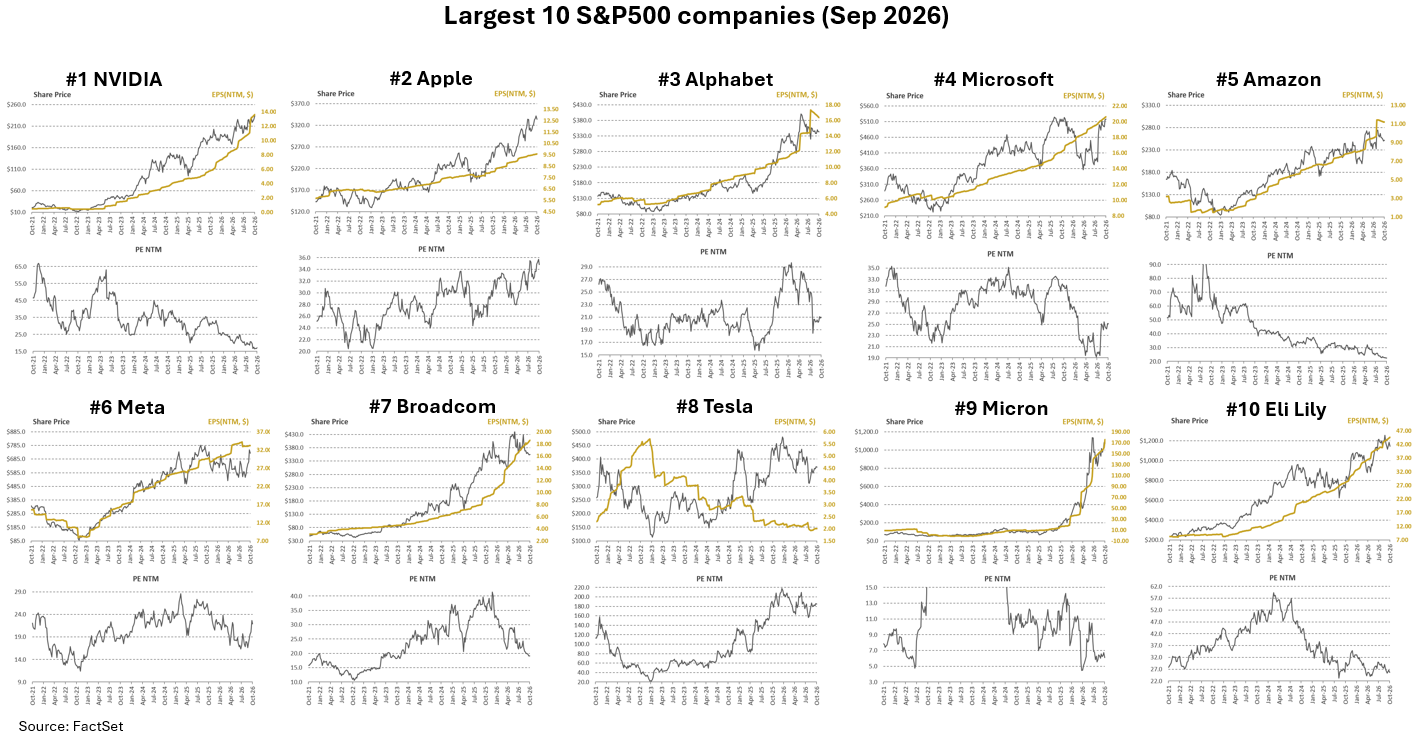
For the other eight, earnings have risen faster than share prices. The market is pricing the chipmakers (NVIDIA, Broadcom and Micron) as cyclicals near peak earnings. The hyperscalers (Alphabet, Microsoft, Amazon, and Meta) have de-rated on doubts about the return on their capital spending.
NVIDIA shows the shift in sentiment most clearly. It is the main supplier of the AI build-out, as Cisco was of the internet’s. Both enjoyed an earnings boom from a new technology wave. But Cisco’s forward PE more than quadrupled, to 132x at the March 2000 peak. NVIDIA’s has more than halved over the past two years, to 17x. In 1999 the market priced Cisco’s earnings as if they could only go up. Today it prices NVIDIA’s as cyclical.
Conclusion
The exuberance of the 1999 bubble reached the very top of the market. Nine of the ten largest companies re-rated in the run-up to the peak. Cisco, the bellwether of the internet boom, saw its multiple more than quadruple.
The market is as concentrated in 2026, but for the opposite reason. In 1999, rising multiples lifted the leaders. In 2026, profits have flowed to a handful of chipmakers and hyperscalers. Eight of the ten largest companies trade on lower multiples than five years ago. NVIDIA’s multiple has more than halved, even though it is one of the biggest beneficiaries of the AI boom. Investors are paying for earnings, not for hope.
The 2026 AI earnings boom is real, and it will cool when capital spending slows. Investors are already pricing it as a cycle. Parts of 1999 remain in vendor financing and neocloud debt. What is missing is extreme speculation that defined that bubble.
Jason Teh is a financial commentator and portfolio manager. This article is general in nature and does not constitute or convey personal financial advice. It has been prepared without consideration of anyone’s financial situation, needs, or financial objectives. Before acting on the areas discussed and contained herein, you should consider whether it is appropriate for you and whether you need to seek professional advice.