Register For Our Mailing List

Register to receive our free weekly newsletter including editorials.

Home / 233

Asset class performance and lessons in 2017

Better than as good as it gets

2017 goes down in history as the 6th consecutive year of positive real total returns from all major asset classes for Australian investors – Australian shares, global shares, Australian and global bonds, listed and unlisted commercial property, housing and bank deposits. Six straight years when everything went up has never happened before in history.
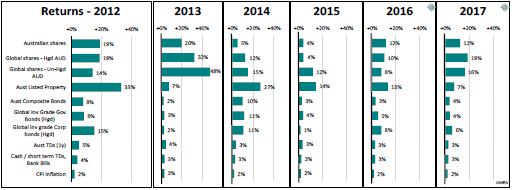
Click chart to enlarge

The next longest period was four positive years in 1925-28 during the great post-war housing and government spending boom. No prizes for what happened next: the 1929 crash, 1930s depression and defaults by NSW and Commonwealth governments.

Periods of negative real returns from the major asset classes together are relatively rare and short-lived. There were only four individual years where major asset classes posted negative returns together:

  • 1912 –War build-up in Europe, US dismantling the Money Trusts, Titanic sinking
  • 1941 – Hitler invading Russia, Pearl Harbour bombing, Japanese army storming down through Asia.
  • 1948 – Industrial unrest, communist agitators, Australian bank nationalisation crisis, Soviet blockade of Berlin
  • 1973 – Australian monetary tightening, severe credit squeeze, Britain entering ECM, USD devaluation, Yom Kippur oil crisis

What is the common thread that runs through all of these positive and negative return periods? Inflation.

Each of the periods of across-the-board negative real returns had high inflation. Conversely, each of the periods of across-the-board positive real returns had low inflation, including the current six-year rally.

Will markets remain positive for another year to make it seven years in a row? All types of assets everywhere are expensive, but shares, property and bonds tend to do well when inflation and interest rates are low. The good news is that inflation and interest rates are still very low in Australia and around the world and are likely to remain that way for some time yet.

Portfolios and lessons

With each of the main asset classes posting positive returns in 2017 it was difficult to lose money.
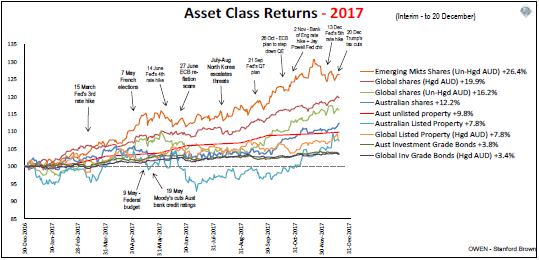
Click chart to enlarge

The active positions that paid off for investors in 2017 include:

  • In Australian shares – bias toward small/medium versus large companies paid off as the big banks dragged on the market
  • In global shares – over-weighting ‘emerging markets’ shares paid off as Chinese tech stocks in particular were very strong
  • In global shares – bias toward hedged versus unhedged as the AUD rose
  • Within fixed rate bonds – bias toward corporate versus government bonds paid off as credit spreads contracted but no benefits from running floating versus fixed rate bonds.

As far as regrets go, it is easy to look back with the benefit of hindsight and say (for example), “We should have had more global shares”. However, it was hard to argue for an overweighting to global shares when they were so expensive at the start of the year and with the Brexit vote and Trump election so fresh in the minds of our investors.


Ashley Owen is Chief Investment Officer at advisory firm Stanford Brown and The Lunar Group. He is also a Director of Third Link Investment Managers, a fund that supports Australian charities. This article is general information that does not consider the circumstances of any individual.


  •   1 January 2018
  •      
  •   


Leave a Comment:

RELATED ARTICLES

Only 2.4% of companies deliver all net shareholder wealth

Spotting signs of trouble in a retirement portfolio

Where do Australian share returns come from?

banner

Most viewed in recent weeks

Why spending more in early retirement can improve lifetime income

Conventional wisdom encourages retirees to preserve superannuation. But if those likely to qualify for the Age Pension later in life spend a little more today, it may deliver higher lifetime income and a more stable retirement.

Testamentary trusts have secured the CGT exemption

Treasury’s latest CGT reform draft delivers a win for testamentary trusts and deceased estates, exempting estate-derived gains from the 30% floor. However, questions on death and divorce rollovers remain unresolved.

Meg on SMSFs: What do we think about reversionary pensions these days?

Reversionary pensions have long been a staple of SMSF estate planning, but are they still the best option? Meg Heffron revisits a once-clear favourite and asks whether changing super rules have shifted the balance.

Is it time to bail on Australian stocks?

For generations, Australian investors have backed banks, miners and dividends. But has that loyalty come at a cost? A look at the numbers raises an uncomfortable question about where future returns will come from.

How does the 4% rule stack up?

The 4% rule has long been retirement's gold standard. But after a difficult period for investors, fresh analysis suggests a more conservative approach may significantly improve the chances of making savings last.

Testamentary trusts survived the trust tax. The drafting battle has just begun.

The fight over testamentary trusts looked settled. Then the draft legislation arrived. Hidden in a technical detail is a question that could force many families to rethink wills they thought were already future-proof.

Latest Updates

Planning

How the typical Australian Family could save $844,350 in taxes

The value of a testamentary trust is not determined by wealth alone. Depending on circumstances, it can reduce the tax burden on inherited income, create efficiencies and help build intergenerational wealth.

Superannuation

There's a reason why your super is locked up until your 60s

For decades, it seemed settled. Then one controversial idea reignited a debate that could reshape the financial future of millions. The real question isn’t who’s right or wrong, but whether a long-held assumption deserves another look.

Property

The housing slide could become a crash

House prices are sliding across Australia, yet the most dangerous ingredient for a housing crash is still missing. If job losses surge amid growing economic risks, today's correction could become a historic property downturn.

Retirement

Under-retiring: The greatest retirement risk in a generation

Two retirees. Similar savings. Completely different lives. New research from Challenger reveals why some Australians confidently spend in retirement while others hold back and the overlooked factor shaping retirement decisions.

Five risks to watch in markets

Things you may often hear are: a recession is around the corner, markets are overpriced, the AI sector is about to flop at any moment. It’s like the never-ending laundry pile that sits in my house, it never really disappears.

Investment strategies

Do you qualify as ‘rich’?

What does it mean to be 'rich'? For something so universally desired, it is surprisingly difficult to define. That ambiguity creates a challenge for investors and raises a bigger question about what financial success really looks like.

Investment strategies

If you’re worried about your bond portfolio, you’re missing the point

Most investors think they know what bonds are for. But when markets turn volatile, a surprising misunderstanding can lead to costly decisions. Here’s the overlooked lesson that could change how you view your portfolio.

Alliances

  • ASA-Logo-RGB-ActiveGreen-web.png

© 2026 Morningstar, Inc. All rights reserved.

Disclaimer
The data, research and opinions provided here are for information purposes; are not an offer to buy or sell a security; and are not warranted to be correct, complete or accurate. Morningstar, its affiliates, and third-party content providers are not responsible for any investment decisions, damages or losses resulting from, or related to, the data and analyses or their use. To the extent any content is general advice, it has been prepared for clients of Morningstar Australasia Pty Ltd (ABN: 95 090 665 544, AFSL: 240892), without reference to your financial objectives, situation or needs. For more information refer to our Financial Services Guide. You should consider the advice in light of these matters and if applicable, the relevant Product Disclosure Statement before making any decision to invest. Past performance does not necessarily indicate a financial product’s future performance. To obtain advice tailored to your situation, contact a professional financial adviser. Articles are current as at date of publication.
This website contains information and opinions provided by third parties. Inclusion of this information does not necessarily represent Morningstar’s positions, strategies or opinions and should not be considered an endorsement by Morningstar.